ClarityVesting uses analytics and measurement cookies to improve the website's content and understand how visitors discover the site. By accepting, you help build a better experience.
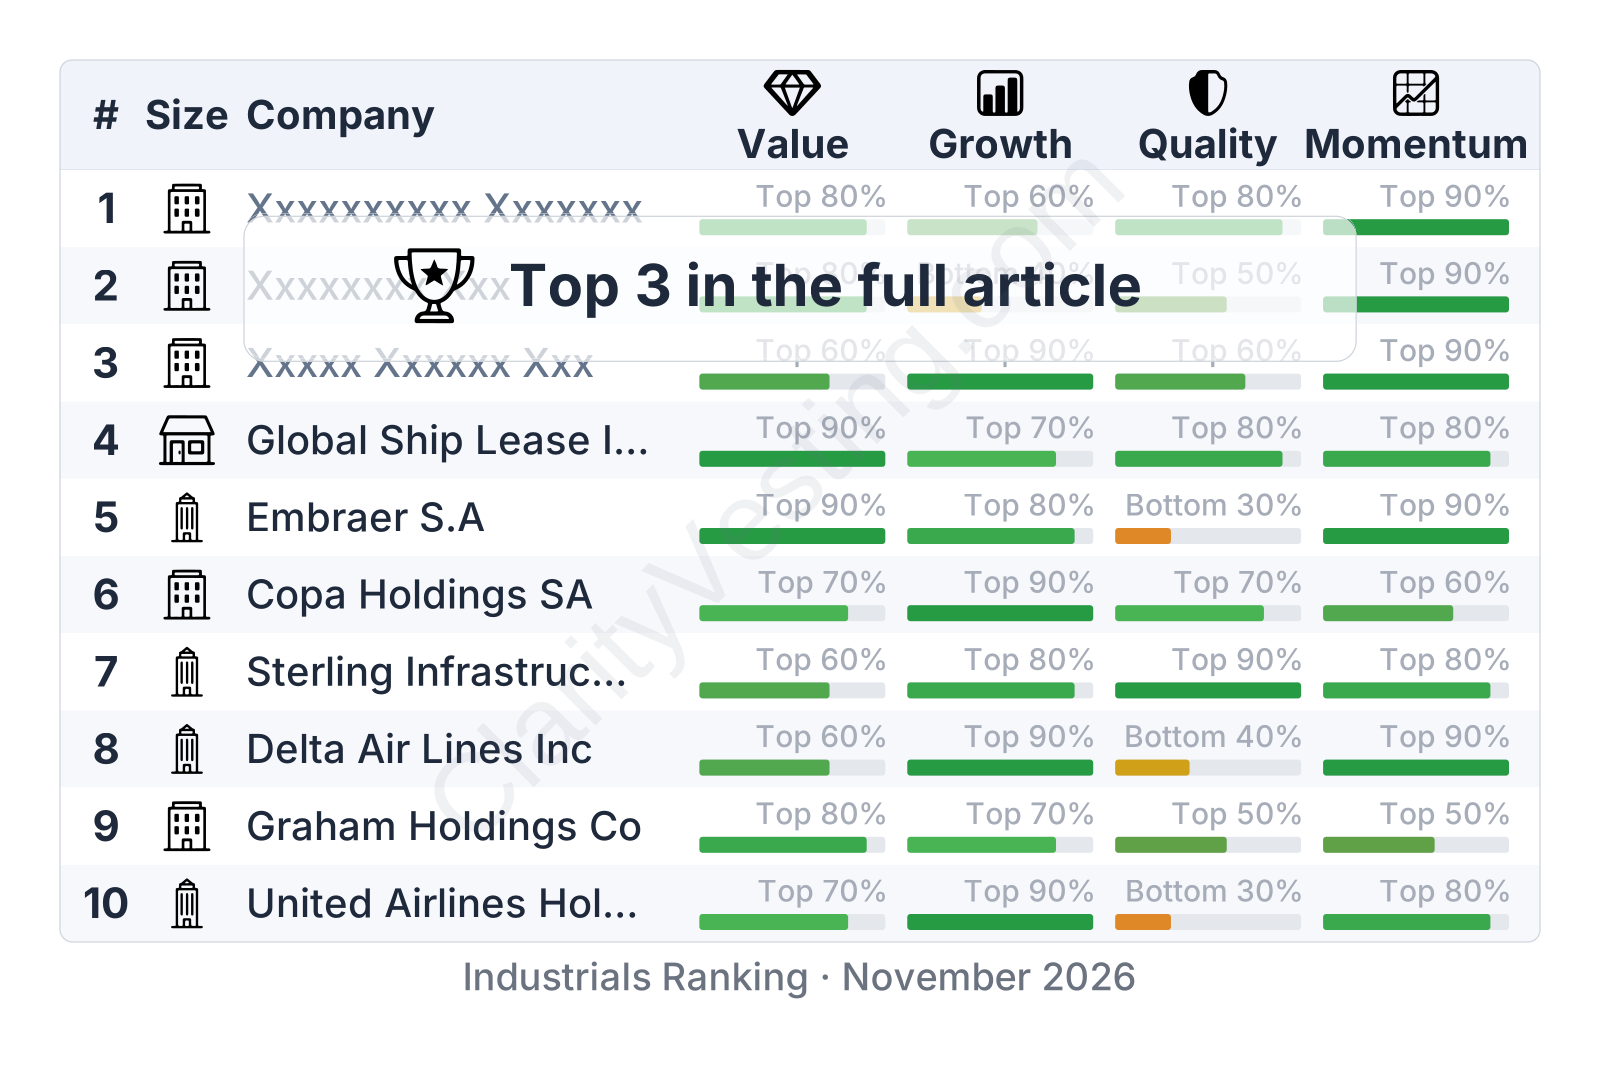
This sector ranking is based on quantitative metrics grouped into four factors:
Value: measures how expensive a stock is relative to the company’s fundamentals
Growth: measures how quickly the business is expanding
Quality: assesses business durability, with a focus on debt levels, margins, and return on invested capital
Momentum: analyzes the current direction and strength of the stock price trend
Companies with strong fundamentals have historically delivered superior long-term performance. However, quantitative metrics alone are not sufficient to evaluate a business. Understanding how a company operates, along with its catalysts and risks, provides a more complete picture.
Quantitative rankings should be used as a starting point for research rather than as standalone investment decisions.
The ranking includes companies across different market capitalizations. Smaller-cap stocks may offer stronger growth opportunities but generally carry higher volatility and business risk.
Comfort Systems USA builds and services critical mechanical and electrical systems for complex facilities. Fast growth, rising margins, strong cash generation, and low debt have established it as one of the more notable operators tied to data centers and U.S. industrial expansion.
ZIM moves container cargo across major global trade routes with a flexible, asset-light model. Its case centers on strong cash generation, route agility, and upside from firmer freight markets, while the analysis also highlights the unusually high cyclicality tied to that potential.
Sinotruk Hong Kong is a major heavy-truck manufacturer with rising exports, a strong recent earnings recovery, and a notably low-leverage balance sheet. Even so, the shares continue to trade on restrained multiples, putting more focus on its industrial scale and cash generation.
Hafnia is one of the world’s largest product tanker operators, moving refined fuels across global trade routes. Strong margins, healthy cash generation, and lower leverage are notable, while scale and fleet optimization give it meaningful weight in a cyclical shipping market.
SkyWest runs regional flights for major U.S. airlines under contract, a model that has recently produced stronger margins, rising cash flow, and a sharper earnings recovery. Its importance to essential regional networks gives the company a distinct place in the airline landscape.
CITIC Limited combines banking, special steel, iron ore, and infrastructure exposure inside one of China’s largest conglomerates. An exceptionally low valuation, a strategic asset base, and improving market momentum make it a business that merits deeper examination.
EMCOR Group installs and maintains the electrical and mechanical systems that keep complex buildings running. Strong exposure to data centers, electrification, and high-value service work has lifted growth, margins, cash flow, and overall business quality.
Argan is a specialized builder of large power and industrial projects, with recent results showing rapid growth, rising margins, strong cash flow, and very low debt. Its niche in U.S. power construction gives the business a long-term profile that stands out.
IES Holdings builds electrical and communications systems for data centers, housing, and industrial projects. In recent years, rapid revenue growth, much stronger margins, excellent returns on capital, and very low debt have made its operating profile difficult to overlook.
Mueller Industries makes essential plumbing, HVAC, and industrial components with unusually high margins, strong cash generation, and minimal debt. Recent sales momentum and balance-sheet flexibility reinforce the strength of its long-term industrial profile.
United Airlines combines one of the largest global route networks with growing premium and loyalty revenue streams. Revenue and earnings have recovered strongly, while the valuation remains restrained relative to broader industrial peers, adding nuance to the overall picture.
Graham Holdings is a diversified holding company spanning Kaplan education, health care, broadcasting, automotive, and other operations. Strong cash generation, modest leverage, and a low earnings multiple give its long-term profile added relevance.
Delta Air Lines combines a vast flight network with premium cabins and a powerful loyalty partnership model. Revenue growth, rising free cash flow, and much better leverage make the company more durable than a typical airline, giving its long-term profile added weight.
Sterling Infrastructure is a specialized U.S. builder with rising exposure to data centers, industrial sites, and transportation work. Expanding margins, strong cash generation, and a far healthier balance sheet have made it one of the more impressive operators in its space.
Copa Holdings operates a hub-based airline network across the Americas from Panama. Its strength lies in solid margins, disciplined growth, improving traffic momentum, and a balance sheet that now appears much stronger than those of many airline peers.
Embraer builds regional jets, business aircraft, defense platforms, and aviation services. Revenue, cash flow, and profitability have improved sharply, while niche leadership in regional aviation and the KC-390 program keeps the long-term outlook worth a closer look.
Global Ship Lease owns containerships and leases them under fixed-rate contracts. Strong margins, heavy cash generation, and a significantly improved balance sheet set it apart, though the next phase depends on how effectively it sustains earnings as charter markets normalize.