Stock Analysis · Sinotruk Hong Kong Ltd (SHKLY)
Overview
Sinotruk Hong Kong Ltd is a Chinese commercial vehicle manufacturer focused mainly on heavy-duty trucks. The group is best known for selling tractors, dump trucks, cargo trucks, specialized trucks, and related components. Its products are used in freight transport, construction, mining, logistics, and infrastructure work. The company also has operations tied to engines, axles, transmissions, and other parts, which matter because they support both vehicle sales and the broader manufacturing ecosystem around its truck platforms.
The business is closely linked to commercial transport demand in China and, increasingly, export markets. In simple terms, when freight activity, construction, and infrastructure spending are strong, demand for heavy trucks and related equipment usually improves as well. Sinotruk’s position is especially important in heavy-duty trucks, where scale, manufacturing efficiency, dealer networks, and product reliability can create meaningful advantages.
Based on company disclosures and the structure of the business, revenue is primarily driven by vehicle sales, with smaller contributions from parts, components, and service-related activities. Approximate revenue sources can be described as follows:
- Heavy-duty trucks and other commercial vehicles: approximately 75% to 85% of revenue. This includes complete vehicles such as tractor trucks, dump trucks, cargo trucks, and specialized commercial vehicles.
- Components and parts: approximately 15% to 25% of revenue. This generally includes engines, gearboxes, axles, cabins, and other truck-related systems sold internally or externally.
- Other activities: a small share of revenue. This may include service-related items and other supporting operations, but these appear materially smaller than vehicle and component sales.
The company’s income flow over recent years shows a cyclical business that recovered strongly after a weak 2022. Revenue moved back above prior levels by 2025, while net income rose more steadily than operating income, suggesting improving scale and better recovery after the downcycle rather than a straight-line expansion.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Farm & Heavy Construction Machinery | |
| Market Cap ⓘ | $12.15B | |
| Beta ⓘ | 1.29 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 10.80 | 22.29 |
| P/B Ratio ⓘ | 0.24 | 1.98 |
| FCF Yield ⓘ | 133.63% | 6.26% |
| Dividend Yield ⓘ | 5.93% | 1.92% |
| EBIT / EV ⓘ | N/A | 4.83% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 39.20% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 3.46% | 7.76% |
| EPS Growth (5Y CAGR) ⓘ | 38.68% | -13.17% |
| BVPS Growth (5Y CAGR) ⓘ | 0.88% | 6.13% |
| Margin Growth (5Y Trend) ⓘ | 0.98% | 0.74% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 10.79% |
| DPS Growth (5Y CAGR) ⓘ | 8.06% | 9.41% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 10.75% |
| ROA (Latest) ⓘ | 9.36% | 5.41% |
| ROIC (5Y Median) ⓘ | 12.60% | 9.37% |
| ROA (5Y Median) ⓘ | 4.66% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | -1.81 | 2.04 |
| Net Debt / EBIT (5Y Median) ⓘ | -1.48 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | -1.49 | 1.39 |
| Net Debt / Assets ⓘ | -18.07% | 19.27% |
| EBITDA / Interest ⓘ | N/A | 9.58 |
| Operating Margin (Latest) ⓘ | 7.33% | 10.49% |
| Operating Margin (5Y Median) ⓘ | 6.62% | 10.30% |
| Debt to Equity (Latest) ⓘ | 10.05% | 64.82% |
| Profit Margin (Latest) ⓘ | 6.11% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $16.23B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +168.95% | +67.77% |
| 12M Return (excl. last month) ⓘ | +79.08% | +12.05% |
| 6M Return ⓘ | +58.03% | 0.00% |
| Price vs. 200-Day MA ⓘ | +72.99% | +0.67% |
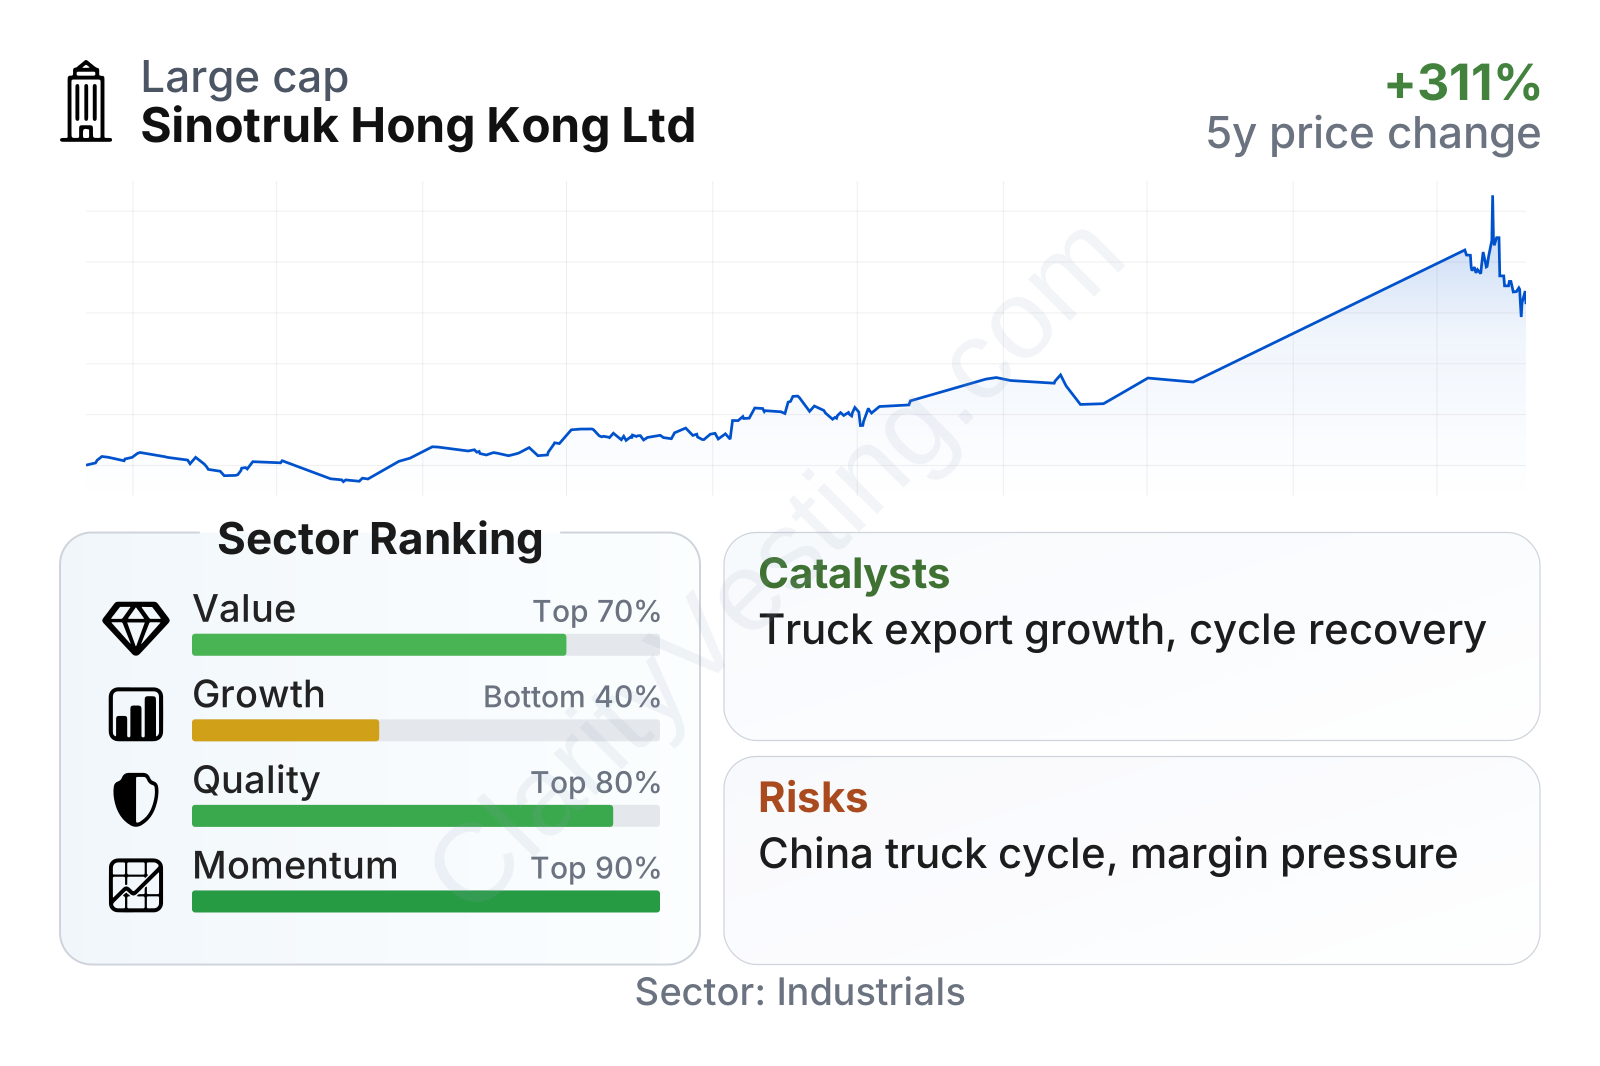
Sinotruk currently stands out for a combination of low valuation multiples, high cash generation, and a strong balance sheet. Relative to the broader industrial machinery universe, its value and quality profile looks notably strong, while momentum has also been unusually powerful. The weaker area is long-term top-line compounding, which helps explain why the shares still trade at lower multiples than many sector peers despite recent strong performance.
The stock’s longer-term price move has been very strong, far ahead of the sector median over one-, three-, and six-month periods. At the same time, the company remains in a large-cap range by industry standards, and its beta suggests the shares can be more volatile than the overall market.
Growth
Sinotruk operates in a sector that should remain relevant for years because trucks are essential to logistics, manufacturing, construction, and infrastructure. That said, this is not a smooth growth market. Heavy truck demand tends to move in cycles, especially in China, where replacement demand, freight activity, industrial output, emissions rules, and public works spending can all sharply affect order volumes.
The company’s recent operating direction looks constructive. Revenue and earnings recovered strongly after the 2022 downturn, and by 2025 annual revenue had climbed to a new high, while net income also exceeded prior peaks. That pattern matters because it suggests Sinotruk is not merely surviving the cycle but regaining volume and preserving profitability at a relatively solid level.
One of the clearest growth supports is exports. Chinese truck manufacturers have been expanding outside their home market, especially into developing regions where price competitiveness, improving product quality, and established industrial ties matter. Sinotruk has brand recognition in heavy-duty trucks and benefits from being part of a larger state-linked industrial ecosystem, which can help with production scale, supply chain coordination, and overseas market reach.
Another growth driver is product upgrading. As fleets gradually shift toward better fuel efficiency, stricter emissions compliance, smarter fleet management, and in some cases alternative-energy commercial vehicles, established truck makers have a chance to capture replacement demand. Sinotruk’s continued spending on research and development indicates that management is trying to stay competitive as truck technology becomes more advanced.
A further catalyst is the broader recovery in commercial activity and infrastructure-related demand. If freight utilization remains healthy and replacement demand continues, the company could benefit from both domestic deliveries and exports. Recent financial performance already points to this recovery dynamic, with year-over-year revenue growth far above the sector median, even if the five-year revenue trend remains less impressive because of the deep industry downturn earlier in the period.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


