Stock Analysis · EMCOR Group Inc (EME)
Overview
EMCOR Group is a specialty construction and facility services company. In simple terms, it helps customers design, install, operate, and maintain the systems that make buildings and industrial sites work: electrical networks, heating and cooling, plumbing, fire protection, controls, and ongoing maintenance. Its customers include commercial buildings, hospitals, data centers, manufacturers, utilities, transportation facilities, and public-sector clients.
The business is built around technical services that are essential rather than optional. A hospital, semiconductor facility, airport, or data center cannot operate without reliable electrical, mechanical, and maintenance support. That gives EMCOR exposure to both new construction and recurring service work.
Based on the company’s segment reporting and recent filings, revenue is primarily generated from the following activities:
- U.S. electrical construction and services: approximately 39% of revenue. This includes electrical installation, power systems, network and communications work, lighting, instrumentation, and services for complex facilities.
- U.S. mechanical construction and facilities services: approximately 34% of revenue. This covers HVAC, plumbing, process piping, refrigeration, building controls, and long-term maintenance or retrofit work.
- U.S. building services: approximately 17% of revenue. This is more recurring in nature and includes operations, maintenance, repairs, upgrades, and support for existing facilities.
- U.S. industrial services: approximately 8% of revenue. This area serves manufacturing and industrial customers with shutdown, turnaround, field, and support services.
- U.K. building services: approximately 2% of revenue. This is a much smaller contribution than the U.S. operations.
One important point for long-term analysis is that EMCOR is not a pure commodity contractor chasing low-margin work everywhere. It has increasingly focused on technically demanding projects and service contracts where reliability, execution, and customer relationships matter more than lowest price alone.
The company’s financial flow has also improved meaningfully over the last several years. Revenue has expanded strongly, but what stands out even more is that operating income and net income have risen faster than sales, which usually signals better project mix, stronger execution, or both.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Engineering & Construction | |
| Market Cap ⓘ | $30.99B | |
| Beta ⓘ | 1.12 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 21.87 | 22.29 |
| P/B Ratio ⓘ | 7.64 | 1.98 |
| FCF Yield ⓘ | 3.78% | 6.26% |
| Dividend Yield ⓘ | 0.09% | 1.92% |
| EBIT / EV ⓘ | 6.24% | 4.83% |
| PEG ⓘ | 0.31 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 19.80% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 19.94% | 7.76% |
| EPS Growth (5Y CAGR) ⓘ | 19.44% | -13.17% |
| BVPS Growth (5Y CAGR) ⓘ | 18.44% | 6.13% |
| Margin Growth (5Y Trend) ⓘ | 3.88% | 0.74% |
| FCF Growth (5Y CAGR) ⓘ | 43.23% | 10.79% |
| DPS Growth (5Y CAGR) ⓘ | 17.84% | 9.41% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 38.47% | 10.75% |
| ROA (Latest) ⓘ | 15.28% | 5.41% |
| ROIC (5Y Median) ⓘ | 27.54% | 9.37% |
| ROA (5Y Median) ⓘ | 10.43% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | -0.19 | 2.04 |
| Net Debt / EBIT (5Y Median) ⓘ | -0.50 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | -0.17 | 1.39 |
| Net Debt / Assets ⓘ | -3.77% | 19.27% |
| EBITDA / Interest ⓘ | N/A | 9.58 |
| Operating Margin (Latest) ⓘ | 10.99% | 10.49% |
| Operating Margin (5Y Median) ⓘ | 7.07% | 10.30% |
| Debt to Equity (Latest) ⓘ | 13.29% | 64.82% |
| Profit Margin (Latest) ⓘ | 7.74% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $1.17B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +265.65% | +67.77% |
| 12M Return (excl. last month) ⓘ | +20.12% | +12.05% |
| 6M Return ⓘ | -16.48% | 0.00% |
| Price vs. 200-Day MA ⓘ | -10.43% | +0.67% |
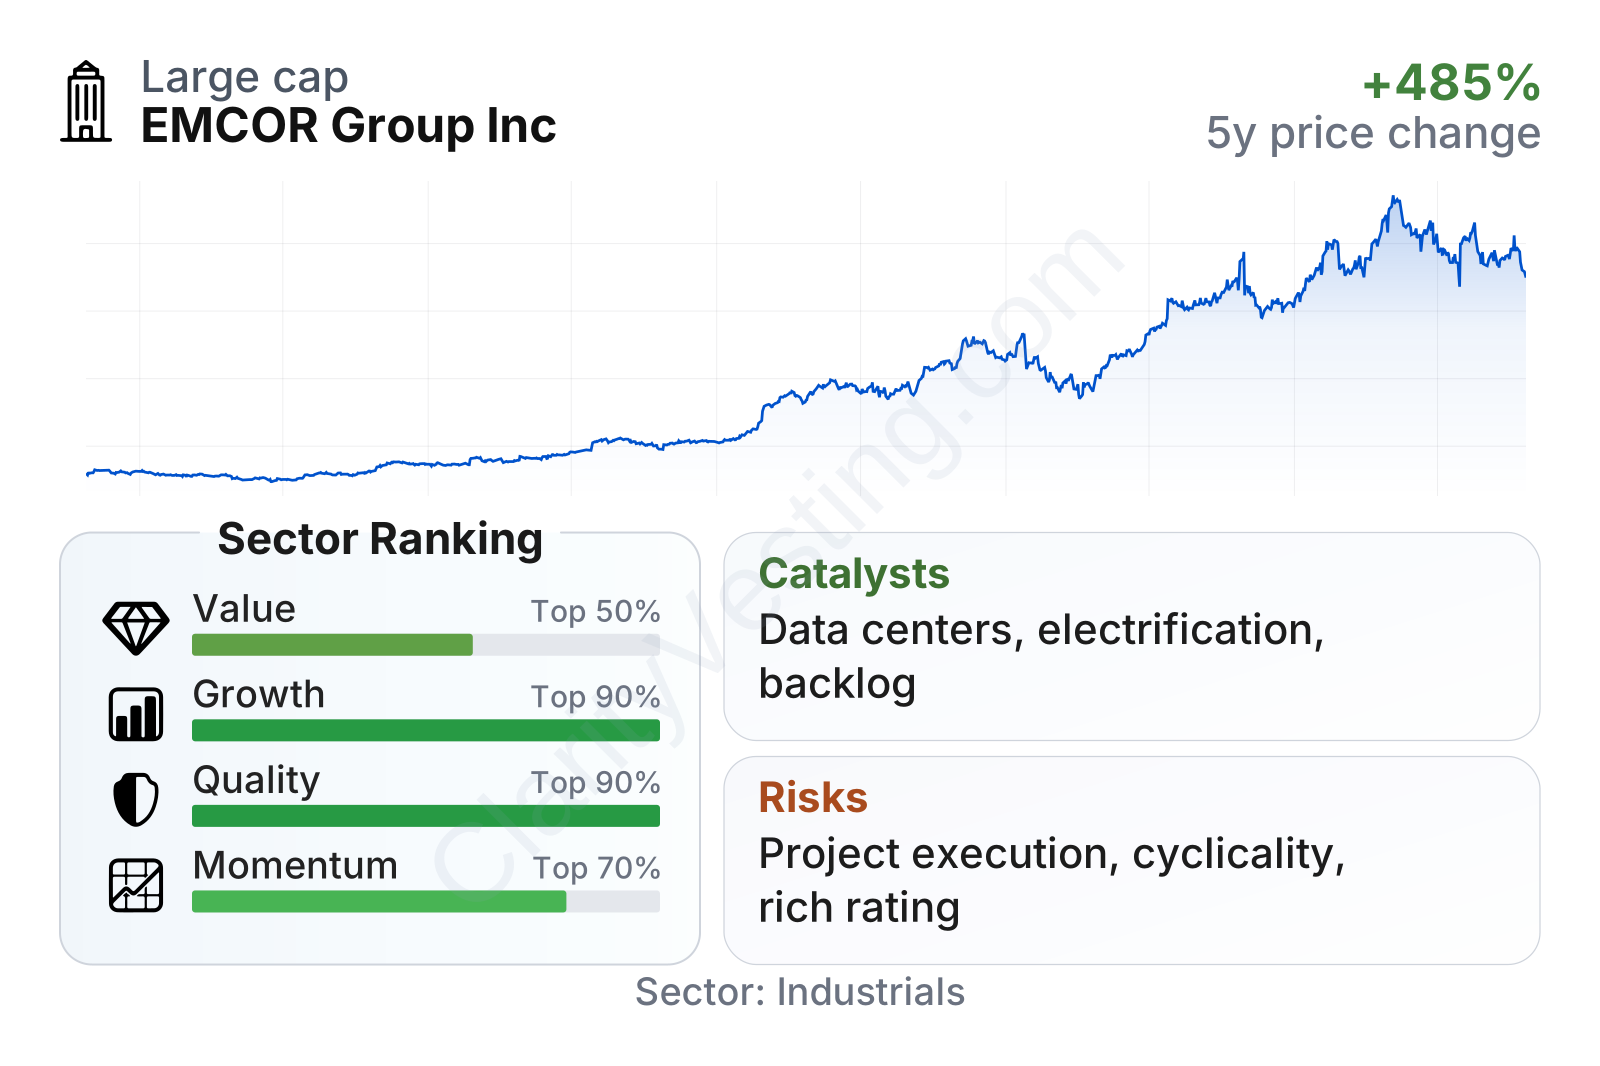
EMCOR is now a large industrial company with above-average share price volatility for the broad market, but not unusually high for construction-related businesses. The most notable feature in the current metrics is balance: growth and quality rank very strongly against the sector, while valuation looks closer to average. Profitability has improved a lot over time, leverage remains low, and cash generation is solid, although the cash flow yield is not especially high after the stock’s major run-up.
The stock chart shows how dramatically the market’s view has changed. EMCOR moved from being treated like a fairly typical contractor a few years ago to being valued more like a high-performing execution-driven industrial business. That re-rating explains why the stock has appreciated much faster than revenue alone.
Growth
EMCOR operates in a part of the market that benefits from several long-duration demand drivers. Building systems are becoming more complex, power needs are rising, aging infrastructure needs upgrades, and mission-critical facilities require constant service. Data centers, health care facilities, high-tech manufacturing, energy-related projects, and retrofit work all support demand for the kind of mechanical and electrical work EMCOR performs.
A major reason the company’s sector outlook is favorable is electrification. Buildings and industrial sites need more power distribution, backup systems, controls, cooling, and efficiency upgrades than in the past. Data center expansion is especially relevant because these facilities require dense electrical and mechanical installations, precision cooling, and long-term maintenance support. Those are exactly the categories where EMCOR has established capabilities.
Its strategy also makes sense for future growth. Management has emphasized higher-value projects, disciplined bidding, selective acquisitions, and service-oriented work that can complement construction revenue. That approach can produce a healthier business than simply maximizing volume, because it aims for better margins and steadier customer relationships.
Recent growth has been unusually strong for an engineering and construction company. Year-over-year revenue growth has stayed near the high-teens to around 20% recently, clearly ahead of the broader sector median. Just as important, this is not only a sales story: over five years, earnings per share, revenue per share, and free cash flow have all compounded at rates well above typical sector levels.
Cash generation remains an important positive feature. Free cash flow climbed sharply over the last few years and remains above the levels seen earlier in the cycle, even with some normal fluctuation. For a project-based business, that matters because accounting profits can sometimes look strong while cash conversion disappoints. EMCOR’s record has been much better than that concern would suggest.
Recent company communications have also pointed to strong project demand and healthy remaining performance obligations, especially in areas tied to network infrastructure, data centers, manufacturing, and other technically complex end markets. In practical terms, that means a meaningful pipeline of awarded work still to be completed, which supports revenue visibility more than in a typical short-cycle contractor.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


