Stock Analysis · Zurn Elkay Water Solutions Corporation (ZWS)
Overview
Zurn Elkay Water Solutions Corporation is a water infrastructure company focused on products that move, control, protect, and improve water in commercial, institutional, and industrial buildings. Its portfolio includes plumbing fixtures, water safety systems, drainage products, drinking water solutions, and sensor-based devices used in places such as schools, hospitals, offices, airports, and public facilities. The company’s business is tied less to discretionary consumer spending and more to building standards, water efficiency needs, health regulations, and long-lived infrastructure replacement cycles.
Following the combination of Zurn and Elkay’s drinking water business, the company has become broader and more balanced across water management categories. Its product lineup now spans both “behind-the-wall” components, such as valves and drainage systems, and “in-front-of-the-wall” products, such as bottle filling stations, drinking fountains, and flush valves. That mix matters because it gives ZWS exposure to new construction, renovation, retrofit, and recurring replacement demand.
Based on recent company reporting, revenue is primarily generated from water management and water delivery products sold into nonresidential end markets. A simple way to think about the business is the following:
- Water control and safety products: approximately 35% to 45% of revenue. This includes backflow prevention, pressure control, shut-off systems, fire protection-related water control components, and connected water management solutions.
- Drainage and finish plumbing products: approximately 25% to 35% of revenue. This includes floor drains, trench drainage, interceptors, flush valves, faucets, carriers, and related specification plumbing products.
- Drinking water solutions: approximately 25% to 35% of revenue. This includes bottle filling stations, water coolers, drinking fountains, filtration, and hydration systems, largely associated with the Elkay portfolio.
- Other accessory and aftermarket sales: a smaller share. This includes replacement parts, filters, and complementary items that support installed products over time.
The company’s customer base is also diversified. It sells through distributors, wholesalers, plumbing representatives, contractors, and specification channels, with demand coming from education, healthcare, government, commercial buildings, and industrial sites. Financially, the business has shown a favorable shift over the last several years: revenue has expanded meaningfully, operating income has improved, interest burden has eased, and net income has climbed faster than sales, pointing to better efficiency and integration benefits.
The financial flow over recent years suggests a business that has not only grown sales, but also converted a larger share of those sales into operating profit and net income. Gross profit has risen materially since 2021, while interest expense has trended lower relative to revenue, supporting stronger earnings quality.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Pollution & Treatment Controls | |
| Market Cap ⓘ | $7.91B | |
| Beta ⓘ | 0.83 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 29.63 | 22.29 |
| P/B Ratio ⓘ | 4.94 | 1.98 |
| FCF Yield ⓘ | 4.74% | 6.26% |
| Dividend Yield ⓘ | 0.89% | 1.92% |
| EBIT / EV ⓘ | 3.90% | 4.83% |
| PEG ⓘ | 1.52 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 10.50% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 7.99% | 7.76% |
| EPS Growth (5Y CAGR) ⓘ | -1.96% | -13.17% |
| BVPS Growth (5Y CAGR) ⓘ | 74.47% | 6.13% |
| Margin Growth (5Y Trend) ⓘ | 7.24% | 0.74% |
| FCF Growth (5Y CAGR) ⓘ | 12.13% | 10.79% |
| DPS Growth (5Y CAGR) ⓘ | 6.42% | 9.41% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 11.20% | 10.75% |
| ROA (Latest) ⓘ | 10.10% | 5.41% |
| ROIC (5Y Median) ⓘ | 6.22% | 9.37% |
| ROA (5Y Median) ⓘ | 5.40% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | 0.60 | 2.04 |
| Net Debt / EBIT (5Y Median) ⓘ | 2.19 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 0.47 | 1.39 |
| Net Debt / Assets ⓘ | 6.67% | 19.27% |
| EBITDA / Interest ⓘ | 15.30 | 9.58 |
| Operating Margin (Latest) ⓘ | 17.84% | 10.49% |
| Operating Margin (5Y Median) ⓘ | 12.11% | 10.30% |
| Debt to Equity (Latest) ⓘ | 33.18% | 64.82% |
| Profit Margin (Latest) ⓘ | 15.45% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $375.10M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +94.56% | +67.77% |
| 12M Return (excl. last month) ⓘ | -0.58% | +12.05% |
| 6M Return ⓘ | +1.38% | 0.00% |
| Price vs. 200-Day MA ⓘ | +0.53% | +0.67% |
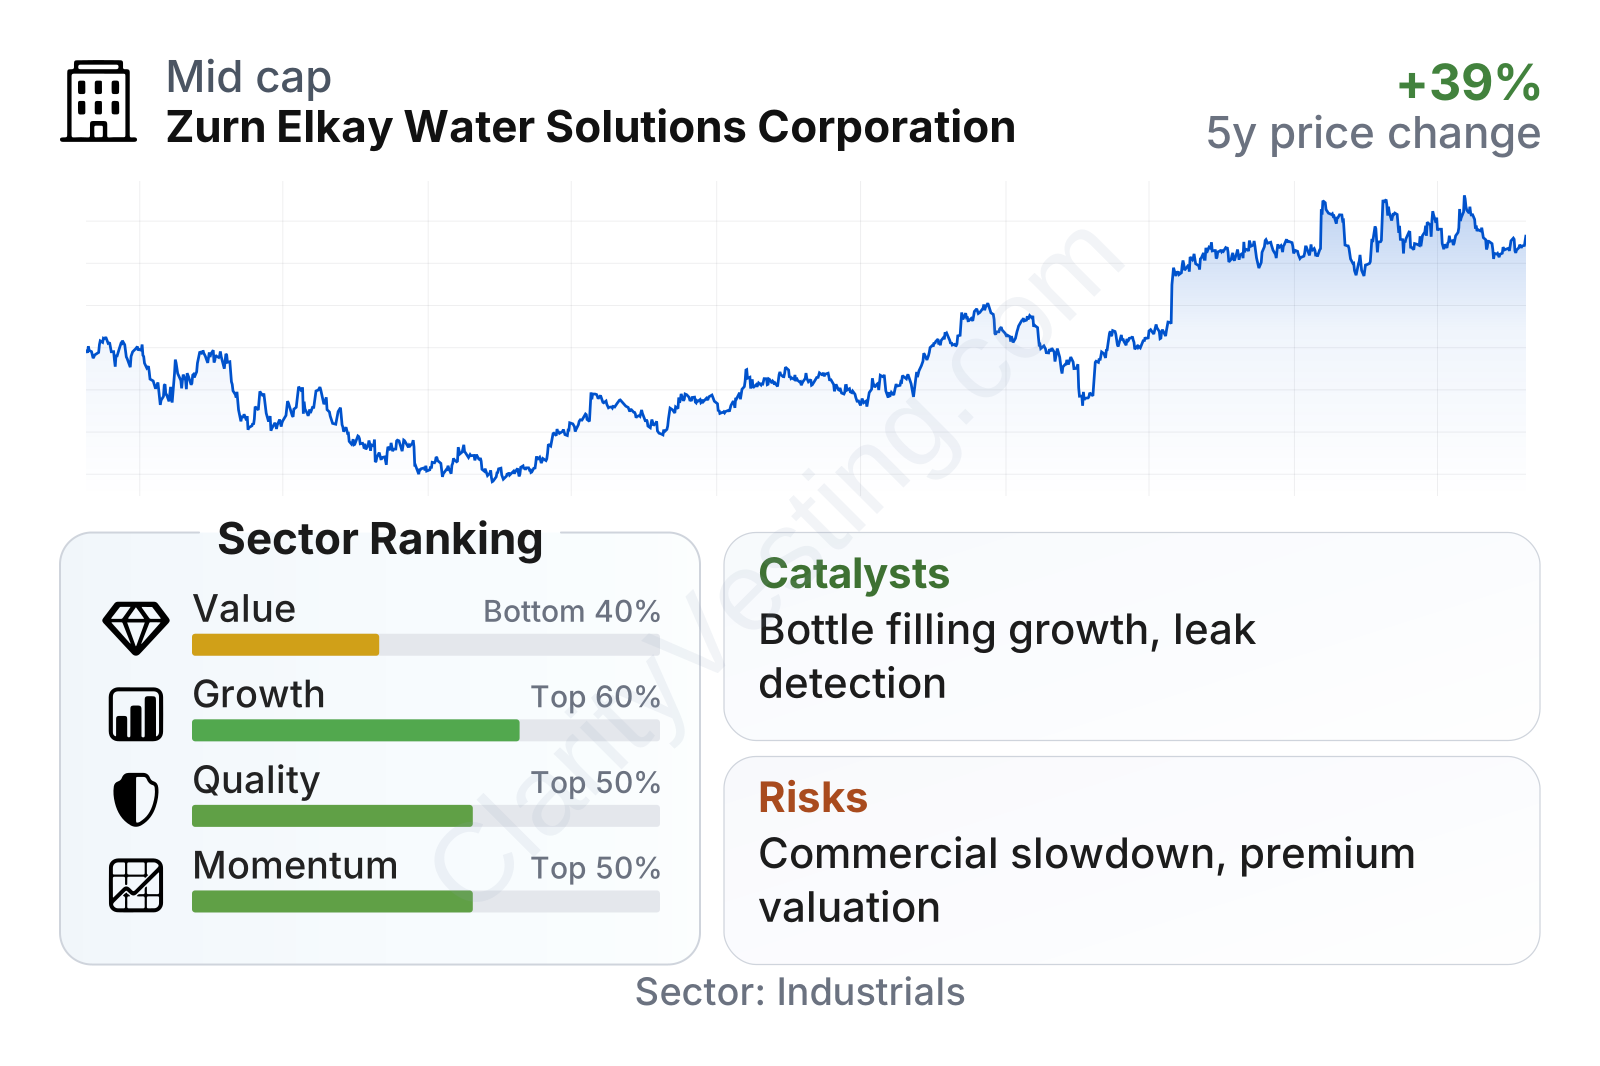
ZWS is a mid-sized industrial company with a market value in the multi-billion-dollar range and a below-market beta, which suggests its share price has tended to swing less than the broader market. The latest factor profile is mixed but understandable: valuation metrics sit below the sector on attractiveness, quality is solid, growth is somewhat above average, and recent share-price momentum is not especially strong. In plain language, the business fundamentals look healthier than the stock’s recent pace would suggest, but the market is still assigning a premium to those fundamentals.
Growth
ZWS operates in a sector with durable long-term support. Water infrastructure, building safety, lead reduction, water conservation, and touchless public hygiene are not short-lived themes. In the United States especially, a meaningful portion of commercial and institutional plumbing infrastructure is old and requires replacement or modernization. That creates demand not only when new buildings are constructed, but also when existing facilities are upgraded to meet code, efficiency, and health requirements.
The company’s strategy appears aligned with these trends. Management has emphasized specification-driven products, recurring replacement demand, productivity gains, and bolt-on acquisitions that expand the portfolio. The Elkay transaction was particularly important because it strengthened ZWS in drinking water access and hydration systems, making the company more relevant in schools, airports, offices, and healthcare buildings where bottle filling stations and filtered hydration products have become standard. The company has also been building a connected water management offering, which can help detect leaks, monitor usage, and improve building efficiency.
Revenue growth has normalized after the acquisition-driven jump in 2022 and 2023, but the broader trend remains positive. Through much of 2024 and 2025, growth stayed in positive territory and accelerated at points into the high single digits and low double digits before a softer most recent quarter. That pattern looks more like normal project timing and comparison effects than a broken growth profile.
Cash generation has also moved in the right direction. Free cash flow has risen strongly from early post-merger levels and remains substantial, which is important because it gives the company flexibility to reduce debt, invest in operations, pursue acquisitions, and continue shareholder returns without depending heavily on outside capital.
Several catalysts stand out. Public facilities continue to adopt filtered bottle filling stations and touchless fixtures. Water safety regulation and leak prevention are supporting demand for monitoring and control products. Nonresidential retrofit activity can remain resilient even when new construction slows, because schools, hospitals, and public buildings still need maintenance and compliance upgrades. Recent company communications have also pointed to ongoing productivity initiatives and portfolio optimization, which could help margins even if revenue growth becomes more moderate.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


