Stock Analysis · Zoetis Inc (ZTS)
Overview
Zoetis is a global animal health company. It develops, manufactures, and sells medicines, vaccines, diagnostic products, and other technologies used to prevent, detect, and treat illnesses in animals. Its customers include veterinarians, livestock producers, and pet owners through veterinary channels. In simple terms, Zoetis sits at the intersection of pharmaceuticals and animal care, serving both household pets and farm animals.
The business is mainly powered by companion animals, especially products for dogs and cats, while livestock remains an important but smaller contributor. Based on recent company reporting, revenue is broadly distributed as follows:
- Companion animal products: about 68% of revenue. This includes parasiticides, dermatology treatments, pain products, vaccines, diagnostics, and other medicines for dogs, cats, and horses used mainly in veterinary clinics.
- Livestock products: about 32% of revenue. This includes vaccines, anti-infectives, parasiticides, medicated feed additives, and other products for cattle, swine, poultry, fish, and sheep.
- By geography, the business is also split between the United States and international markets, with the U.S. representing the larger share and international operations contributing a little over 40% in recent years. That international base matters because it reduces reliance on one single market.
Within its portfolio, some of Zoetis’ most important growth franchises have come from companion animal treatments such as Simparica, Apoquel, Cytopoint, Librela, Solensia, and diagnostics. This mix is important because companion animal care tends to be more resilient and often carries attractive margins, while livestock demand can be more cyclical and exposed to farm economics.
The financial flow over the last several years shows a business that has steadily expanded revenue, gross profit, operating income, and net income. Research and development spending has also increased, which supports future product launches, while selling and administrative costs have risen more slowly than revenue overall, helping preserve strong profitability.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Drug Manufacturers - Specialty & Generic | |
| Market Cap ⓘ | $32.90B | |
| Beta ⓘ | 0.74 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 13.10 | 25.42 |
| P/B Ratio ⓘ | 10.88 | 3.08 |
| FCF Yield ⓘ | 7.19% | 3.12% |
| Dividend Yield ⓘ | 2.57% | 1.85% |
| EBIT / EV ⓘ | 9.45% | 0.56% |
| PEG ⓘ | 6.66 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -0.20% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | 6.94% | 8.60% |
| EPS Growth (5Y CAGR) ⓘ | -9.19% | -17.73% |
| BVPS Growth (5Y CAGR) ⓘ | -5.79% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | 2.81% | -0.57% |
| FCF Growth (5Y CAGR) ⓘ | 7.09% | 0.96% |
| DPS Growth (5Y CAGR) ⓘ | 19.14% | 6.69% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 22.76% | 3.17% |
| ROA (Latest) ⓘ | 17.30% | 2.98% |
| ROIC (5Y Median) ⓘ | 21.33% | 4.56% |
| ROA (5Y Median) ⓘ | 16.05% | 1.87% |
| Net Debt / EBIT (Latest) ⓘ | 2.21 | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.48 | 1.86 |
| Net Debt / EBITDA (Latest) ⓘ | 1.94 | 1.00 |
| Net Debt / Assets ⓘ | 51.48% | 5.06% |
| EBITDA / Interest ⓘ | 16.36 | 9.55 |
| Operating Margin (Latest) ⓘ | 36.88% | 9.25% |
| Operating Margin (5Y Median) ⓘ | 36.46% | 7.33% |
| Debt to Equity (Latest) ⓘ | 293.46% | 26.68% |
| Profit Margin (Latest) ⓘ | 27.69% | 3.34% |
| Free Cash Flow (Latest) ⓘ | $2.37B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -48.69% | +51.61% |
| 12M Return (excl. last month) ⓘ | -48.66% | +19.90% |
| 6M Return ⓘ | -29.74% | +10.10% |
| Price vs. 200-Day MA ⓘ | -12.98% | +6.44% |
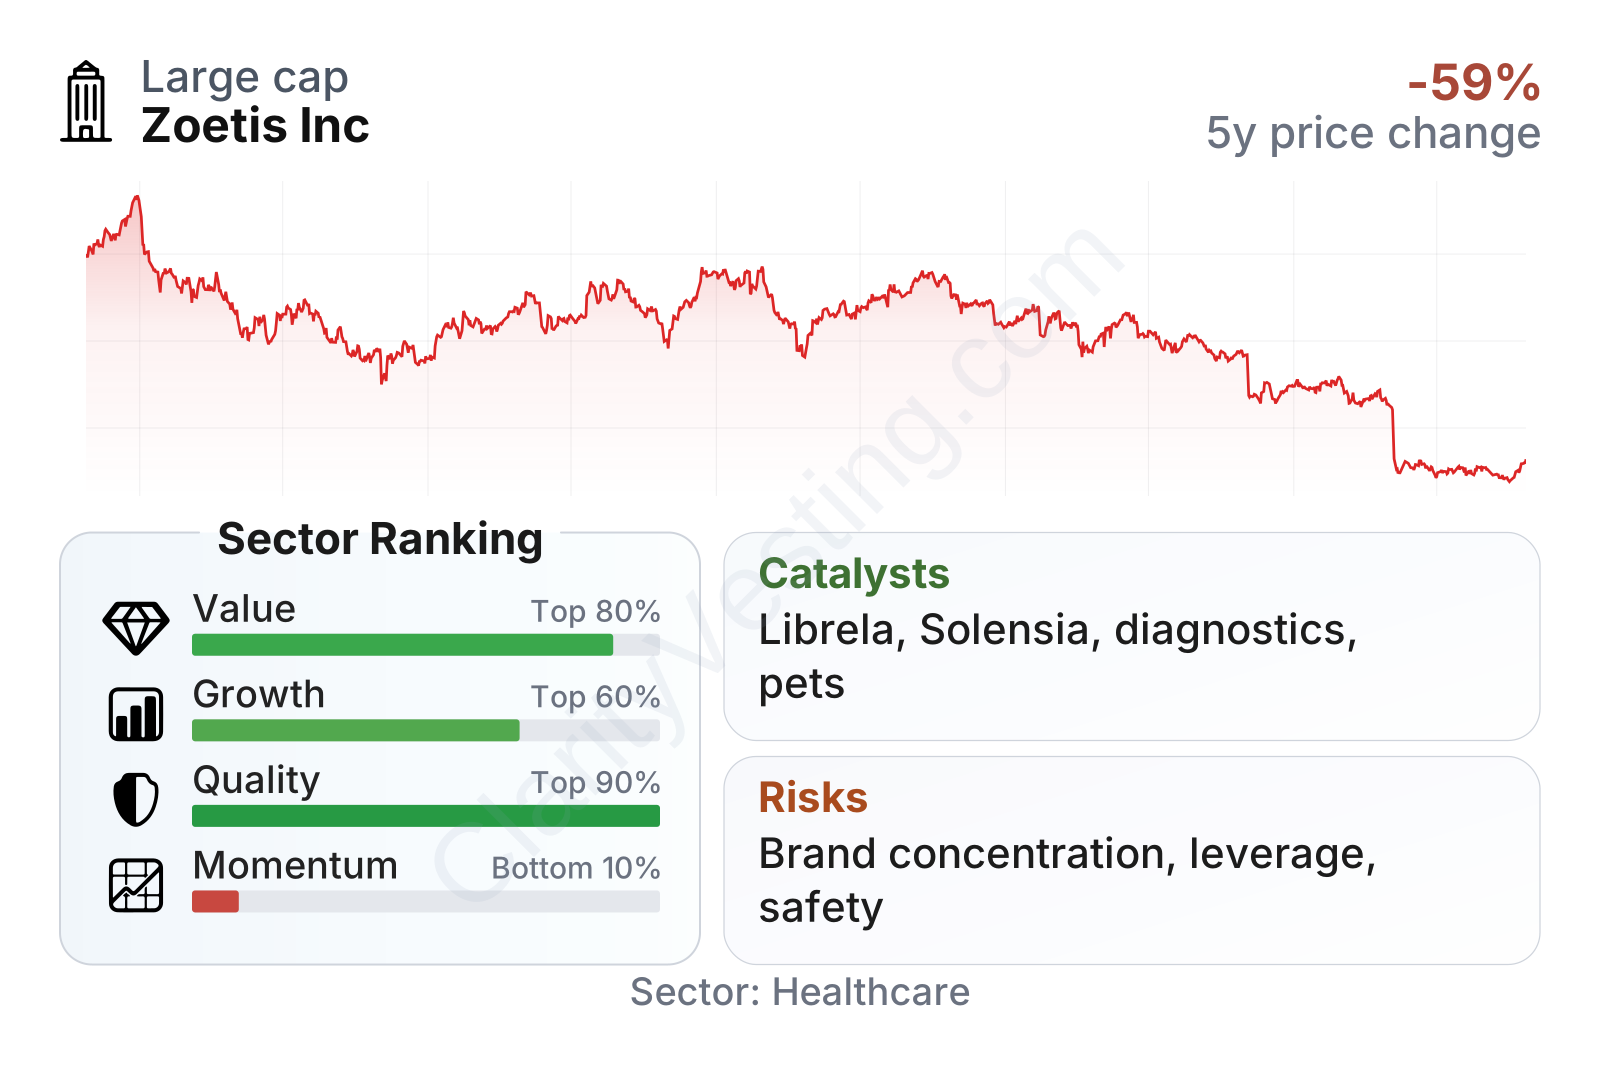
Zoetis is a large healthcare company with a relatively low stock volatility profile, as reflected by a beta below 1. On profitability and capital efficiency, it stands out strongly versus much of the healthcare sector. Returns on assets are far above sector norms, free cash flow generation is solid, and margins remain unusually high for a manufacturer. The weaker area is recent stock performance, which has been much softer than the broader sector. Growth is positive over multi-year periods, but the latest year-over-year revenue comparison has cooled meaningfully, which helps explain the market’s more cautious view.
Growth
Animal health is generally considered an attractive long-term market. Pet ownership has increased structurally in many countries, veterinary care has become more sophisticated, and pet owners are often willing to spend more on chronic conditions, pain management, dermatology, and parasite protection. On the livestock side, the need to improve animal productivity and disease prevention remains important, although that part of the market usually grows more slowly and can be more cyclical.
Zoetis’ strategy fits well with those long-term trends. The company has built a broad portfolio across medicines, vaccines, and diagnostics, and it benefits from a large installed customer base among veterinarians. That matters because diagnostics can help reinforce product sales: once a veterinary clinic uses a company’s testing platform and care pathway, additional treatments and follow-up products can become easier to place.
A key growth driver has been innovation in companion animal medicine. Zoetis has been expanding in areas where pet owners and veterinarians increasingly seek premium solutions, especially osteoarthritis pain, allergy and itch treatments, and parasite control. Products such as Librela for dogs and Solensia for cats address chronic pain management, a category with room for broader adoption if clinical experience remains favorable. The dermatology and parasiticide franchises also continue to support recurring demand.
Revenue growth has clearly slowed from the stronger pace seen in 2023 and 2024. That does not erase the broader expansion trend, but it shows that Zoetis is now moving through a more mature phase, where future upside will likely depend more on product mix, adoption of newer therapies, and execution in international markets than on easy volume gains alone.
Cash generation remains one of the more reassuring features of the business. Free cash flow has climbed meaningfully over the past several years and remains above $2 billion on a trailing basis, even after a modest pullback from the recent peak. That gives Zoetis financial flexibility to support research, acquisitions, manufacturing capacity, and shareholder distributions without changing the overall character of the business.
Recent company updates in 2026 have continued to emphasize companion animal innovation, lifecycle management of key products, and geographic expansion. The broad opportunity is not tied to a single breakthrough product alone; it is more about Zoetis continuing to deepen its role in everyday veterinary care, where recurring use and brand familiarity matter a great deal.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


