Stock Analysis · ZoomLion (ZLIOY)
Overview
Zoomlion Heavy Industry Science and Technology, traded in the U.S. over-the-counter market under the symbol ZLIOY, is a large Chinese industrial equipment manufacturer. The company designs and sells heavy machinery used mainly in construction, infrastructure, agriculture, and industrial lifting. Its product range includes concrete machinery, cranes, earthmoving equipment, aerial work platforms, mining machinery, and agricultural machines. In simple terms, Zoomlion makes the large equipment used to build roads, bridges, buildings, industrial sites, and to mechanize farming.
The business is diversified across several machinery categories, but construction-related equipment remains the core of the group. Based on company disclosures in recent annual reporting, the main revenue sources are approximately the following:
- Aerial work machinery: around 25% to 30% of revenue. This includes scissor lifts, boom lifts, and other equipment used for working at height.
- Concrete machinery: around 15% to 20%. This covers concrete pumps, mixers, and related job-site equipment.
- Cranes and lifting machinery: around 15% to 20%. This includes truck cranes, tower cranes, crawler cranes, and other lifting systems.
- Earthmoving and foundation machinery: around 10% to 15%. This includes excavators and equipment used in site preparation and ground engineering.
- Agricultural machinery: around 10% to 15%. This business includes tractors, harvesters, and other farm equipment.
- Other products and services: the remaining share. This can include parts, finance-related services, and smaller equipment categories.
Geographically, China is still the main market, but international business has become increasingly important as domestic construction cycles have remained uneven. That overseas expansion matters because it reduces dependence on one market and gives Zoomlion more ways to grow when Chinese real estate and infrastructure demand soften.
The profit profile also shows a business that went through a deep downturn in 2022 and then gradually recovered. Revenue fell sharply from 2021 levels, but operating profit and net income improved again in 2023 through 2025, helped by cost discipline and a better mix. Research and development spending remains meaningful for an equipment maker, which suggests the company is still investing in product competitiveness rather than simply cutting its way to short-term earnings.
Over the last few years, the most visible pattern has been a steep revenue contraction after the 2021 peak, followed by stabilization and a recovery in profitability. Revenue has not yet returned to the earlier high, but margins and net income have improved faster than sales, pointing to a more efficient operating base.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Nov 11, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Farm & Heavy Construction Machinery | |
| Market Cap ⓘ | $8.63B | |
| Beta ⓘ | 0.33 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 10.51 | 21.16 |
| P/B Ratio ⓘ | N/A | 3.17 |
| FCF Yield ⓘ | 3.30% | 5.03% |
| Dividend Yield ⓘ | 8.48% | 1.92% |
| EBIT / EV ⓘ | 6.32% | 6.26% |
| PEG ⓘ | 7.89 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 4.70% | 9.20% |
| RPS Growth (5Y CAGR) ⓘ | -7.06% | 7.66% |
| EPS Growth (5Y CAGR) ⓘ | 33.87% | -7.47% |
| BVPS Growth (5Y CAGR) ⓘ | -1.69% | 6.12% |
| Margin Growth (5Y Trend) ⓘ | 1.10% | 0.74% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 11.01% |
| DPS Growth (5Y CAGR) ⓘ | 4.70% | 9.31% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 4.43% | 10.37% |
| ROA (Latest) ⓘ | 2.78% | 5.41% |
| ROIC (5Y Median) ⓘ | 6.59% | 9.39% |
| ROA (5Y Median) ⓘ | 2.77% | 4.92% |
| Net Debt / EBIT (Latest) ⓘ | 3.53 | 2.08 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.27 | 2.28 |
| Net Debt / EBITDA (Latest) ⓘ | 2.79 | 1.40 |
| Net Debt / Assets ⓘ | 10.38% | 19.16% |
| EBITDA / Interest ⓘ | 8.04 | 10.09 |
| Operating Margin (Latest) ⓘ | 7.87% | 10.30% |
| Operating Margin (5Y Median) ⓘ | 10.89% | 10.29% |
| Debt to Equity (Latest) ⓘ | 52.90% | 64.92% |
| Profit Margin (Latest) ⓘ | 7.09% | 6.73% |
| Free Cash Flow (Latest) ⓘ | $284.84M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +61.71% | +56.30% |
| 12M Return (excl. last month) ⓘ | -18.07% | +11.78% |
| 6M Return ⓘ | -25.41% | +0.98% |
| Price vs. 200-Day MA ⓘ | -6.99% | +1.53% |
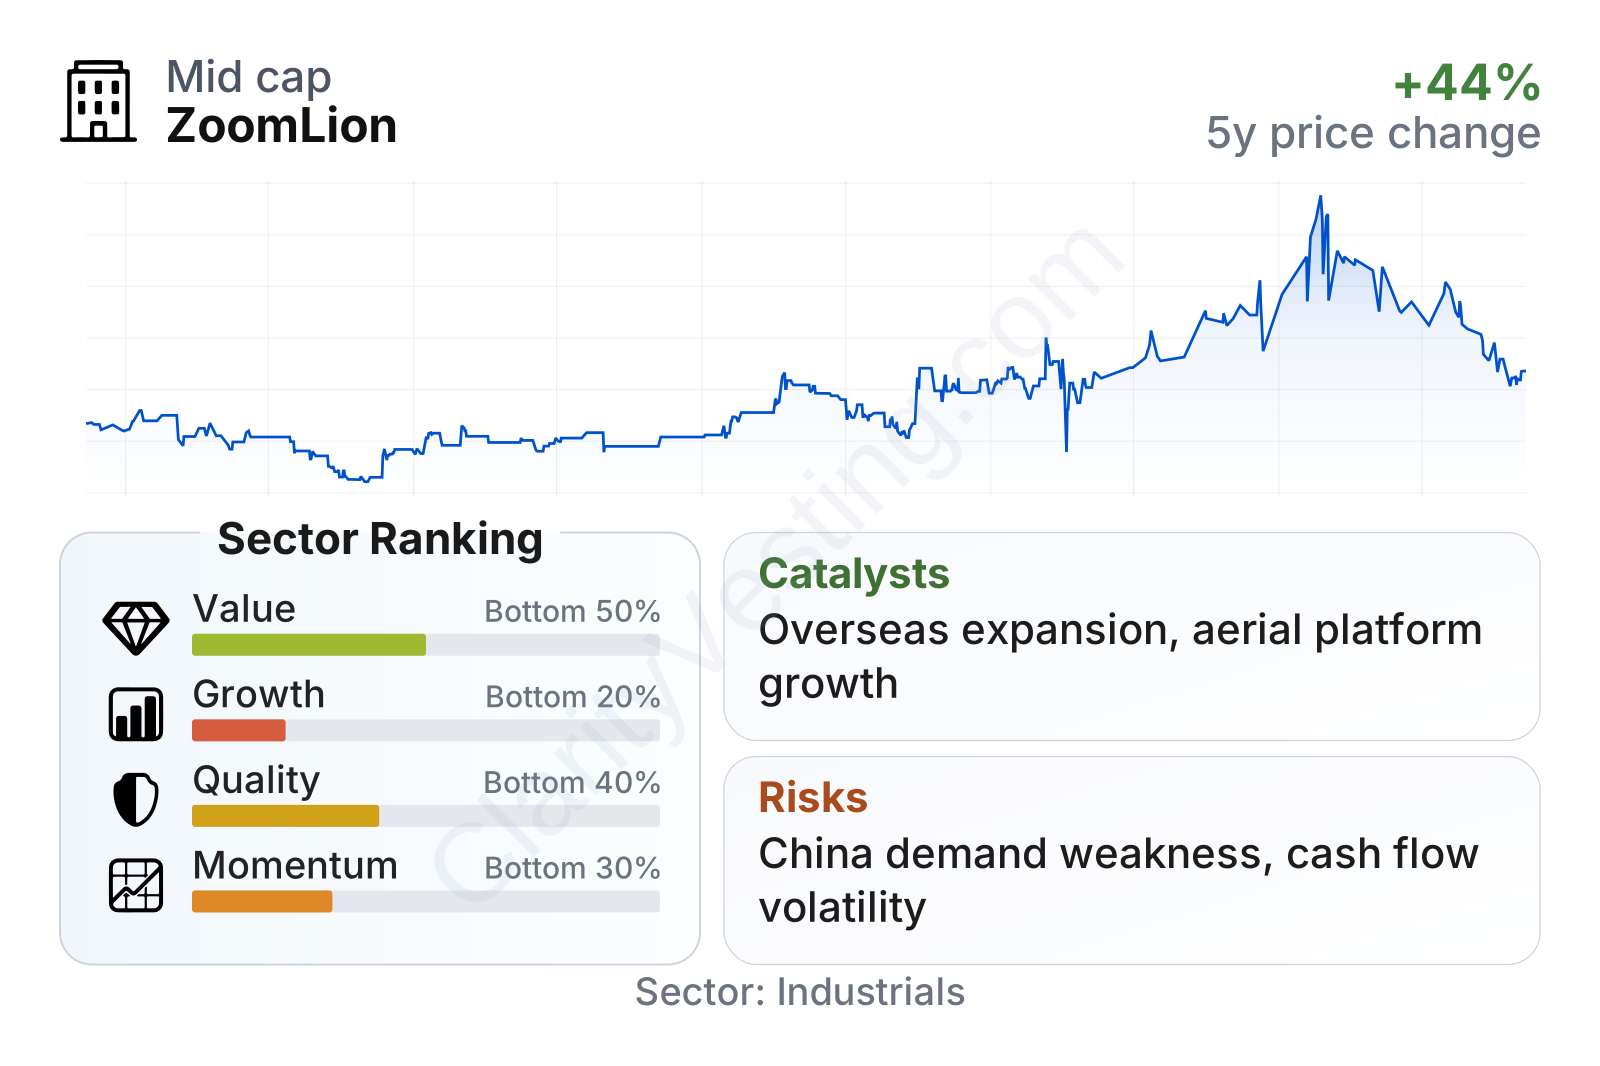
Zoomlion stands out as a mid-to-large industrial company with a relatively low share-price volatility, reflected in a beta well below 1. On valuation, its earnings multiple is below the sector median, which suggests the market is not assigning a premium to the business. The tradeoff is that growth and quality metrics rank below many peers: recent revenue growth is modest, returns on capital are weaker than the sector median, and momentum has been soft over the last 6 to 12 months. One notable exception is income distribution, with a trailing dividend yield far above the sector median, although dividend sustainability always depends on future cash generation rather than headline yield alone.
Growth
Zoomlion operates in sectors that should remain relevant for years: construction equipment, lifting machinery, access platforms, and agricultural mechanization. These are not speculative markets. They are tied to long-term needs such as urbanization, infrastructure renewal, industrial automation, logistics, and farm productivity. Demand can be cyclical, but the end markets themselves are durable.
The strongest part of the company’s growth logic is international expansion. Chinese machinery makers have increasingly tried to grow abroad as domestic construction markets became more competitive and less predictable. For Zoomlion, this strategy makes sense because it can spread manufacturing scale, broaden its customer base, and reduce reliance on any single economic cycle. The aerial work platform business is also strategically important because it is one of the faster-evolving segments in equipment, with applications across maintenance, construction, warehousing, and industrial services.
The short-term growth record has been uneven. The company experienced severe year-over-year declines during the downcycle, which shows how exposed it is to swings in equipment demand. More recently, annual revenue has moved back into positive territory, but still below the broader sector’s median pace. That means Zoomlion’s recovery is real, yet not especially fast by industry standards.
Cash generation is another area to watch closely. Free cash flow has been volatile, including periods of negative readings and only a modest positive level on a trailing basis. For an industrial manufacturer, that often reflects working-capital swings, dealer inventory movements, and the timing of customer payments. If revenue recovery continues and overseas sales scale further, stronger cash conversion could become an important catalyst because it would support balance-sheet flexibility and make earnings quality look more convincing.
Recent company communications have continued to emphasize intelligent manufacturing, digitalization, new-energy equipment, and overseas development. Those themes fit the direction of the global machinery industry. Smarter and more energy-efficient machines can improve differentiation, while a broader international footprint can open markets where replacement demand and infrastructure spending are more favorable than in China’s current construction cycle.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer