Stock Analysis · Xpeng Inc (XPEV)
Overview
XPeng Inc is a Chinese smart electric vehicle maker focused on mass-premium cars, SUVs, and related software. The company designs, develops, manufactures, and sells battery electric vehicles under the XPENG brand. It also builds software features around the car, including advanced driver-assistance systems, in-car operating systems, connectivity, charging support, and other mobility-related services. In practical terms, XPeng is trying to position itself as a technology-driven EV manufacturer rather than only a traditional car company.
The business is still overwhelmingly centered on vehicle sales. Based on the company’s annual disclosures, revenue is mainly generated from the following sources:
- Vehicle sales: about 91% to 94% of revenue in recent years. This includes sales of XPeng-branded electric cars, mainly sedans and SUVs.
- Services and others: about 6% to 9% of revenue. This generally includes maintenance services, supercharging, automotive financing-related arrangements, vehicle parts, accessories, and other supporting automotive services.
That concentration matters: XPeng’s results depend primarily on how many vehicles it delivers, what prices it can sustain, and whether production scale can improve margins. The company has also been expanding its product range and international footprint, while continuing to invest heavily in software and intelligent driving capabilities.
From a high-level financial flow perspective, revenue has grown sharply over the last several years, but profitability has remained under pressure because manufacturing costs, research spending, and selling expenses have consumed most of the gross profit. The recent direction is better than the earlier period, with losses narrowing materially by 2025, but the path to consistent profits is not yet complete.
The long-term pattern shown here is a business that has scaled fast, improved gross profit after a weak 2023, and kept investing aggressively in product development. That combination can support future competitiveness, but it also explains why XPeng still has to prove that higher revenue can translate into durable earnings.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Nov 11, 2026 | |
| Context | ||
| Sector | Consumer Cyclical | |
| Industry | Auto Manufacturers | |
| Market Cap ⓘ | $9.70B | |
| Beta ⓘ | 0.98 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 17.68 |
| P/B Ratio ⓘ | N/A | 2.77 |
| FCF Yield ⓘ | 6.39% | 7.34% |
| Dividend Yield ⓘ | N/A | 2.54% |
| EBIT / EV ⓘ | -3.29% | 7.09% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 8.00% | 5.10% |
| RPS Growth (5Y CAGR) ⓘ | 88.47% | 8.97% |
| EPS Growth (5Y CAGR) ⓘ | -55.56% | -12.24% |
| BVPS Growth (5Y CAGR) ⓘ | 25.58% | 5.63% |
| Margin Growth (5Y Trend) ⓘ | N/A | -0.17% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 5.89% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 10.17% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -3.35% | 11.42% |
| ROA (Latest) ⓘ | -3.11% | 5.57% |
| ROIC (5Y Median) ⓘ | -9.32% | 10.52% |
| ROA (5Y Median) ⓘ | -8.81% | 5.37% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 2.04 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 2.24 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 1.44 |
| Net Debt / Assets ⓘ | 19.38% | 21.02% |
| EBITDA / Interest ⓘ | N/A | 9.63 |
| Operating Margin (Latest) ⓘ | -3.39% | 9.14% |
| Operating Margin (5Y Median) ⓘ | -22.78% | 9.64% |
| Debt to Equity (Latest) ⓘ | 151.26% | 71.37% |
| Profit Margin (Latest) ⓘ | -4.14% | 5.35% |
| Free Cash Flow (Latest) ⓘ | $620.45M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -33.62% | +21.42% |
| 12M Return (excl. last month) ⓘ | -52.90% | 0.00% |
| 6M Return ⓘ | -37.28% | +1.94% |
| Price vs. 200-Day MA ⓘ | -28.26% | +1.50% |
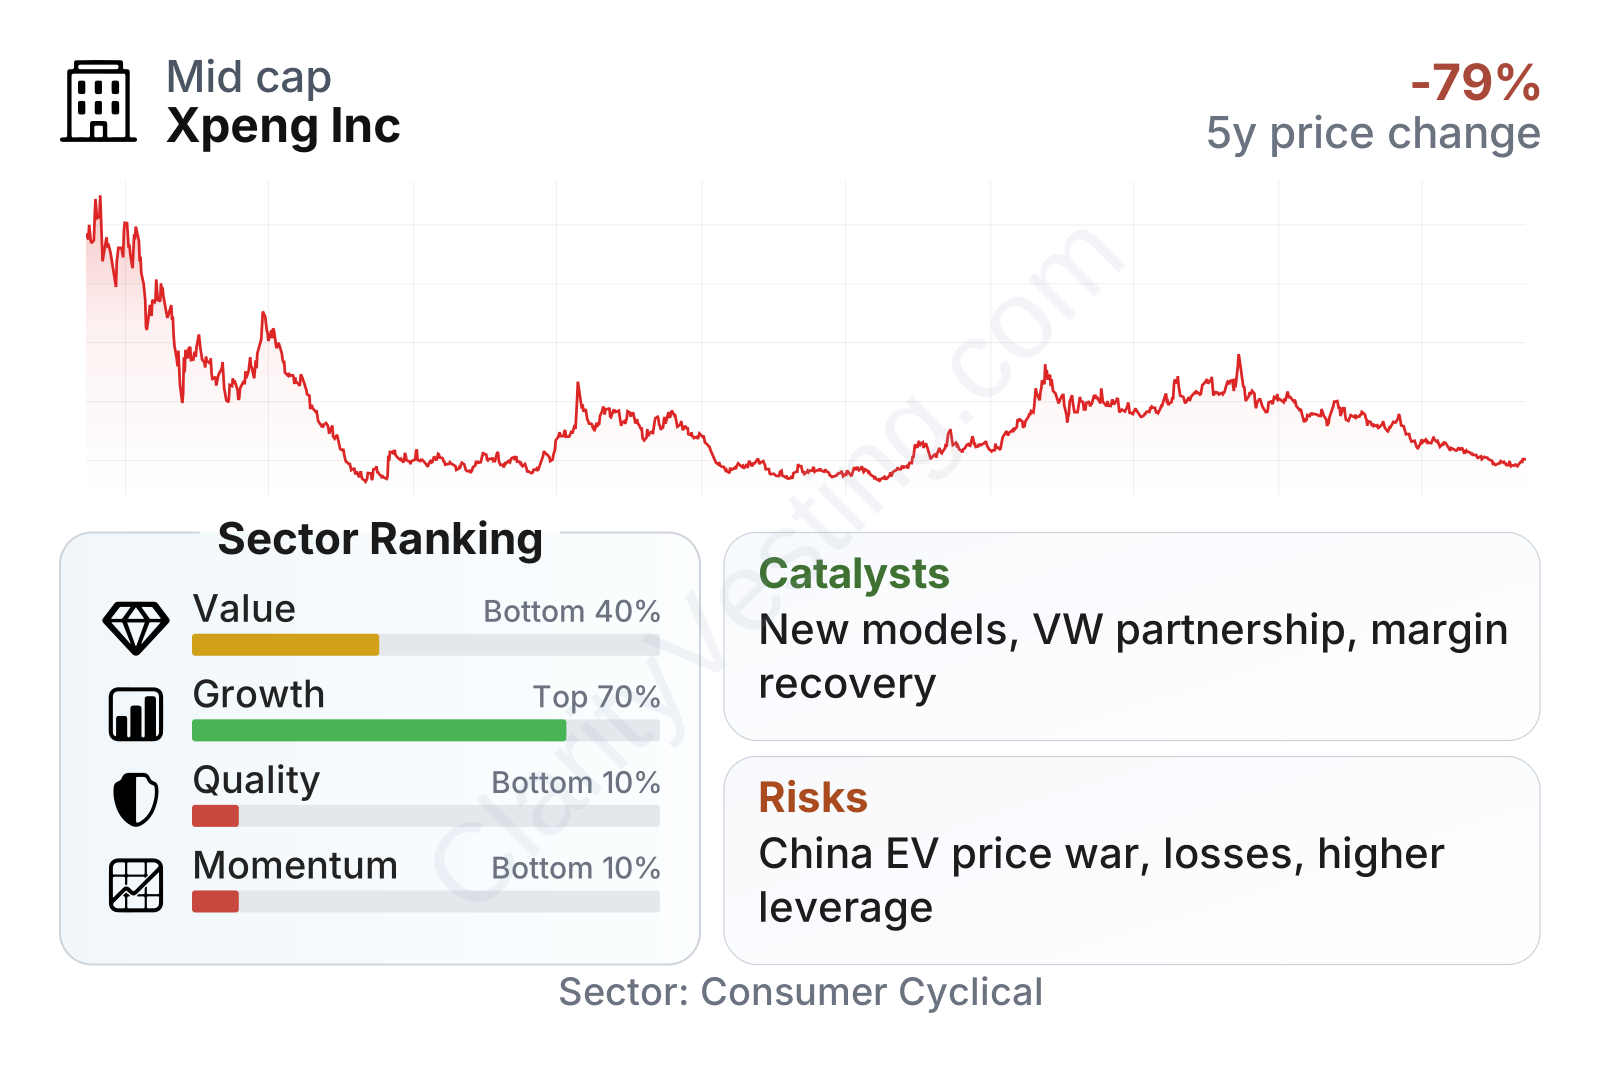
XPeng sits in the mid-sized range by market value and its share price has been highly volatile over the last few years, which is common among younger EV manufacturers. In the factor breakdown, growth stands above much of the sector, helped by strong multi-year revenue expansion, while quality and momentum are weak. That mix describes a company with real commercial progress but an incomplete financial profile: sales are rising, free cash flow has turned positive, yet profitability and returns on capital remain below industry norms.
Valuation metrics are also hard to read in the usual way because earnings are still negative. That makes book value, cash generation, delivery growth, and margin improvement more useful than conventional earnings multiples when assessing the company’s current position.
Growth
XPeng operates in the electric vehicle market, which remains a structural growth industry even if the pace is uneven. Over the long run, stricter emissions rules, consumer interest in lower operating costs, charging network expansion, and software-led vehicle features all support EV adoption. China is already the world’s largest EV market, and it remains the company’s core arena. That creates both opportunity and intense competition.
XPeng’s strategy for growth is coherent. It is expanding its model lineup, targeting larger volumes, improving manufacturing scale, and leaning on software differentiation through intelligent driving and connected-vehicle features. The company has also been pushing further into overseas markets and broadening price coverage across product categories. For an automaker at this stage, that matters because scale is one of the main drivers of margin improvement.
The revenue trend has been volatile, which is typical for a company exposed to model launches, price competition, and changing demand conditions. Even so, the broader picture remains one of strong expansion over the last several years. Recent year-over-year growth has cooled sharply from the exceptional bursts seen around major rollout periods, but the company still compares favorably with much of the broader sector on multi-year top-line growth.
Another encouraging point is cash generation. XPeng has posted positive trailing free cash flow, which suggests the business is not relying only on accounting improvements to show progress. Positive free cash flow does not remove execution risk, but it does indicate that operations and working capital have improved compared with earlier, more cash-intensive phases.
A notable catalyst for XPeng is its partnership structure around technology and manufacturing scale. The company has drawn attention through collaboration with Volkswagen on EV-related platforms and technology, which supports credibility and may help spread development costs over a broader base. XPeng has also continued launching newer models and refreshing existing vehicles, an important factor in China’s fast-moving EV market where product cycles are short and consumer preferences shift quickly.
Recent company communications have also highlighted strong delivery momentum during parts of 2025 and continued product rollout efforts. For a business like XPeng, sustained delivery growth combined with better gross margin is the key bridge between being a fast-growing EV maker and becoming a financially stronger automaker.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer