Stock Analysis · Zijin Mining Group Co Ltd-H (ZIJMF)
Overview
Zijin Mining Group is a large Chinese mining company focused on metals that matter both to the traditional economy and to the energy transition. It explores, develops, and operates mines for gold, copper, zinc, silver, and lithium, and it also runs some smelting and refining activities. In simple terms, the company digs valuable metals out of the ground, processes part of them, and sells them into industrial and financial markets around the world.
The business is built around two main profit engines: gold and copper. Gold gives the company exposure to a metal that often performs well when inflation, geopolitical tension, or currency concerns rise. Copper gives exposure to electrification, power grids, electric vehicles, and general industrial demand. That mix is important because it makes Zijin more than a pure gold miner.
Based on the company’s recent annual reporting and operating disclosures, revenue is spread across several metals and products, with processed and mined products both contributing. Exact percentages can move meaningfully with metal prices, shipment timing, and the share of concentrate versus refined products sold, but the broad picture is clear:
- Copper-related products: approximately 45% to 55% of revenue. This includes copper cathode, copper concentrate, blister copper, and other copper products.
- Gold-related products: approximately 30% to 40% of revenue. This includes mined gold, refined gold, and gold products sold through trading and processing channels.
- Zinc, lead, and silver-related products: approximately 5% to 15% of revenue, depending on prices and production mix.
- Other minerals and materials, including lithium and by-products: generally a small but growing share of revenue.
Zijin’s asset base is geographically diversified, with operations and projects in China as well as overseas regions including Central Asia, Africa, South America, and parts of Europe. That wide footprint gives it more growth options than many single-country miners, although it also adds political and operational complexity.
The financial flow over the last several years shows an encouraging pattern: revenue has grown steadily, while operating income and net income have expanded even faster. That suggests the company has recently benefited not only from scale, but also from stronger margins and improved operating efficiency.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Nov 21, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Gold | |
| Market Cap ⓘ | $85.89B | |
| Beta ⓘ | 1.00 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 8.73 | 15.60 |
| P/B Ratio ⓘ | N/A | 2.20 |
| FCF Yield ⓘ | 13.03% | 5.22% |
| Dividend Yield ⓘ | 23.81% | 1.93% |
| EBIT / EV ⓘ | 16.43% | 8.17% |
| PEG ⓘ | 1.08 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 3.20% | 10.90% |
| RPS Growth (5Y CAGR) ⓘ | 10.08% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | 30.12% | -9.13% |
| BVPS Growth (5Y CAGR) ⓘ | 13.93% | 5.53% |
| Margin Growth (5Y Trend) ⓘ | 10.66% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 65.52% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 25.15% | 5.68% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 27.02% | 8.91% |
| ROA (Latest) ⓘ | 13.24% | 5.01% |
| ROIC (5Y Median) ⓘ | 16.58% | 7.91% |
| ROA (5Y Median) ⓘ | 8.02% | 3.90% |
| Net Debt / EBIT (Latest) ⓘ | 0.73 | 1.33 |
| Net Debt / EBIT (5Y Median) ⓘ | 2.23 | 1.69 |
| Net Debt / EBITDA (Latest) ⓘ | 0.71 | 0.95 |
| Net Debt / Assets ⓘ | 15.67% | 12.22% |
| EBITDA / Interest ⓘ | 31.89 | 12.78 |
| Operating Margin (Latest) ⓘ | 31.94% | 13.23% |
| Operating Margin (5Y Median) ⓘ | 12.28% | 11.87% |
| Debt to Equity (Latest) ⓘ | 85.36% | 40.11% |
| Profit Margin (Latest) ⓘ | 18.88% | 7.03% |
| Free Cash Flow (Latest) ⓘ | $11.19B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +172.81% | +45.33% |
| 12M Return (excl. last month) ⓘ | -4.38% | +16.67% |
| 6M Return ⓘ | -23.52% | -8.36% |
| Price vs. 200-Day MA ⓘ | -28.36% | -8.36% |
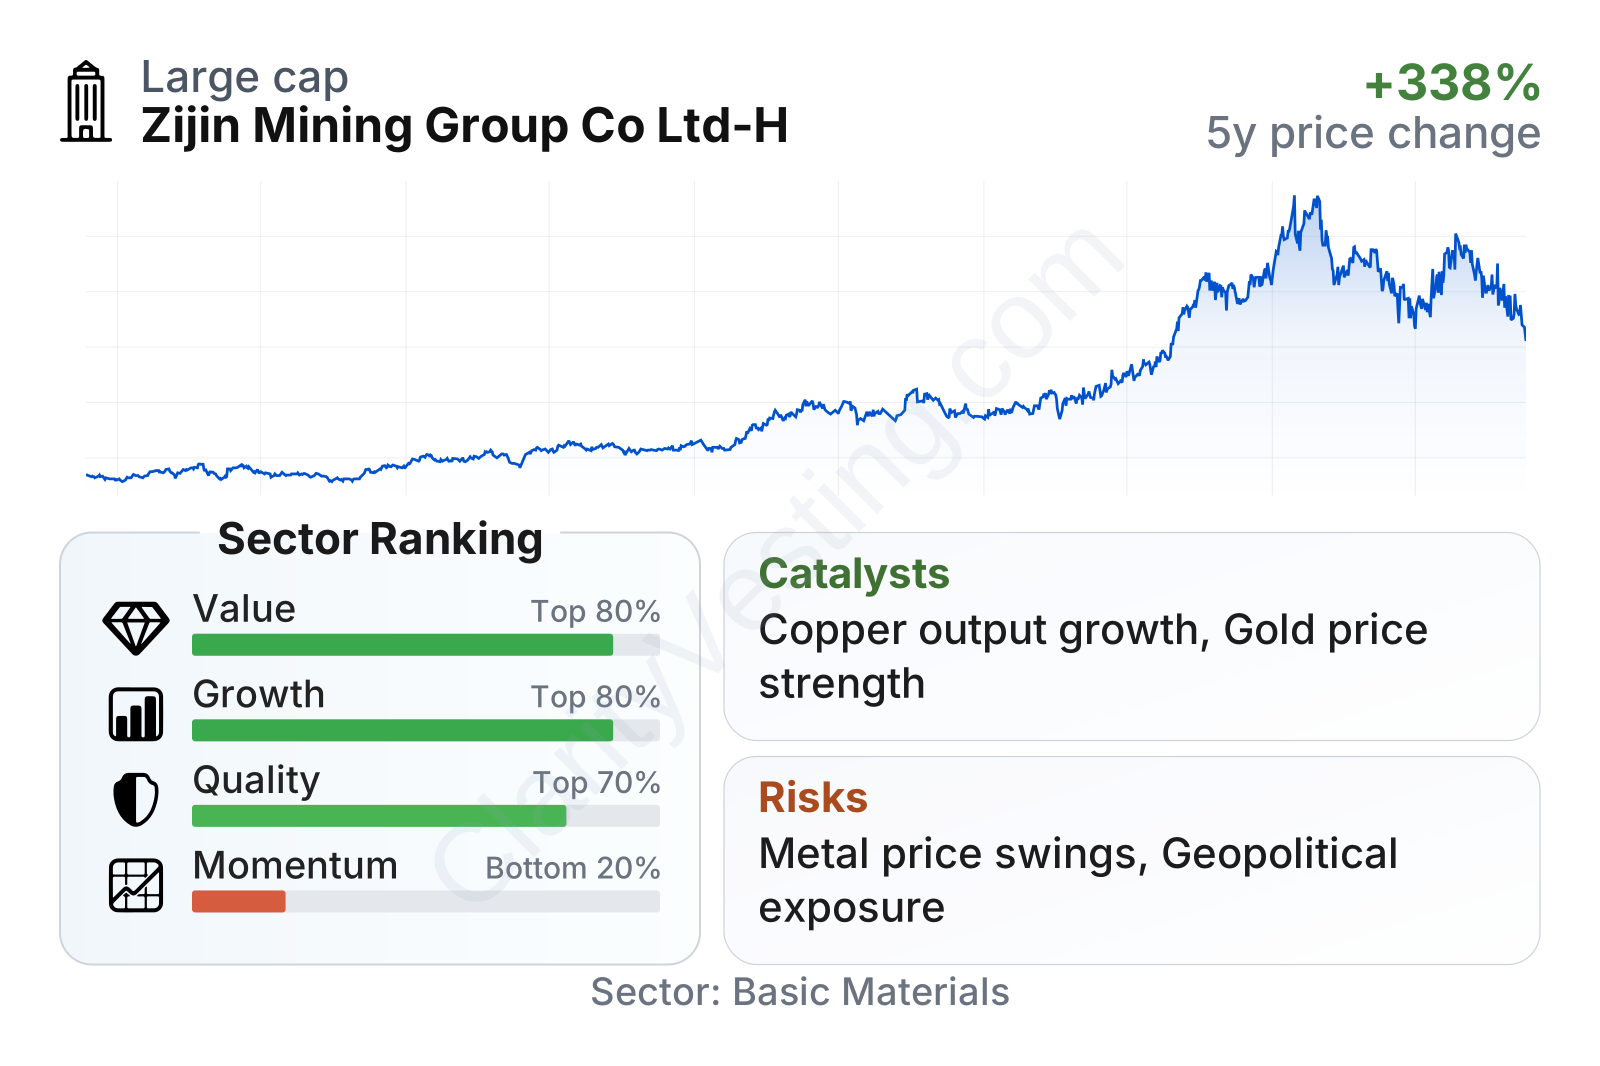
Zijin is a very large mining company by market value, and its share price behavior has been close to the overall market in volatility terms, with a beta around 1. The valuation section of the metrics table looks notably undemanding relative to much of the sector: the earnings multiple is below the sector median, free cash flow yield is well above average, and the operating earnings yield on enterprise value is also strong. Quality is another bright spot, with returns on capital and returns on assets clearly above sector norms. The weaker area is recent momentum: after a very strong multiyear run, the shares have been softer over the last 6 to 12 months than many peers, which often means the market is digesting prior gains or reassessing near-term commodity expectations.
Growth
Zijin operates in a sector with long-term structural support. Gold remains relevant as a store of value and reserve asset, while copper is one of the clearest beneficiaries of electrification, renewable energy buildout, grid upgrades, electric vehicles, and data center infrastructure. Lithium adds another link to battery supply chains. For a miner with material exposure to several of these metals, the industry backdrop is favorable over a multiyear period even if short-term commodity prices remain volatile.
The company’s strategy also makes industrial sense. Instead of relying on one mature mining district, Zijin has expanded through a mix of resource development, acquisitions, and brownfield optimization at existing assets. That approach can work well in mining because increasing output from known deposits is often less risky than depending entirely on brand-new discoveries. The company has spent years building a pipeline across copper, gold, and emerging battery materials, giving it several ways to grow rather than one single project deciding the whole future.
Revenue growth has clearly cooled from the unusually strong pace seen in earlier periods, and the latest year-over-year increase is modest. Even so, the longer pattern still points to expansion rather than stagnation. More importantly, earnings growth over five years has been far stronger than revenue growth, which indicates that mine mix, costs, grades, and pricing have moved in the company’s favor over time.
Cash generation has improved sharply after a weak patch. Free cash flow turned negative at one point, which is common in mining during heavy investment phases, but the rebound has been substantial and the trailing figure now sits at a very strong level. For a capital-intensive business, that matters. Healthy cash flow supports project development, debt management, and dividend capacity without requiring constant outside financing.
One of the clearest catalysts is rising production from major copper and gold assets developed or expanded in recent years. Another is the possibility of sustained high copper and gold prices: copper because of supply tightness and electrification demand, gold because of central bank buying, inflation hedging, and macro uncertainty. In addition, Zijin’s growing lithium exposure gives the group a potential extra leg of growth if battery material markets recover from recent weakness.
Recent company updates have also highlighted continued mine development and reserve growth efforts, which are particularly important in this industry. A miner that can replace and expand reserves has a much stronger long-term profile than one that is simply harvesting mature assets.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


