Stock Analysis · Zhuzhou CRRC Times Electric Co. Ltd (ZHUZF)
Overview
Zhuzhou CRRC Times Electric Co. Ltd is a Chinese industrial technology company best known for supplying the electronic and power systems used in trains and urban transit. It develops and manufactures traction systems, power semiconductor devices, control systems, signaling-related products, and other equipment that help locomotives, high-speed trains, subways, and new-energy vehicles operate efficiently. The company is part of the wider CRRC ecosystem, which matters because CRRC is one of the largest rail equipment groups in the world.
For long-term analysis, the business is easier to understand if it is viewed as a supplier of “brains and power components” for transportation equipment. In rail, that means traction converters, motors, and control systems. Outside rail, the company has expanded into power semiconductors and electric-drive technologies used in areas such as electric vehicles and industrial applications. This broadens its addressable market beyond train manufacturing alone.
Based on company reporting in recent annual disclosures, revenue is mainly generated from the following areas:
- Rail transit electrical equipment: approximately 50% to 60% of revenue. This usually includes traction converter systems, auxiliary power supply systems, train control electrical products, and related onboard equipment.
- Power semiconductor devices: approximately 20% to 30% of revenue. This segment includes devices such as IGBT modules and related semiconductor products used in rail, renewable energy, industrial drives, and electric vehicles.
- Industrial and other electrical equipment: approximately 10% to 20% of revenue. This typically includes electric-drive systems, sensor products, testing services, and other industrial electrification products.
- Emerging businesses and other activities: generally a small share of revenue, depending on the year, and can include newer mobility and technology-related offerings.
The overall business mix shows a company still anchored in rail transportation, but increasingly supported by semiconductor and electrification activities. That matters because rail tends to provide stability, while semiconductors and vehicle electrification offer faster growth potential.
The operating profile has improved over the last several years. Revenue has risen steadily, gross profit has expanded, and net income has moved upward as well. One notable feature is the company’s sustained research and development spending, which has increased meaningfully over time. That supports its position as a technology supplier rather than a simple parts manufacturer, although it also means cash generation can be less smooth than accounting profits.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Nov 21, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Railroads | |
| Market Cap ⓘ | $4.75B | |
| Beta ⓘ | 0.27 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 10.50 | 20.77 |
| P/B Ratio ⓘ | N/A | 3.20 |
| FCF Yield ⓘ | -3.05% | 4.98% |
| Dividend Yield ⓘ | 31.23% | 1.88% |
| EBIT / EV ⓘ | N/A | 6.24% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 17.10% | 9.60% |
| RPS Growth (5Y CAGR) ⓘ | 14.17% | 7.69% |
| EPS Growth (5Y CAGR) ⓘ | -8.06% | -5.74% |
| BVPS Growth (5Y CAGR) ⓘ | 2.02% | 6.13% |
| Margin Growth (5Y Trend) ⓘ | 1.93% | 0.72% |
| FCF Growth (5Y CAGR) ⓘ | -30.25% | 11.01% |
| DPS Growth (5Y CAGR) ⓘ | 27.12% | 9.09% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 10.48% |
| ROA (Latest) ⓘ | 5.86% | 5.38% |
| ROIC (5Y Median) ⓘ | 7.30% | 9.45% |
| ROA (5Y Median) ⓘ | 5.97% | 4.91% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 2.12 |
| Net Debt / EBIT (5Y Median) ⓘ | -1.02 | 2.28 |
| Net Debt / EBITDA (Latest) ⓘ | 0.47 | 1.42 |
| Net Debt / Assets ⓘ | 3.51% | 19.19% |
| EBITDA / Interest ⓘ | 138.03 | 10.09 |
| Operating Margin (Latest) ⓘ | N/A | 10.44% |
| Operating Margin (5Y Median) ⓘ | 15.22% | 10.29% |
| Debt to Equity (Latest) ⓘ | 13.03% | 66.48% |
| Profit Margin (Latest) ⓘ | 13.62% | 6.98% |
| Free Cash Flow (Latest) ⓘ | -$144.75M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -15.09% | +48.25% |
| 12M Return (excl. last month) ⓘ | +4.75% | +10.31% |
| 6M Return ⓘ | +4.75% | +0.15% |
| Price vs. 200-Day MA ⓘ | +2.82% | 0.00% |
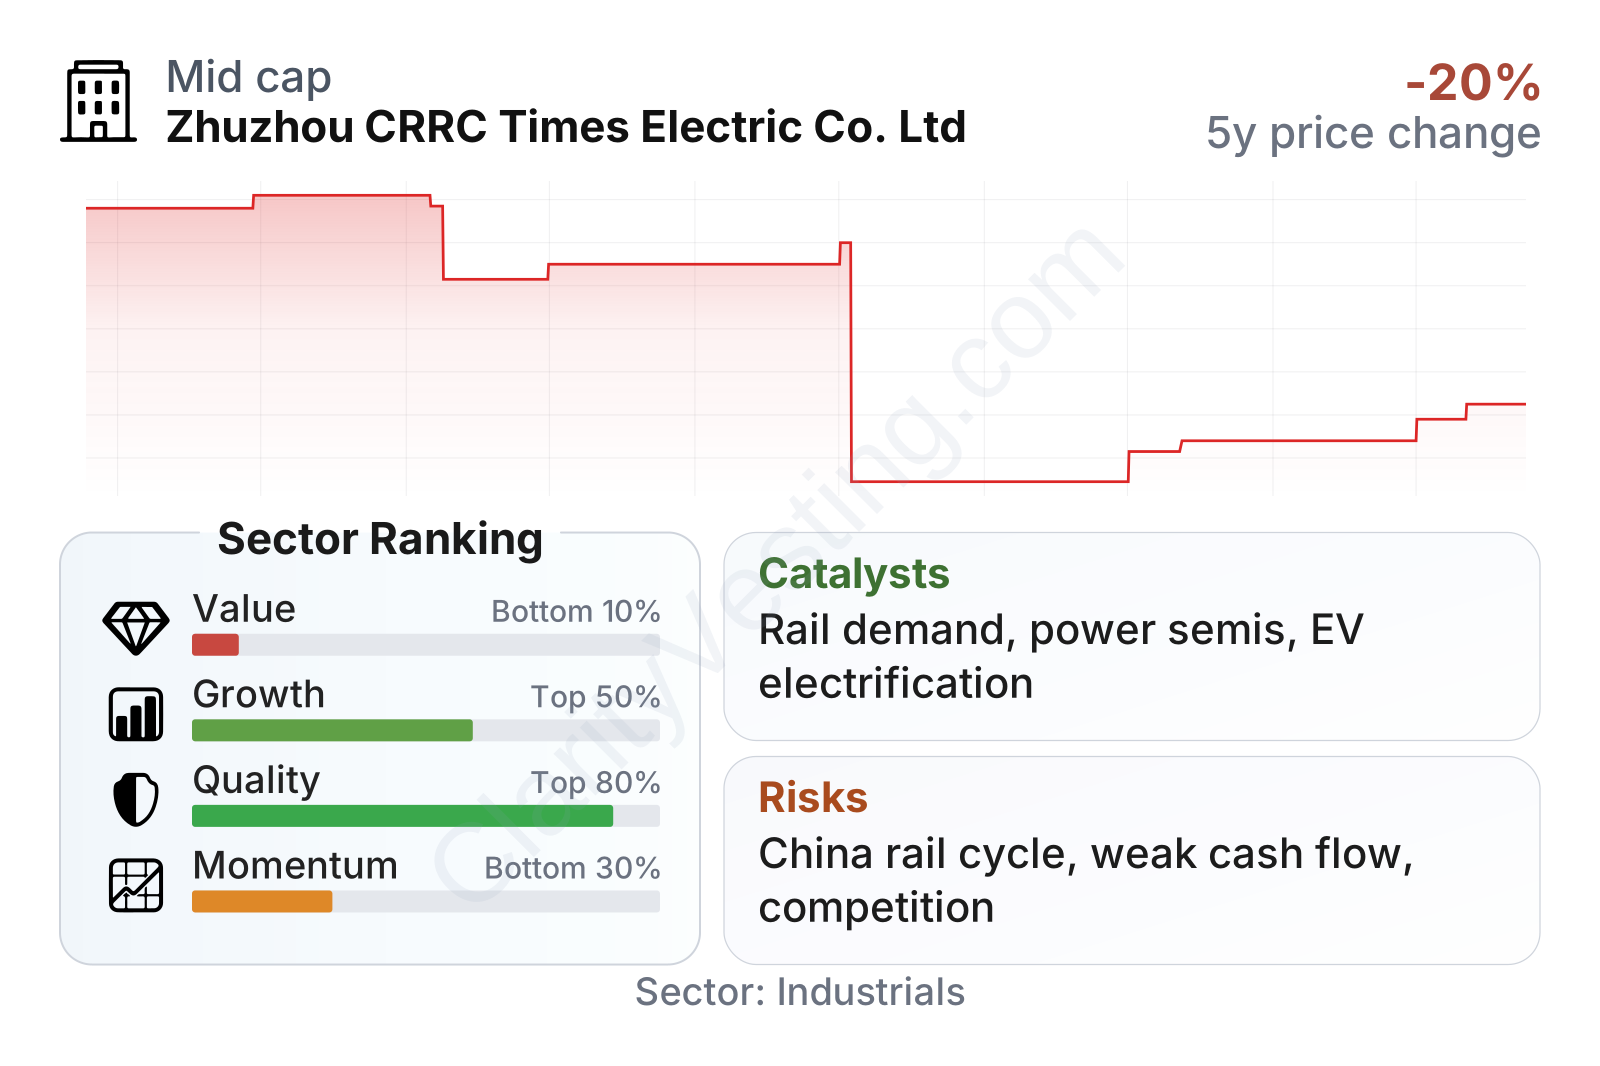
Zhuzhou CRRC Times Electric is a mid-sized industrial company with a relatively low share-price volatility profile, as reflected in its low beta. On valuation, the stock trades at an earnings multiple clearly below the sector median, which suggests the market is not assigning an aggressive premium to its growth prospects. At the same time, its quality indicators are strong: profitability is above many peers, leverage is low, and interest coverage is exceptionally high. The weaker areas are free cash flow and recent share-price momentum, which help explain why the value factor ranks poorly despite solid operating performance.
Growth
The company operates in markets with favorable long-term drivers. Rail transit remains supported by urbanization, replacement demand, and ongoing investment in transport infrastructure, especially in China. On top of that, power semiconductors and electrification are structural growth areas tied to electric vehicles, industrial automation, and energy-efficiency upgrades. This gives the company exposure to both a relatively stable installed base business and faster-growing technology categories.
Its strategy also appears coherent. The rail business provides scale, customer relationships, and a demanding engineering environment that can support product development. The semiconductor and electric-drive businesses create a second growth engine that is not entirely dependent on new rail project timing. That combination is valuable because it reduces reliance on a single product family while still staying within the company’s core capabilities in power electronics and control systems.
Revenue growth has generally remained positive, though it has moderated from stronger periods. The latest year-over-year growth rate is still above the sector median, and the five-year revenue-per-share growth record is also stronger than many peers. In other words, the top line has been expanding at a healthy pace, even if growth is no longer as rapid as during the earlier rebound years.
A more cautious point is cash conversion. Free cash flow has deteriorated and recently turned negative on a trailing basis. This does not automatically mean the business is weakening, because working capital swings, inventory build, customer payment timing, and capacity investment can all distort short-term cash results. Still, for a long-term view, it is important that revenue growth ultimately translates into more consistent cash generation.
As for catalysts, the most important ones are continued rail equipment demand, broader adoption of domestically produced power semiconductors, and rising electrification across transport and industry. Recent company communications have continued to emphasize product development and expansion in semiconductor-related capabilities, which is significant because that market can carry stronger strategic value than traditional equipment supply alone.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


