Stock Analysis · Zhaojin Mining Industry Company Limited (ZHAOF)
Overview
Zhaojin Mining Industry Company Limited is a China-based gold producer. Its business centers on the exploration, mining, processing, smelting, and sale of gold, with additional exposure to copper and other by-products. In simple terms, it pulls ore from mines, refines valuable metals, and sells them into industrial and precious metals markets. The company is part of the basic materials sector, but its economics are driven mainly by gold prices, ore grades, production volumes, and the cost of operating mines.
The company’s revenue base is concentrated in precious metals, especially gold. Public company materials indicate that gold-related products are the dominant earnings engine, while copper and other mineral products provide additional support. Exact line-by-line percentages can vary by year, but the business mix can be summarized as follows:
- Gold products: approximately 75% to 90% of revenue in recent years. This usually includes mined gold, refined gold, and related processing output.
- Copper products: approximately 10% to 20% of revenue. This includes copper concentrate and other copper-related sales from the company’s mining portfolio.
- Other products and services: generally below 10% of revenue. This can include by-products, processing-related activities, and smaller mineral contributions.
Zhaojin stands out as a mid-to-large listed gold miner rather than a diversified global mining giant. That matters for long-term analysis: when gold prices are strong, the business can scale earnings quickly, but the company is also more exposed to a single commodity cycle than highly diversified peers.
The operating picture has improved sharply over the last several years. Revenue has expanded from roughly 6.9 billion to 17.6 billion, while net income rose from near break-even levels in 2021 to more than 3.5 billion by 2025. That suggests not only stronger selling prices, but also much better conversion of sales into operating profit and cash generation.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Gold | |
| Market Cap ⓘ | $9.03B | |
| Beta ⓘ | 0.94 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 18.21 | 16.92 |
| P/B Ratio ⓘ | 0.45 | 1.66 |
| FCF Yield ⓘ | 76.29% | 5.83% |
| Dividend Yield ⓘ | N/A | 2.07% |
| EBIT / EV ⓘ | N/A | 6.38% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 16.00% | 11.25% |
| RPS Growth (5Y CAGR) ⓘ | 24.32% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | -15.38% | -15.24% |
| BVPS Growth (5Y CAGR) ⓘ | 8.85% | 5.49% |
| Margin Growth (5Y Trend) ⓘ | 20.09% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 65.42% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 12.48% | 5.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.59% |
| ROA (Latest) ⓘ | 10.09% | 4.92% |
| ROIC (5Y Median) ⓘ | 3.61% | 7.91% |
| ROA (5Y Median) ⓘ | 1.48% | 3.92% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | 8.74 | 1.69 |
| Net Debt / EBITDA (Latest) ⓘ | 1.81 | 0.93 |
| Net Debt / Assets ⓘ | 31.30% | 13.69% |
| EBITDA / Interest ⓘ | N/A | 12.38 |
| Operating Margin (Latest) ⓘ | N/A | 13.24% |
| Operating Margin (5Y Median) ⓘ | 20.20% | 11.82% |
| Debt to Equity (Latest) ⓘ | 121.43% | 40.30% |
| Profit Margin (Latest) ⓘ | N/A | 6.38% |
| Free Cash Flow (Latest) ⓘ | $6.89B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +85.81% | +73.47% |
| 12M Return (excl. last month) ⓘ | -9.48% | +27.59% |
| 6M Return ⓘ | -39.98% | -4.02% |
| Price vs. 200-Day MA ⓘ | +35.51% | -0.65% |
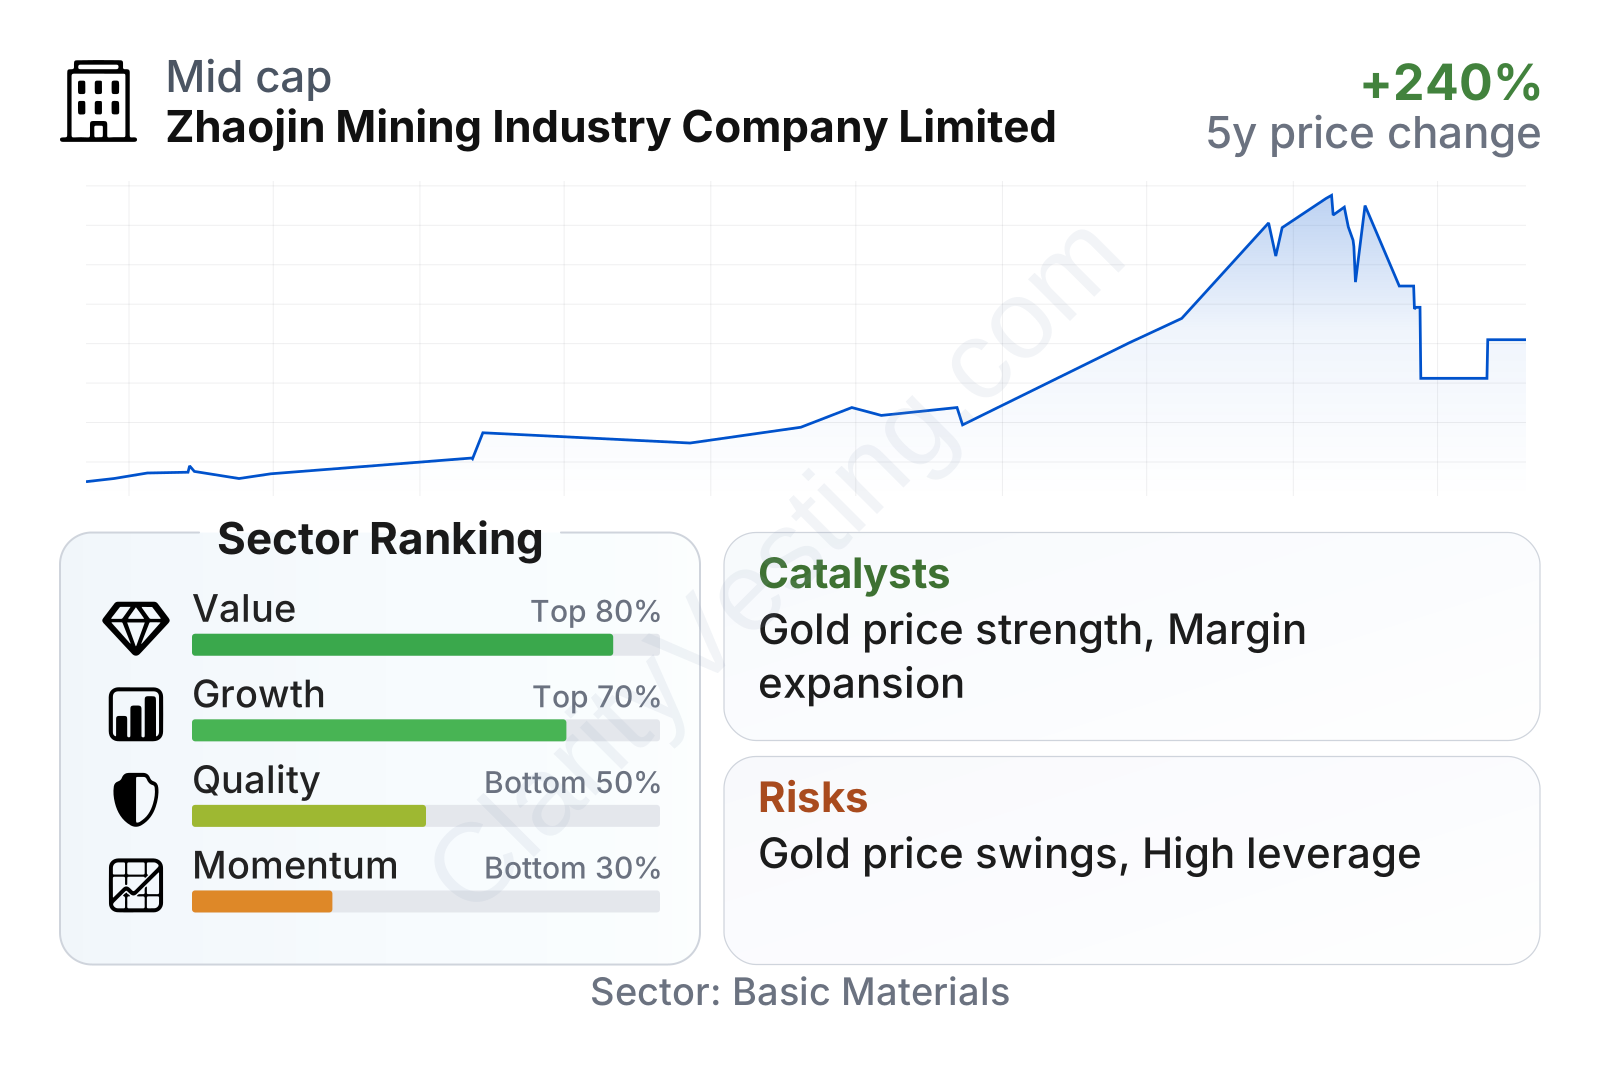
Zhaojin’s profile is unusual in a good way on several headline metrics. Its valuation multiples are not stretched relative to the broader materials group, while price-to-book is notably low. Free cash flow generation and dividend yield both look stronger than the sector median. Growth metrics are also solid, especially revenue per share and free cash flow growth over five years. The weaker area is balance-sheet quality: leverage measures are clearly heavier than many peers, which reduces some of the comfort created by the attractive cash flow and profit trends.
The stock’s trading pattern also sends a mixed message. The longer-term share price performance has been strong, but the shorter-term performance has lagged much of the sector. That combination often appears when a company has improved fundamentals but the market has recently become more cautious about commodity prices, leverage, or the sustainability of margins.
Growth
Gold mining is a mature industry, but the demand backdrop for gold remains structurally relevant. Central bank buying, geopolitical uncertainty, inflation concerns, and the metal’s role as a store of value continue to support long-term interest in gold. For a producer like Zhaojin, this matters because even modest operational improvements can have an outsized effect when the gold price environment is favorable.
The company’s recent trajectory points to a business that has been growing faster than many peers. Revenue growth has been ahead of the sector median on the latest year-over-year reading, and the five-year revenue-per-share trend is particularly strong.
Zhaojin’s strategy also makes industrial sense. A gold miner creates value mainly through three levers: increasing production, improving ore quality or recovery rates, and controlling costs. Public company disclosures describe continued investment in mining resources, production capacity, and operational efficiency. For a producer already benefiting from stronger gold pricing, that framework is logical because it aims to raise output while protecting margins.
Cash generation is another encouraging sign. Free cash flow has improved materially over time, which is especially important in mining because the industry is capital-intensive and needs regular spending on equipment, development, and reserves replacement.
A strong free cash flow trend gives the company more flexibility to fund expansion, manage debt, and maintain shareholder distributions without relying too heavily on new borrowing. This is one of the more important positive signals in Zhaojin’s current profile.
One of the clearest catalysts is simple: gold price strength. Because Zhaojin is heavily tied to gold, sustained high prices can lift revenue and earnings faster than for many other basic materials companies. Another potential catalyst is continued operational optimization if recent margin gains prove durable. The company’s earnings progression from 2021 to 2025 shows that this is not only a volume story; profitability has improved meaningfully as well.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


