Stock Analysis · Yue Yuen Industrial Limited (YUEIF)
Overview
Yue Yuen Industrial Limited is one of the world’s largest athletic and casual footwear manufacturers. The group is best known for making shoes for global brands on an outsourced basis, while also operating a large sportswear and apparel retail network in China through its subsidiary Pou Sheng. In simple terms, one part of the business manufactures shoes for major international labels, and the other part sells branded sports products directly to consumers.
The business is mainly organized around two revenue engines.
- Manufacturing: approximately 69% of 2025 revenue. This segment designs and manufactures athletic, casual, outdoor, and sports shoes for international brand customers, and also includes some footwear components and related activities.
- Retailing: approximately 31% of 2025 revenue. This business is largely tied to Pou Sheng and includes the distribution and retail sale of sportswear, footwear, and apparel through physical stores and digital channels, mainly in Greater China.
That mix matters because manufacturing and retail behave differently. Manufacturing depends heavily on order volumes, factory efficiency, labor costs, and customer concentration. Retail depends more on consumer demand, store productivity, inventory discipline, and the health of the sportswear market in China.
Over the last few years, the company’s revenue has stayed around the low-$8 billion range, but profit recovery has been uneven. The operating picture improved meaningfully from 2021 to 2024, helped by better factory utilization and cost control, before softening in 2025 as operating income came down from the prior year. Even so, net income remained much stronger than the pandemic-disrupted period.
The cost structure shows a business with a very large manufacturing expense base, which is normal for contract footwear production. A notable positive is that operating expenses have trended lower from their earlier peak, while net income recovered sharply from 2021 levels. The weaker point is that gross profit narrowed again in 2025, showing that the business still has limited room for error when demand or product mix turns less favorable.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Nov 21, 2026 | |
| Context | ||
| Sector | Consumer Cyclical | |
| Industry | Footwear & Accessories | |
| Market Cap ⓘ | $2.89B | |
| Beta ⓘ | 0.80 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 10.00 | 17.13 |
| P/B Ratio ⓘ | 0.64 | 2.72 |
| FCF Yield ⓘ | 24.12% | 7.52% |
| Dividend Yield ⓘ | 9.28% | 2.43% |
| EBIT / EV ⓘ | 9.79% | 7.11% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -2.20% | 5.30% |
| RPS Growth (5Y CAGR) ⓘ | -1.36% | 8.77% |
| EPS Growth (5Y CAGR) ⓘ | -2.72% | -11.05% |
| BVPS Growth (5Y CAGR) ⓘ | 3.13% | 5.47% |
| Margin Growth (5Y Trend) ⓘ | 1.73% | -0.16% |
| FCF Growth (5Y CAGR) ⓘ | 15.90% | 5.66% |
| DPS Growth (5Y CAGR) ⓘ | -46.36% | 9.76% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 11.36% |
| ROA (Latest) ⓘ | N/A | 5.53% |
| ROIC (5Y Median) ⓘ | 5.49% | 10.58% |
| ROA (5Y Median) ⓘ | 3.59% | 5.35% |
| Net Debt / EBIT (Latest) ⓘ | 2.04 | 2.11 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.00 | 2.24 |
| Net Debt / EBITDA (Latest) ⓘ | 0.79 | 1.51 |
| Net Debt / Assets ⓘ | 8.33% | 21.74% |
| EBITDA / Interest ⓘ | N/A | 9.63 |
| Operating Margin (Latest) ⓘ | 3.12% | 9.20% |
| Operating Margin (5Y Median) ⓘ | 4.67% | 9.64% |
| Debt to Equity (Latest) ⓘ | 27.25% | 74.26% |
| Profit Margin (Latest) ⓘ | 3.55% | 5.47% |
| Free Cash Flow (Latest) ⓘ | $696.52M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +103.23% | +15.79% |
| 12M Return (excl. last month) ⓘ | +20.68% | -0.63% |
| 6M Return ⓘ | -9.47% | +1.17% |
| Price vs. 200-Day MA ⓘ | +30.45% | +0.36% |
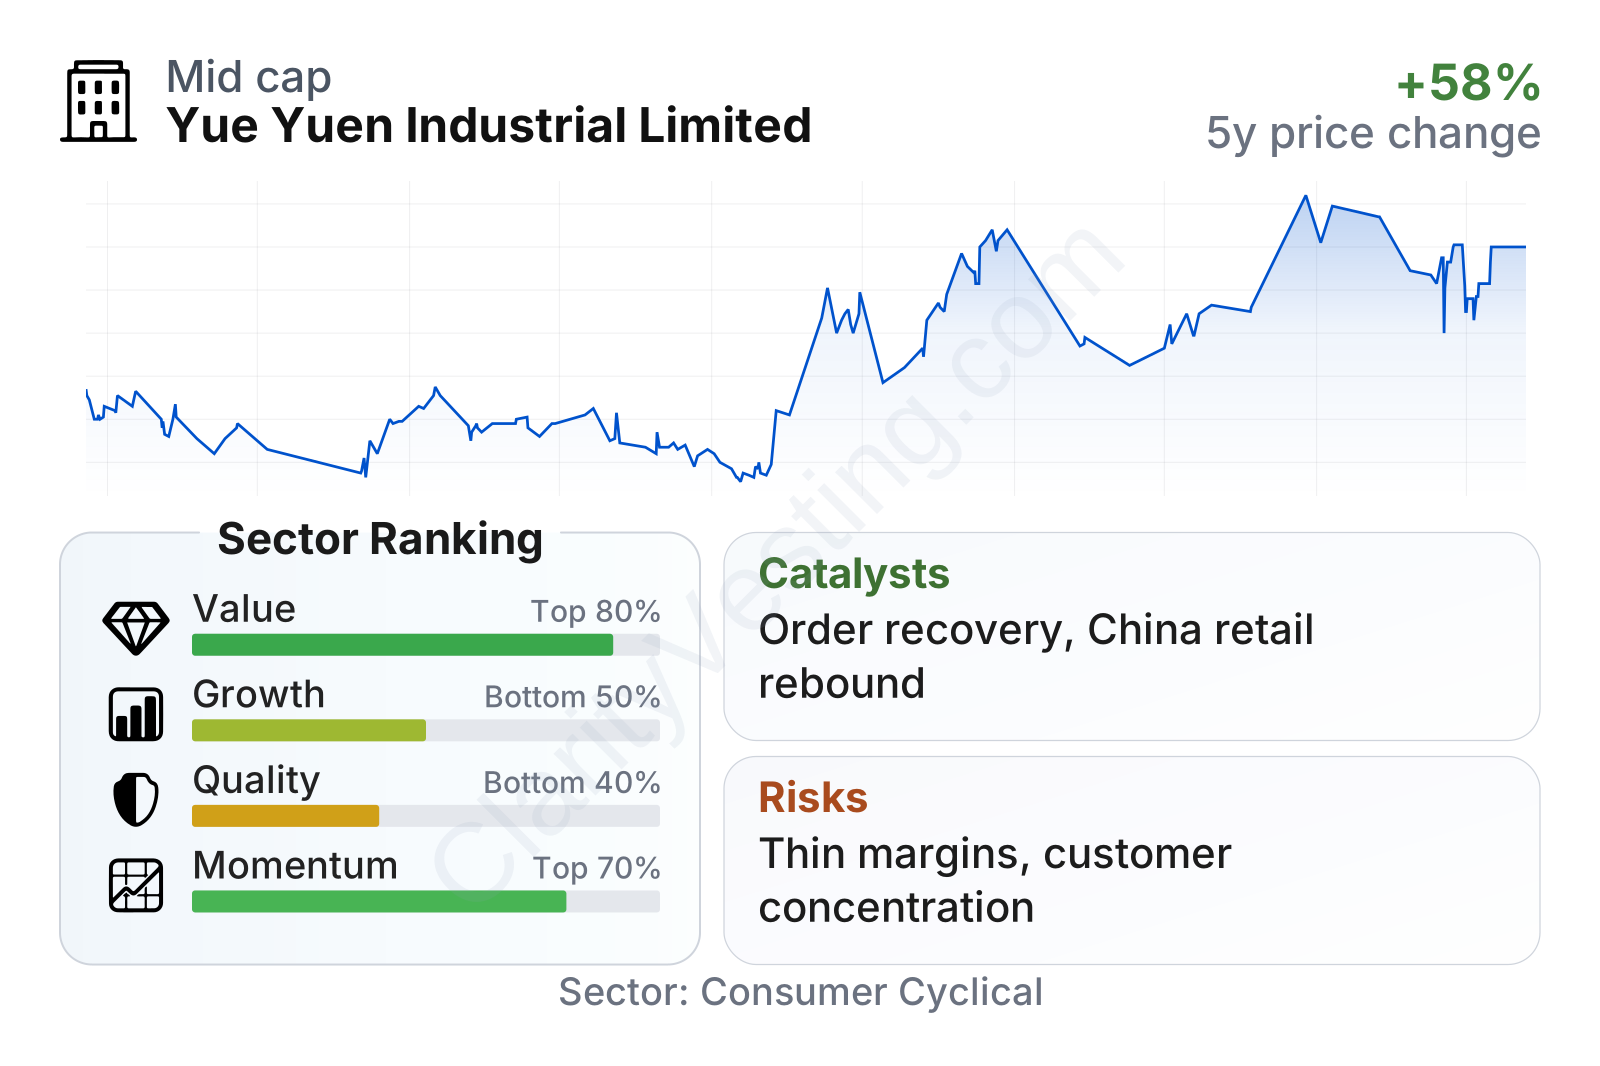
Yue Yuen is a mid-sized company by public market standards, and its recent metrics paint a mixed but interesting picture. On valuation, it screens cheaper than much of the consumer cyclical sector, with a price-to-earnings ratio around 10 and a price-to-book ratio well below the sector median. Free cash flow generation also stands out positively, and the trailing dividend yield is unusually high.
The weaker side is growth and profitability quality. Revenue has recently slipped year over year, long-term sales growth has been modest to negative, and margins remain below the sector median. Still, leverage looks controlled rather than stretched, and price performance over the last three years has been materially better than the broader sector, even after some recent pullback.
Growth
Yue Yuen operates in a sector that still has long-term structural support. Global demand for athletic shoes, outdoor footwear, and sports-inspired casual products continues to benefit from health, fitness, and lifestyle trends. At the same time, large global brands often prefer asset-light models and rely on specialized manufacturing partners instead of owning all production themselves. That outsourcing model supports continued relevance for scaled manufacturers such as Yue Yuen.
The company’s strategy also makes industrial sense. Scale is a real advantage in footwear manufacturing because major brand customers need high-volume output, quality consistency, technical know-how, and multi-country production capacity. Yue Yuen has long-standing relationships with major international sportswear and footwear brands, and that creates switching costs even if it does not eliminate pricing pressure. Its retail operation adds a second growth lever, giving the group direct exposure to sportswear demand in China rather than relying only on factory orders.
Recent sales growth has not been consistently strong, which helps explain why the stock still looks inexpensive on several valuation measures. Revenue has experienced meaningful swings in recent years, reflecting both pandemic-era disruption and later normalization. The more encouraging signal is that free cash flow has improved far more than sales over a five-year period, suggesting that management has been able to extract better cash performance even without strong top-line momentum.
A practical catalyst is any sustained rebound in orders from major footwear brands after inventory corrections across the industry. Another is production reallocation across Asia. Large brand customers increasingly want diversified sourcing beyond a single country, and Yue Yuen’s multi-country manufacturing footprint can make it a useful partner in that shift. On the retail side, a steadier consumer environment in China and better digital execution at Pou Sheng could support better sell-through and inventory turns.
In recent company communications, management has continued to emphasize operational discipline, manufacturing efficiency, and the role of sports retail as a complementary business. That does not create explosive growth on its own, but it does fit the profile of a company trying to improve resilience and cash conversion rather than chasing expansion at any cost.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


