Stock Analysis · Yihai International Holding Ltd (YNNHF)
Overview
Yihai International Holding Ltd is a packaged-food company best known for making soup bases, seasoning compounds, and convenient meal products closely tied to the hot pot and Chinese cuisine market. The business was built around supplying products connected to the Haidilao restaurant ecosystem, but over time it has also expanded into sales to third-party restaurants, retailers, and consumers through supermarkets and e-commerce channels. In practical terms, Yihai sits between branded food manufacturing and foodservice supply.
The company’s revenue mix has historically been concentrated in three main areas, based on its annual reporting structure and business descriptions:
- Hot pot soup flavorings — roughly 45% to 50% of revenue in recent years. This includes soup base products used in hot pot meals, the category most closely associated with the company’s original business.
- Chinese-style compound seasonings — roughly 20% to 30%. This covers seasoning packets and ready-to-use flavoring products for a wider range of dishes beyond hot pot.
- Convenience food products — roughly 20% to 30%. This includes self-heating meals, instant food items, and other ready-to-eat or ready-to-cook products aimed at at-home consumption.
That mix matters because it shows Yihai is no longer only a supplier to one restaurant chain. It is gradually becoming a broader branded food company, with exposure to both foodservice and retail demand. The business is still highly connected to the popularity of hot pot and prepared Chinese meals, but its expansion into convenience foods creates a second growth path if consumer eating habits continue shifting toward packaged meal solutions.
From a profit structure perspective, the company has remained strongly profitable even through uneven growth periods. Revenue has moved within a relatively narrow band over the last five years, but gross profit has stayed solid and operating profitability has remained well above many peers in packaged foods. That suggests the brand, product positioning, and manufacturing model still support healthy economics despite a more competitive environment.
The operating picture over the past few years shows a business with resilient gross profit and good cash conversion, but with some pressure on operating income versus peak levels. In other words, Yihai still earns attractive margins, yet growth has not been smooth enough to fully restore earlier market enthusiasm.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Consumer Defensive | |
| Industry | Packaged Foods | |
| Market Cap ⓘ | $1.50B | |
| Beta ⓘ | 1.01 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 11.07 | 17.88 |
| P/B Ratio ⓘ | 0.33 | 1.29 |
| FCF Yield ⓘ | 95.40% | 12.39% |
| Dividend Yield ⓘ | 57.29% | 2.85% |
| EBIT / EV ⓘ | N/A | 6.43% |
| PEG ⓘ | 2.09 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 14.30% | 4.10% |
| RPS Growth (5Y CAGR) ⓘ | 2.30% | 6.18% |
| EPS Growth (5Y CAGR) ⓘ | -16.71% | -13.59% |
| BVPS Growth (5Y CAGR) ⓘ | 5.14% | 3.20% |
| Margin Growth (5Y Trend) ⓘ | -1.93% | -0.15% |
| FCF Growth (5Y CAGR) ⓘ | 34.61% | 4.10% |
| DPS Growth (5Y CAGR) ⓘ | 27.59% | 6.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 12.34% |
| ROA (Latest) ⓘ | 25.25% | 6.30% |
| ROIC (5Y Median) ⓘ | 18.97% | 10.49% |
| ROA (5Y Median) ⓘ | 14.17% | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | -0.87 | 1.96 |
| Net Debt / EBIT (5Y Median) ⓘ | -1.64 | 2.35 |
| Net Debt / EBITDA (Latest) ⓘ | -0.72 | 1.38 |
| Net Debt / Assets ⓘ | -29.99% | 21.51% |
| EBITDA / Interest ⓘ | N/A | 9.46 |
| Operating Margin (Latest) ⓘ | 16.67% | 8.87% |
| Operating Margin (5Y Median) ⓘ | 18.09% | 9.53% |
| Debt to Equity (Latest) ⓘ | 2.38% | 72.35% |
| Profit Margin (Latest) ⓘ | 13.09% | 5.40% |
| Free Cash Flow (Latest) ⓘ | $1.43B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -13.27% | +20.92% |
| 12M Return (excl. last month) ⓘ | +25.20% | +2.13% |
| 6M Return ⓘ | +5.61% | +1.26% |
| Price vs. 200-Day MA ⓘ | -10.97% | +1.39% |
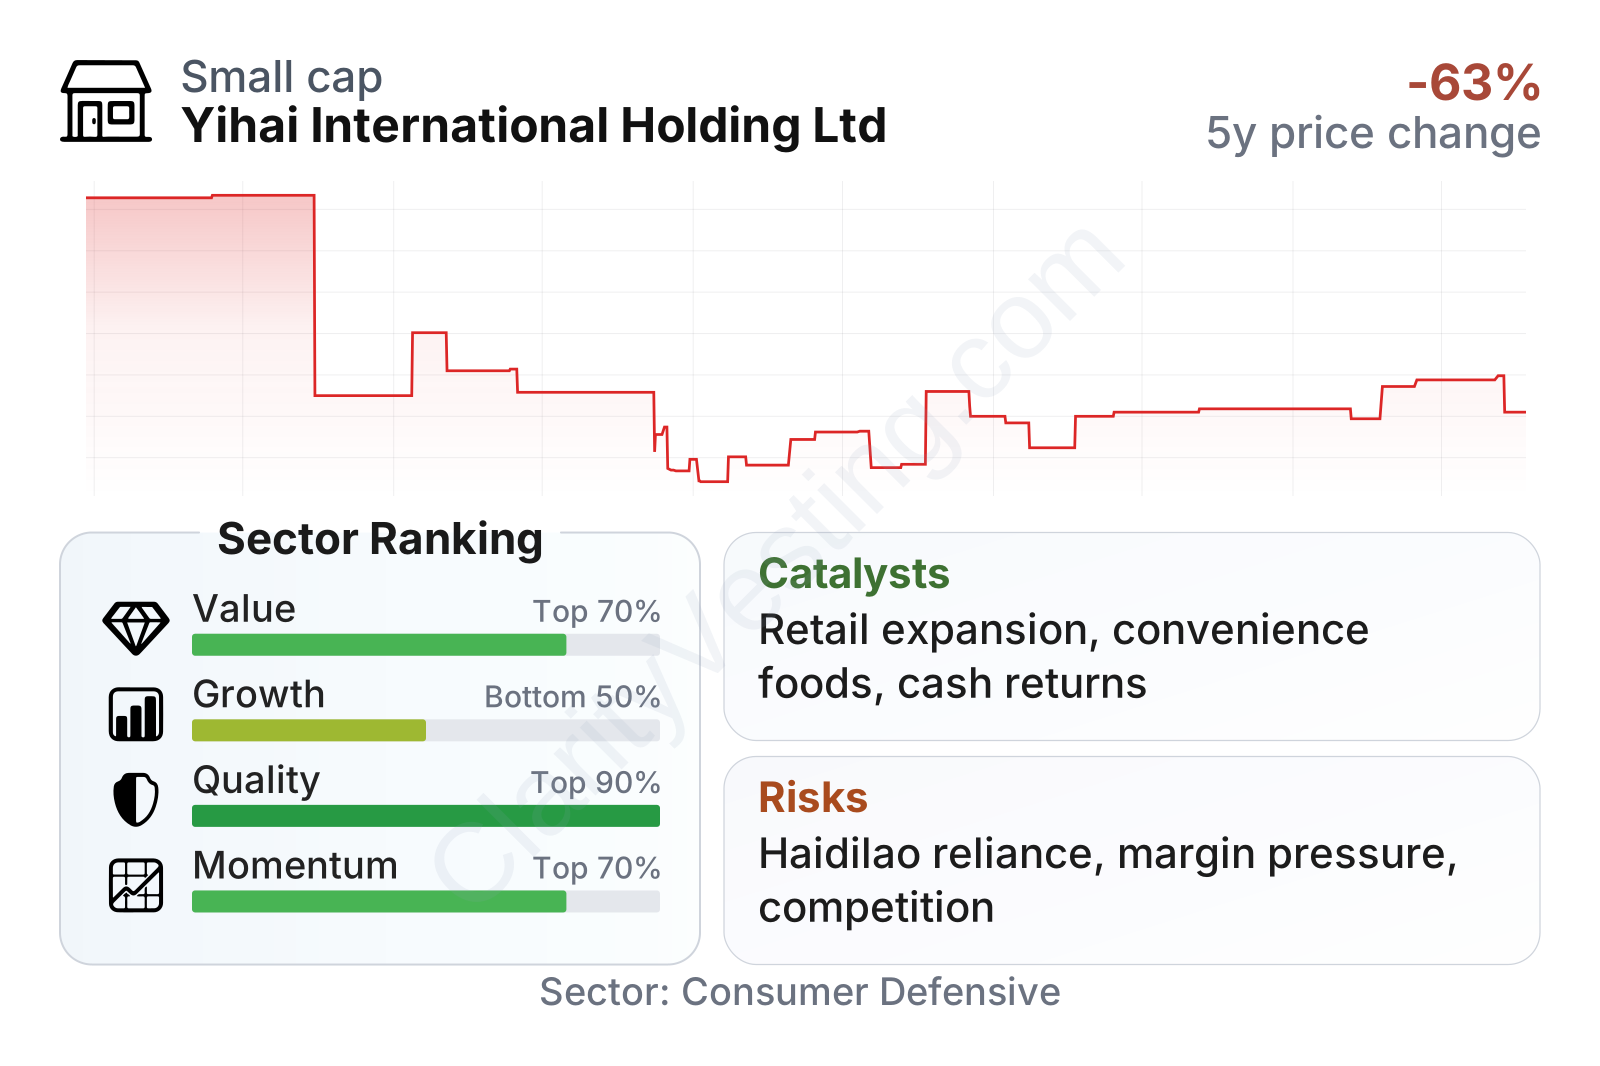
Yihai currently looks unusual in a favorable way on balance sheet strength and profitability. It ranks very high on quality metrics, with returns on assets far above the sector median, operating margins in the mid-teens versus a much lower sector norm, and very limited leverage. Net debt metrics are negative, which points to a net cash position rather than financial strain.
Cash generation is another standout feature. Free cash flow is strong relative to the company’s size, and the free-cash-flow yield and dividend yield screen as exceptionally high. At the same time, the valuation multiples shown here are below sector medians, especially on earnings and book value. That combination usually signals either an overlooked cash-generative business or a market that remains skeptical about the durability of future growth.
Growth metrics are more mixed. Recent year-over-year revenue growth is healthy, but the longer five-year record is less impressive, with weak revenue-per-share expansion and negative earnings compounding over that period. Share price behavior reflects that tension: the stock has recovered from earlier lows and has outperformed the sector over shorter periods, but it still sits well below where it traded several years ago.
Growth
Yihai operates in parts of the food industry that still offer room for expansion. Chinese branded condiments, meal flavorings, and convenience foods benefit from several long-term trends: more at-home consumption, rising demand for standardized prepared ingredients, and growing consumer willingness to pay for recognizable food brands. These are not explosive markets in the way a new technology segment might be, but they can support steady growth for companies that build trusted products and efficient distribution.
The company’s strategy broadly makes sense for that environment. Its original strength came from hot pot soup base products and its relationship with Haidilao, which gave it scale, product credibility, and a built-in sales channel. The next phase has been to widen beyond that foundation by pushing compound seasonings and convenience foods into retail and broader foodservice. That is strategically important because it reduces reliance on one customer ecosystem and gives Yihai more direct access to household spending.
A meaningful catalyst is the company’s ability to monetize its manufacturing and flavor-development capabilities across more categories. If convenience food products continue gaining share, Yihai could benefit from a larger addressable market than restaurant-linked soup bases alone. Another potential support is the company’s financial profile: strong cash generation and a net cash balance can fund product launches, channel expansion, dividends, or efficiency investments without putting pressure on the balance sheet.
Recent operating momentum also gives some support to the growth case. Revenue growth has been running ahead of the broader sector median, showing that the business is still capable of expanding faster than many packaged-food peers even if the longer multi-year trend remains uneven. For a mature food manufacturer, that matters more than headline excitement: it suggests Yihai has not lost relevance in its core categories.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


