Stock Analysis · Yancoal Australia Ltd (YACAF)
Overview
Yancoal Australia Ltd is a large Australian coal producer focused mainly on thermal coal used in power generation, with additional exposure to metallurgical coal used in steelmaking. The company operates a portfolio of mines in New South Wales and Queensland and sells coal into export markets across Asia. Yancoal became one of Australia’s largest coal exporters after expanding through major mine acquisitions, and its scale now matters because coal mining is a business where logistics, port access, reserve life, and production continuity can strongly influence profitability.
Its revenue is overwhelmingly tied to coal sales, but there are still useful distinctions inside that broad category. Based on company reporting in recent annual disclosures, the mix is primarily driven by thermal coal, with metallurgical coal making up a smaller share. Revenue can also be influenced by whether sales come from managed operations or from Yancoal’s share of joint ventures.
- Thermal coal: approximately 80% to 90% of revenue. This includes coal sold to electricity generators, mainly in Asian export markets.
- Metallurgical coal: approximately 10% to 20% of revenue. This includes semi-soft and PCI products used in steelmaking, depending on mine output and coal quality.
- Other revenue: typically a very small share. This can include handling, services, or minor ancillary items rather than a separate major business line.
What makes the business simple to understand is that Yancoal is essentially a volume-and-price company: it produces coal, ships it through established export infrastructure, and its earnings depend heavily on realized coal prices, production levels, costs, and currency movements. Over the last several years, revenue and profit have swung sharply with global coal prices, showing both the earning power of the asset base and the cyclical nature of the industry.
The long-term pattern is clear: earnings surged during the coal price spike in 2022, then normalized as prices came down. Even after that pullback, the business continued to generate solid gross profit and remained cash generative, which is important because it suggests the company’s mines still produce meaningful cash flow outside peak pricing conditions.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Energy | |
| Industry | Thermal Coal | |
| Market Cap ⓘ | $5.53B | |
| Beta ⓘ | -0.57 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 25.75 | 14.47 |
| P/B Ratio ⓘ | 0.62 | 1.70 |
| FCF Yield ⓘ | 28.77% | 8.66% |
| Dividend Yield ⓘ | 4.57% | 3.77% |
| EBIT / EV ⓘ | N/A | 7.46% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 13.00% | 27.35% |
| RPS Growth (5Y CAGR) ⓘ | 2.20% | 6.75% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -15.45% |
| BVPS Growth (5Y CAGR) ⓘ | 10.18% | 5.85% |
| Margin Growth (5Y Trend) ⓘ | -13.20% | 0.75% |
| FCF Growth (5Y CAGR) ⓘ | -24.99% | 3.62% |
| DPS Growth (5Y CAGR) ⓘ | -17.01% | 16.85% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 11.33% |
| ROA (Latest) ⓘ | 10.30% | 6.03% |
| ROIC (5Y Median) ⓘ | 11.71% | 10.16% |
| ROA (5Y Median) ⓘ | 10.30% | 5.34% |
| Net Debt / EBIT (Latest) ⓘ | -1.04 | 1.62 |
| Net Debt / EBIT (5Y Median) ⓘ | -0.88 | 1.91 |
| Net Debt / EBITDA (Latest) ⓘ | -0.57 | 1.06 |
| Net Debt / Assets ⓘ | -16.96% | 17.29% |
| EBITDA / Interest ⓘ | 104.57 | 9.64 |
| Operating Margin (Latest) ⓘ | 15.60% | 16.32% |
| Operating Margin (5Y Median) ⓘ | 25.42% | 19.53% |
| Debt to Equity (Latest) ⓘ | 0.67% | 54.41% |
| Profit Margin (Latest) ⓘ | 4.65% | 8.79% |
| Free Cash Flow (Latest) ⓘ | $1.59B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +84.64% | +62.93% |
| 12M Return (excl. last month) ⓘ | +26.85% | +44.83% |
| 6M Return ⓘ | -22.90% | -1.62% |
| Price vs. 200-Day MA ⓘ | -1.76% | +5.18% |
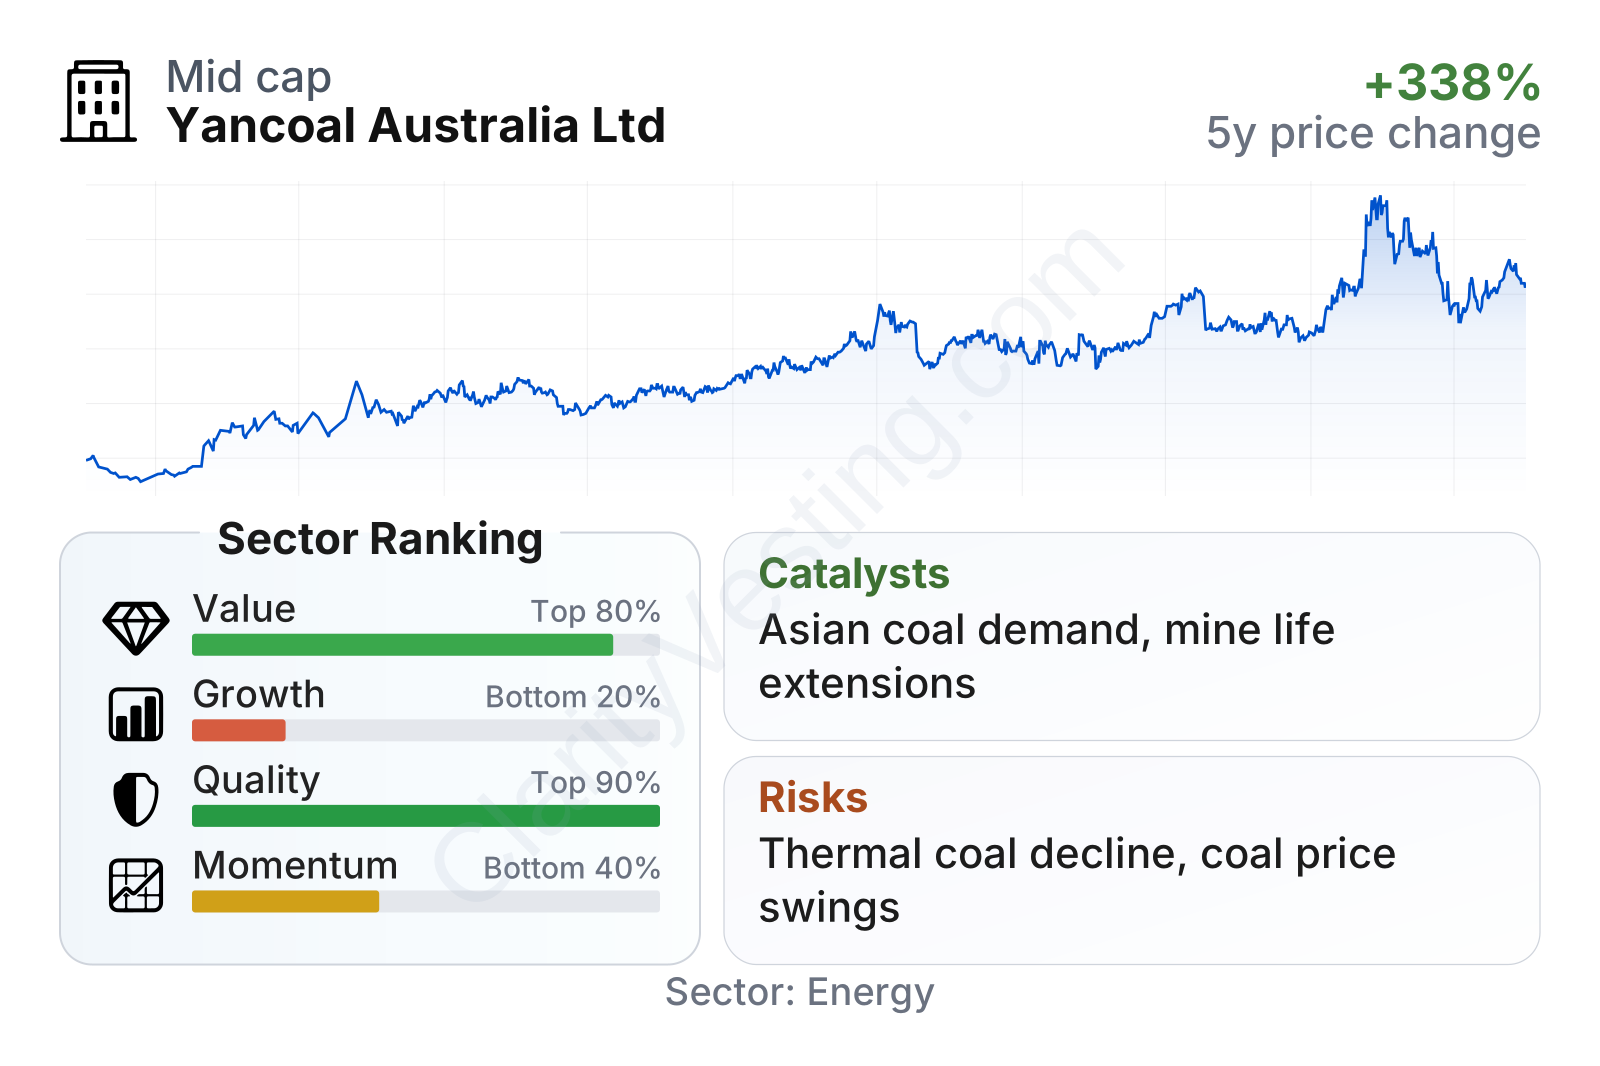
The overall financial profile looks unusual in a good way for a coal miner. On valuation, the shares screen cheaply on book value and strongly on free cash flow yield, while the earnings multiple is higher than the sector median because profits have already fallen from prior peak conditions. On quality, Yancoal stands out with a very strong balance sheet, net cash rather than net debt, extremely low leverage, and interest coverage far above most peers. Growth metrics are weaker, reflecting the fact that recent years have been about normalization after exceptional coal markets rather than steady expansion. Price momentum has also cooled in the shorter term even though the longer-term share performance remains strong.
The share price history also reflects that boom-and-normalization pattern. The stock climbed sharply from late 2021 through parts of 2024 and reached another spike in early 2026, but the retreat afterward shows how quickly sentiment can move when coal prices, demand expectations, or policy concerns change.
Growth
Yancoal operates in a sector with a split outlook. In mature economies, thermal coal faces structural pressure from decarbonization policies, renewable power growth, and tighter financing conditions. That is a real headwind for very long-term demand. However, the picture is more supportive in parts of Asia, where coal still plays a major role in power generation and energy security. For producers with export scale, low costs, and reliable logistics, this can still translate into meaningful cash flow for years, even if the sector is not a classic growth industry.
Yancoal’s strategy is more about disciplined cash generation than aggressive expansion. That approach makes sense in coal. Building major new thermal coal capacity is increasingly difficult, so value often comes from operating existing mines efficiently, extending mine lives where permitted, optimizing product mix, and returning surplus cash while preserving balance sheet strength. Recent financial characteristics support that view: the company has maintained strong free cash flow and a net cash position even after coal prices fell from extraordinary highs.
One practical catalyst is operational leverage to coal prices. If benchmark prices strengthen because of weather disruptions, supply issues, or stronger Asian demand, Yancoal’s earnings can recover quickly because its production base is already in place. Another catalyst is reserve life and mine planning: approvals, extensions, or better-than-expected production from key operations can support output visibility. The company has also highlighted ongoing mine development and optimization work across its asset base in annual reporting, which matters more here than headline acquisitions.
There is also a broader supply-side argument supporting established producers. Global pressure on new coal investment can tighten future supply. That does not guarantee higher prices, but it can help incumbents with existing reserves, rail access, port capacity, and customer relationships. In that setting, Yancoal’s scale in Australia is strategically meaningful.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


