Stock Analysis · Exzeo Group Inc (XZO)
Overview
Exzeo Group Inc operates in financial services and is classified in the diversified insurance industry. Based on its recent financial profile, the company appears to be a relatively small public company by sector standards, but one that has gone through a sharp change in scale over the last few years. Revenue and earnings expanded quickly from 2023 through 2025, and profitability improved from losses in 2022 to strong reported profits by 2025.
The available public financial information shows a business that is generating revenue primarily from its operating activities within insurance and related financial services, but the exact breakdown by product line is not clearly disclosed in the material used here. Because of that, a precise split by segment or product cannot be presented reliably. What can be said with confidence is that the company’s reported revenue base has increased materially, while operating expenses as a share of revenue have fallen, which points to either better underwriting, improved pricing, operating leverage, or a business mix shift toward higher-margin activities.
- Total revenue rose from about $46 million in 2022 to about $217 million in 2025.
- Reported net income moved from a loss of about $55 million in 2022 to a profit of about $83 million in 2025.
- Operating income improved from deeply negative in 2022 to more than $110 million in 2025.
That transition is important for long-term analysis because it suggests Exzeo is no longer being valued only as a turnaround possibility. It is increasingly being judged on whether these stronger margins and profits can persist.
The multi-year progression is striking: revenue has expanded quickly, but profit has risen even faster. That usually signals a business that has recently gained scale or improved efficiency. It also means future results will be watched closely, because once margins reach unusually high levels, the market tends to test whether they are durable.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Financial Services | |
| Industry | Insurance - Diversified | |
| Market Cap ⓘ | $1.43B | |
| Beta ⓘ | N/A | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 16.49 | 12.26 |
| P/B Ratio ⓘ | 5.27 | 1.23 |
| FCF Yield ⓘ | 5.72% | 10.40% |
| Dividend Yield ⓘ | N/A | 3.02% |
| EBIT / EV ⓘ | 8.55% | 8.14% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 6.90% | 9.35% |
| RPS Growth (5Y CAGR) ⓘ | 33.19% | 12.19% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -9.53% |
| BVPS Growth (5Y CAGR) ⓘ | 56.95% | 4.99% |
| Margin Growth (5Y Trend) ⓘ | 67.64% | -3.86% |
| FCF Growth (5Y CAGR) ⓘ | 27.53% | 4.81% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 8.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 38.77% | 9.49% |
| ROE (Latest) ⓘ | 47.36% | 13.90% |
| ROA (Latest) ⓘ | 30.56% | 1.55% |
| ROIC (5Y Median) ⓘ | N/A | 7.86% |
| ROE (5Y Median) ⓘ | 31.24% | 12.17% |
| ROA (5Y Median) ⓘ | 5.28% | 1.30% |
| Net Debt / EBIT (Latest) ⓘ | -1.12 | 0.96 |
| Net Debt / EBIT (5Y Median) ⓘ | -1.21 | 0.73 |
| Net Debt / EBITDA (Latest) ⓘ | -1.09 | 0.92 |
| Operating Margin (Latest) ⓘ | 52.40% | 22.30% |
| Operating Margin (5Y Median) ⓘ | 2.89% | 24.63% |
| Debt to Equity (Latest) ⓘ | 2.30% | 58.56% |
| Profit Margin (Latest) ⓘ | 37.68% | 26.57% |
| Free Cash Flow (Latest) ⓘ | $81.53M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | N/A | +88.33% |
| 12M Return (excl. last month) ⓘ | N/A | +19.38% |
| 6M Return ⓘ | -0.60% | +4.75% |
| Price vs. 200-Day MA ⓘ | +2.46% | +3.50% |
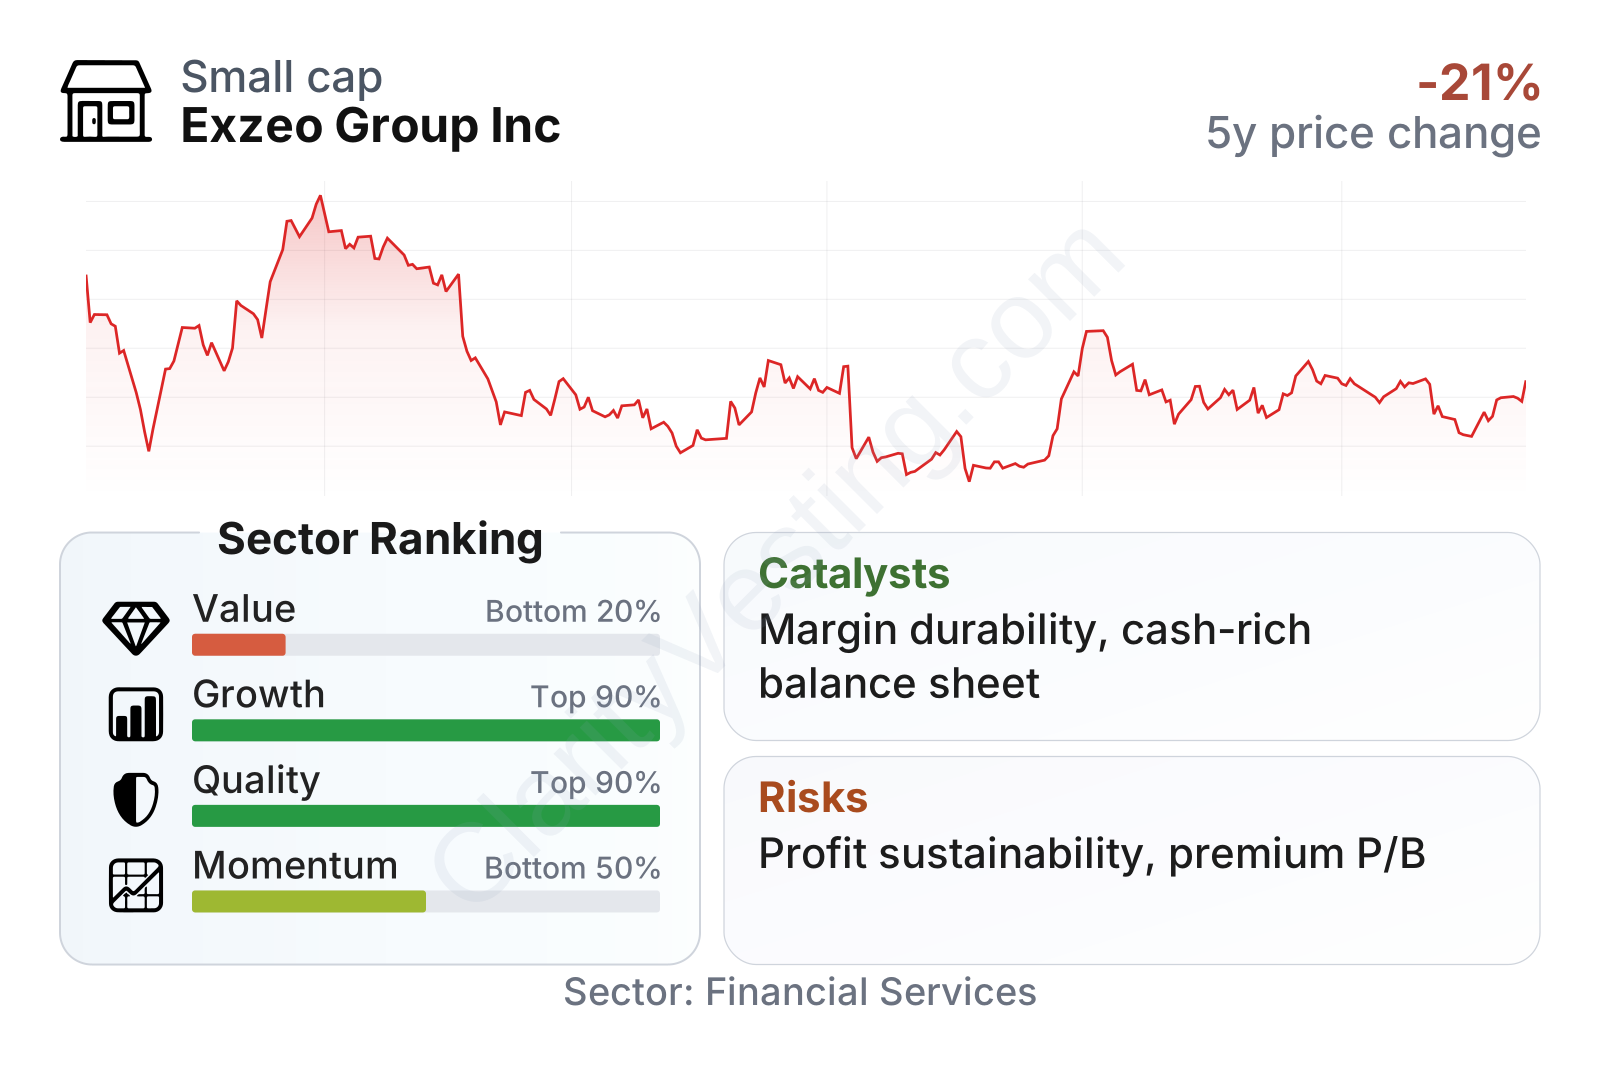
Exzeo stands out more for quality and long-term growth than for cheapness or share-price momentum. Profitability measures are far above the sector median, balance-sheet leverage is very low, and free cash flow is positive. At the same time, valuation multiples are not low for an insurance-related company, especially on book value, and the stock’s recent trading trend has been weaker than much of the sector.
The recent share-price path also shows that the market has become more cautious after a strong operational improvement. A decline from late 2025 into mid-2026, followed by a partial rebound, usually reflects a market trying to decide whether the earnings step-up is sustainable or whether the earlier enthusiasm ran ahead of fundamentals.
Growth
Exzeo is operating in a broad financial services area that can grow over time, but it is not automatically a high-growth industry in the way software or semiconductors can be. That makes company-specific execution especially important. In Exzeo’s case, the growth case rests less on sector tailwinds alone and more on the company’s ability to keep scaling revenue while protecting margins and capital efficiency.
On that front, the recent record is notable. Revenue growth over the last year was positive, though below the sector median, but the longer-term picture is much stronger. Revenue per share has compounded at a far faster pace than the typical company in the sector over five years. Free cash flow growth has also been strong, and book value per share has risen rapidly over the same period, even if the path has been uneven.
The earnings profile suggests that Exzeo has moved into a more profitable phase. Reported earnings per share reached close to $1.00 for full-year 2025, and the mid-2026 figure indicates the company remained profitable. For a long-term reader, the key issue is not simply that earnings exist now, but that they have emerged after a period of losses and improved at a pace that materially changed how the business looks.
Book value per share has been volatile, which is common in financial businesses going through restructuring, capital changes, or sharp profitability swings. Still, the longer-term direction is favorable, and the five-year compound growth rate is far ahead of the sector median. In a financial company, book value matters because it represents part of the capital base that supports operations and often anchors valuation over time.
A practical growth catalyst is the company’s ability to convert scale into cash generation. With free cash flow now positive and operating margins well above sector norms, Exzeo has more room than before to reinvest, pursue product expansion, strengthen distribution, or preserve balance-sheet flexibility. The biggest opportunity from recent performance is straightforward: if the company can show that 2025 was not a one-off peak, the business could be viewed less as a small-cap turnaround and more as a structurally more profitable insurer or financial platform.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


