Stock Analysis · Dentsply Sirona Inc (XRAY)
Overview
Dentsply Sirona is a dental equipment and dental consumables company. It sells products used by dentists, specialists, and dental laboratories, including imaging systems, treatment centers, digital scanners, clear aligners, implants, endodontic tools, preventive products, and restorative materials. In simple terms, it is a broad dental supplier: some products are large machines used in clinics, while others are recurring items used every day in patient care.
The company operates globally and its business mix is usually split between equipment and consumables. Based on recent annual reporting, revenue is broadly concentrated in the following categories:
- Connected Technology Solutions: about 36% of revenue. This includes digital imaging, treatment centers, CAD/CAM systems, software, and other technology-heavy equipment used in dental offices.
- Essential Dental Solutions: about 34% of revenue. This includes everyday dental supplies such as restorative materials, infection prevention products, and endodontic and preventive care items.
- Orthodontic and Implant Solutions: about 30% of revenue. This includes clear aligners, implant systems, and related specialist products.
That mix matters because equipment sales can be more cyclical and sensitive to clinic spending, while consumables are usually steadier because they are used continuously in routine treatment. Over the last several years, the company’s revenue base has gradually compressed, while expenses and non-cash charges have weighed heavily on reported profit. Even so, the business still produces meaningful gross profit, showing that the issue has been less about lack of demand for all products and more about execution, costs, and profitability.
The long-term pattern shows a business that still generates a large amount of gross profit, but too much of that has been absorbed by operating costs and impairment-related pressure, leaving reported earnings weak or negative in recent years.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Medical Instruments & Supplies | |
| Market Cap ⓘ | $1.68B | |
| Beta ⓘ | 0.88 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 24.79 |
| P/B Ratio ⓘ | 1.31 | 3.08 |
| FCF Yield ⓘ | 8.50% | 3.15% |
| Dividend Yield ⓘ | 3.76% | 1.94% |
| EBIT / EV ⓘ | -6.36% | 0.57% |
| PEG ⓘ | 0.63 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -4.10% | 7.45% |
| RPS Growth (5Y CAGR) ⓘ | -1.00% | 8.61% |
| EPS Growth (5Y CAGR) ⓘ | -22.76% | -17.81% |
| BVPS Growth (5Y CAGR) ⓘ | -26.24% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | N/A | -0.62% |
| FCF Growth (5Y CAGR) ⓘ | -32.96% | 1.04% |
| DPS Growth (5Y CAGR) ⓘ | 11.33% | 6.77% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -6.16% | 3.24% |
| ROA (Latest) ⓘ | -10.06% | 3.01% |
| ROIC (5Y Median) ⓘ | -8.02% | 4.60% |
| ROA (5Y Median) ⓘ | -10.70% | 1.89% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.84 |
| Net Debt / EBITDA (Latest) ⓘ | 22.29 | 1.00 |
| Net Debt / Assets ⓘ | 39.83% | 5.45% |
| EBITDA / Interest ⓘ | 1.02 | 9.64 |
| Operating Margin (Latest) ⓘ | -7.03% | 9.27% |
| Operating Margin (5Y Median) ⓘ | -10.82% | 7.38% |
| Debt to Equity (Latest) ⓘ | 171.13% | 28.58% |
| Profit Margin (Latest) ⓘ | -14.99% | 3.59% |
| Free Cash Flow (Latest) ⓘ | $143.00M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -69.61% | +42.80% |
| 12M Return (excl. last month) ⓘ | -25.39% | +18.50% |
| 6M Return ⓘ | -26.72% | +7.57% |
| Price vs. 200-Day MA ⓘ | -23.14% | +5.12% |
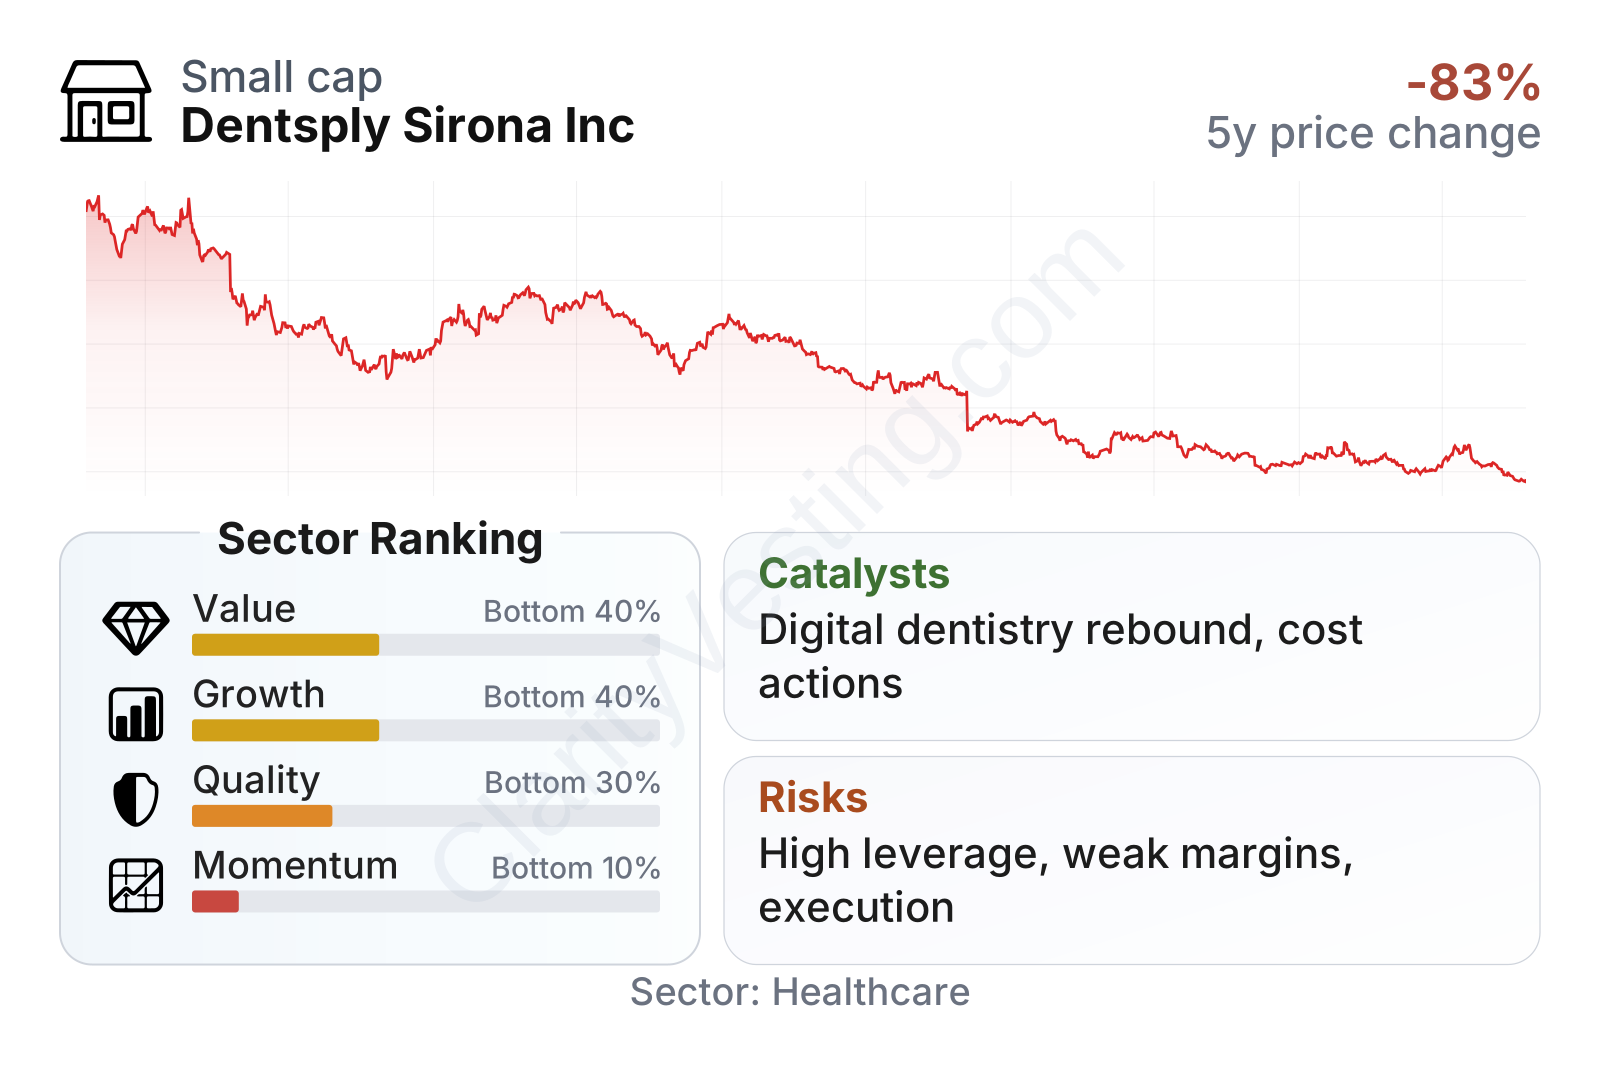
Dentsply Sirona currently sits in the lower end of the healthcare sector on value, growth, and quality measures, and in the bottom tier on momentum. The valuation picture looks optically inexpensive on asset value, cash flow yield, and dividend yield, but those cheaper-looking metrics come alongside weak profitability, negative returns on capital, and a multiyear decline in business performance. In other words, the low multiples reflect real operating strain rather than a business showing broad financial strength.
Growth
Dental care is still an attractive long-term market. Demand is supported by aging populations, rising awareness of oral health, growing interest in cosmetic dentistry, and the gradual shift toward digital workflows in clinics. Over time, practices are expected to keep adopting scanners, imaging systems, chairside software, and other tools that can improve efficiency and patient experience. That gives companies like Dentsply Sirona exposure to a sector with durable underlying demand.
Where the picture becomes more difficult is at the company level. Its strategy makes sense on paper: combine recurring consumables with higher-value digital equipment and specialist products, then use a global sales footprint to cross-sell across the dental office. The challenge is that recent execution has not translated into sustained expansion. Revenue growth has been inconsistent and often negative, which is not what long-term shareholders usually want to see from a company exposed to digital dentistry and orthodontics.
The recent revenue pattern points to a company that has struggled to convert industry tailwinds into steady top-line progress. There have been short periods of stabilization, but the broader trend remains choppy, and recent year-over-year comparisons have stayed below the healthcare sector median.
Cash generation adds an important nuance. Even with weak reported earnings, Dentsply Sirona has continued to produce positive free cash flow. That is a useful support point because it shows the business is not purely dependent on accounting profits to fund itself.
Still, free cash flow has moved down sharply from earlier levels, so this cushion has become thinner. For future growth to look more convincing, the company likely needs not just stable cash generation, but also cleaner execution in its core dental categories and a clearer rebound in organic sales.
One of the more visible catalysts is the continued digitization of dental practices. If clinics resume equipment upgrades more actively, Dentsply Sirona has a broad installed base and a recognized product portfolio that could benefit. Another possible opportunity comes from simplification efforts and cost actions, which could improve margins if management executes well. Recent company updates have also emphasized portfolio focus, operational improvements, and leadership actions aimed at restoring consistency.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


