Stock Analysis · XP Power Limited (XPPLF)
Overview
XP Power Limited is a power-control components company that designs and manufactures power converters, high-voltage power supplies, and related solutions used inside other equipment. In simple terms, its products help machines receive the right type of electrical power safely and reliably. The company mainly serves industrial, healthcare, and semiconductor equipment customers, where power performance and long product life matter more than selling low-cost commodity parts.
The business is built around selling engineered power products directly to equipment manufacturers, often for demanding applications such as medical devices, factory automation systems, analytical instruments, and semiconductor tools. That gives XP Power exposure to customers that usually require product qualification, regulatory compliance, and ongoing technical support.
Based on recent annual reporting, revenue is primarily split by end market rather than by a large number of unrelated activities. The main sources of revenue are approximately:
- Industrial technology: about 45% to 50% of revenue. This includes factory automation, test and measurement, robotics, and a broad range of industrial equipment.
- Semiconductor manufacturing equipment: about 25% to 30% of revenue. This covers power solutions used in wafer fabrication and related chip-production tools, including high-voltage applications.
- Healthcare: about 20% to 25% of revenue. This includes medical and diagnostic equipment where reliability, approvals, and product consistency are important.
- Other smaller activities: a limited remainder, generally linked to adjacent electronics and niche applications.
Geographically, XP Power has historically sold across Asia, Europe, and North America, with Asia often representing the largest exposure because of semiconductor and electronics manufacturing activity. Its model combines internal manufacturing with engineering and customer-facing sales support, which is important in markets where customers often design a power solution into equipment for several years.
Over the last few years, the company’s revenue rose from roughly $240 million in 2021 to more than $316 million in 2023, before dropping back to about $247 million in 2024 and about $230 million in 2025. That pattern shows a business tied to industrial and semiconductor demand cycles rather than a straight-line growth profile.
The profit structure also changed sharply. Gross profit remained meaningful, but operating income fell from roughly $30 million in 2021 to nearly break-even in 2025, while interest expense stayed elevated. In practice, that means XP Power still generates substantial sales and gross profit, but much less of that is reaching the bottom line than it did a few years ago.
The operating picture suggests a company that still has a solid product base and customer demand, but where margin pressure, lower volumes, and financing costs have reduced earnings power.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Electrical Equipment & Parts | |
| Market Cap ⓘ | $1.27B | |
| Beta ⓘ | 1.74 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 22.10 |
| P/B Ratio ⓘ | 4.32 | 1.97 |
| FCF Yield ⓘ | 3.90% | 6.38% |
| Dividend Yield ⓘ | N/A | 1.94% |
| EBIT / EV ⓘ | N/A | 4.79% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -1.60% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | -8.50% | 7.81% |
| EPS Growth (5Y CAGR) ⓘ | -36.86% | -13.06% |
| BVPS Growth (5Y CAGR) ⓘ | -7.49% | 6.14% |
| Margin Growth (5Y Trend) ⓘ | -12.06% | 0.88% |
| FCF Growth (5Y CAGR) ⓘ | 22.26% | 11.01% |
| DPS Growth (5Y CAGR) ⓘ | -60.25% | 9.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 10.84% |
| ROA (Latest) ⓘ | -5.27% | 5.41% |
| ROIC (5Y Median) ⓘ | 0.88% | 9.38% |
| ROA (5Y Median) ⓘ | -2.23% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | 29.39 | 2.08 |
| Net Debt / EBIT (5Y Median) ⓘ | 28.17 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 2.46 | 1.39 |
| Net Debt / Assets ⓘ | 23.97% | 19.28% |
| EBITDA / Interest ⓘ | 2.25 | 9.58 |
| Operating Margin (Latest) ⓘ | 0.75% | 10.50% |
| Operating Margin (5Y Median) ⓘ | 2.14% | 10.29% |
| Debt to Equity (Latest) ⓘ | 66.55% | 65.48% |
| Profit Margin (Latest) ⓘ | -3.72% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $49.49M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +114.23% | +61.68% |
| 12M Return (excl. last month) ⓘ | +127.44% | +12.58% |
| 6M Return ⓘ | +63.91% | 0.00% |
| Price vs. 200-Day MA ⓘ | +32.02% | +0.02% |
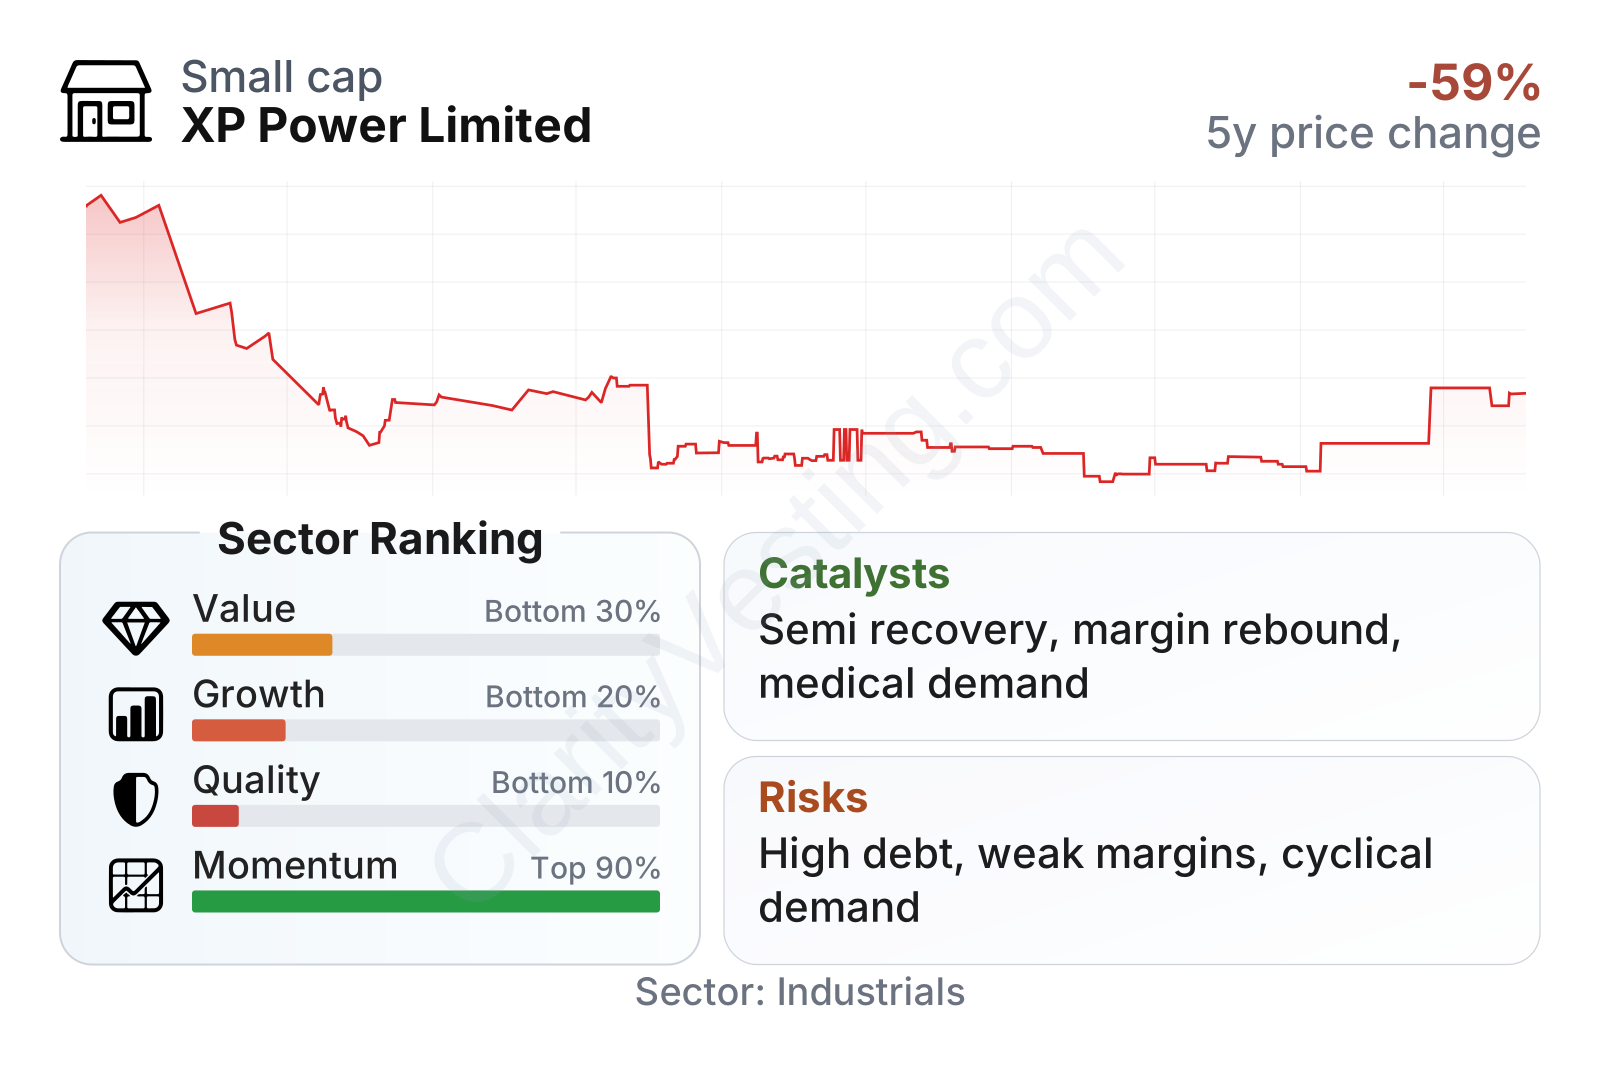
XP Power is a mid-sized industrial electronics company with a stock that has been very volatile. After a deep decline from 2021 levels, the shares rebounded strongly over the last 6 to 12 months, which signals improving market confidence but also a higher sensitivity to changing expectations. The beta above 1.8 points to a share price that tends to move more sharply than the broader market.
The table points to a mixed profile. Valuation metrics are not especially cheap relative to the company’s current fundamentals, even though the earnings multiple sits below the sector median. That lower P/E needs to be read carefully because present earnings quality is weak. Free cash flow is positive, which is an important stabilizing element, but the cash flow yield is still below the sector median.
On growth, the company ranks near the bottom of its sector. Recent revenue has been slightly negative year over year, and the longer five-year record shows declines in revenue per share, earnings per share, and book value per share. The main bright spot is free cash flow, which has improved over a multi-year period despite weak accounting earnings.
Quality is the weakest area. Operating margin is around 1%, far below the sector median near 10%. Profit margin is negative, returns on assets are negative, and leverage is stretched. Net debt to EBITDA is roughly 2.9x, while EBITDA covers interest by less than 2x, which leaves limited room for operational setbacks.
Growth
XP Power operates in segments that should remain relevant over the long term. Industrial automation, medical technology, and semiconductor equipment all depend on increasingly specialized power systems. As machinery becomes more precise and electronics content rises, power conversion tends to become more critical rather than less. That gives the company exposure to structurally attractive demand areas, even if short-term orders can swing sharply.
The strategy itself is understandable. XP Power focuses on applications where technical requirements, certifications, and reliability matter. In these niches, customers are less likely to switch suppliers casually because redesigns can be costly and time-consuming. The company has also expanded in high-voltage and semiconductor-related products, areas that can carry better technical differentiation than standard power supplies.
A major future growth catalyst is a recovery in semiconductor equipment spending. If wafer-fab customers move from inventory digestion back to broader capital spending, XP Power could benefit because this end market is one of its larger and more specialized businesses. Another catalyst is margin normalization: if revenue stabilizes while manufacturing utilization improves and financing pressure eases, earnings could recover faster than sales.
There is also a potential longer-term opportunity from medical and industrial electrification trends. More connected devices, automation equipment, and advanced diagnostic systems usually require compact, efficient, and tightly regulated power solutions. That is a favorable backdrop for a company with engineering depth and a direct relationship model.
Recent trading momentum suggests the market has started to price in some recovery. The stock has materially outperformed the sector over the last 6 months and over the last 12 months excluding the latest month. That does not prove a turnaround is complete, but it does indicate that expectations have improved noticeably.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


