Stock Analysis · XD Inc (XDNCF)
Overview
XD Inc is a China-based digital entertainment company best known for publishing and developing mobile and online games, while also operating the TapTap game community and distribution platform. In simple terms, the business sits at the intersection of game creation, game publishing, and player engagement. That mix matters because it gives the company more than one way to reach users: it can earn money from its own titles, from publishing third-party games, and from traffic and services tied to its platform ecosystem.
The company’s revenue has historically come from two main operating lines: games and platform-related services. Based on recent annual reporting, mobile games remain the largest contributor, while TapTap and other value-added online services have become increasingly important as the platform expands its user base and advertising or service potential.
Main revenue sources can be summarized as follows:
- Online games: approximately 75% to 85% of revenue in recent years. This includes self-developed games and published games, mainly generated through in-game purchases and related player spending.
- Premium game publishing / information services / platform-related and other services: approximately 15% to 25% of revenue in recent years. This includes TapTap-related services, game distribution support, advertising, and other digital content or platform monetization activities.
The business model has become more attractive as profitability improved. Revenue rose strongly from about RMB 2.7 billion in 2021 to more than RMB 5.6 billion in 2025, while the company moved from operating losses to sizable operating profit. Another notable point is cost discipline: research and development remains large in absolute terms, but it now consumes a much smaller share of revenue than it did a few years ago, which has helped margins expand.
The operating profile has changed meaningfully over the last five years. Revenue has scaled, gross profit has widened, and operating income has shifted from deep losses to strong profitability. Interest expense has also dropped sharply, showing that earnings improvement is not only coming from sales growth but also from a cleaner financial structure.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Communication Services | |
| Industry | Electronic Gaming & Multimedia | |
| Market Cap ⓘ | $1.28B | |
| Beta ⓘ | 1.77 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 270.00 | 17.77 |
| FCF Yield ⓘ | 215.73% | 14.45% |
| Dividend Yield ⓘ | N/A | 2.73% |
| EBIT / EV ⓘ | N/A | 4.63% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 7.50% | 5.50% |
| RPS Growth (5Y CAGR) ⓘ | 19.02% | 4.55% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -17.45% |
| Margin Growth (5Y Trend) ⓘ | 65.20% | 0.81% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 5.63% |
| DPS Growth (5Y CAGR) ⓘ | 20.74% | 5.09% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 8.51% |
| ROIC (5Y Median) ⓘ | -4.77% | 8.16% |
| Net Debt / EBIT (Latest) ⓘ | -1.30 | 2.00 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 2.83 |
| Net Debt / EBITDA (Latest) ⓘ | -1.23 | 1.22 |
| Net Debt / Assets ⓘ | -66.36% | 18.70% |
| EBITDA / Interest ⓘ | N/A | 8.31 |
| Operating Margin (Latest) ⓘ | 26.80% | 15.53% |
| Operating Margin (5Y Median) ⓘ | 2.48% | 13.39% |
| Debt to Equity (Latest) ⓘ | 2.80% | 59.59% |
| Profit Margin (Latest) ⓘ | 24.94% | 8.77% |
| Free Cash Flow (Latest) ⓘ | $2.76B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +26.82% | +48.95% |
| 12M Return (excl. last month) ⓘ | 0.00% | +1.03% |
| 6M Return ⓘ | 0.00% | +0.56% |
| Price vs. 200-Day MA ⓘ | 0.00% | +1.63% |
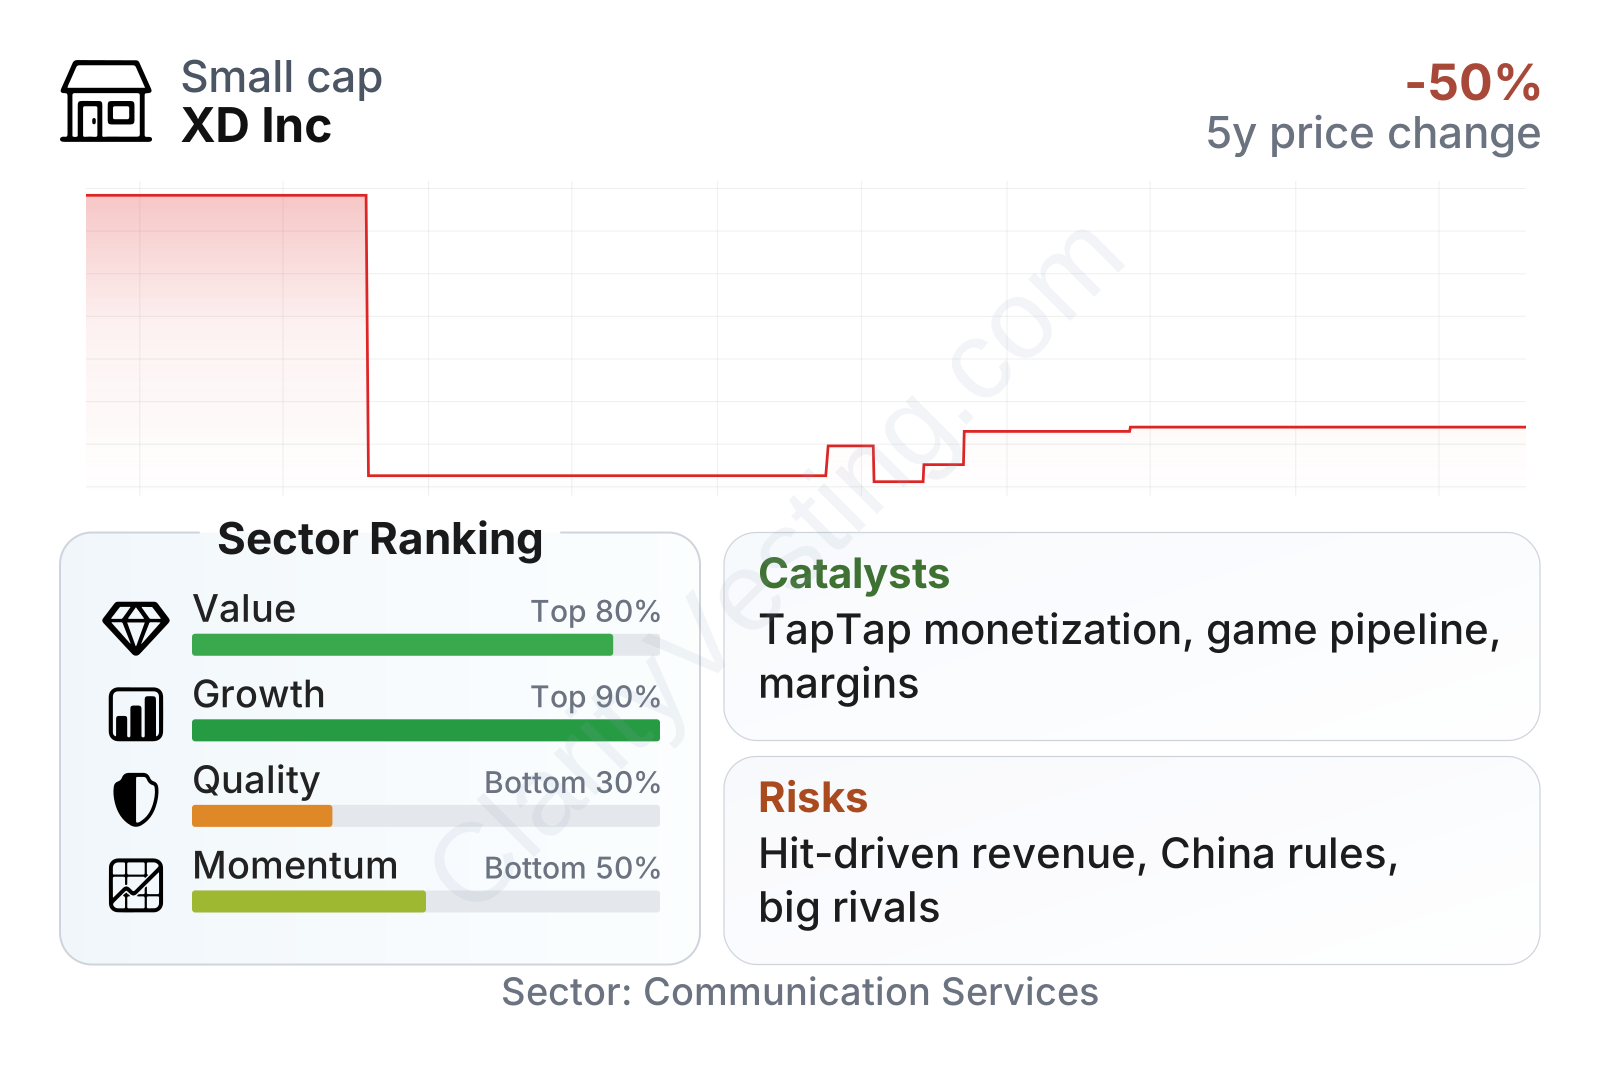
XD Inc is a small-cap company with a market value around the low-billion-dollar range, and the stock has been volatile, with a beta well above 1. The share price history shows a major reset from 2021 to 2023 and then a long period of stabilization, which helps explain why momentum indicators look only average to weak despite much better operating results.
The latest metrics paint a mixed but interesting picture. Growth ranks near the top of the sector, supported by revenue expansion above the sector median, very strong five-year revenue-per-share growth, and a major improvement in operating margins. Profitability is also stronger than many peers on a current basis, with operating and net margins clearly above sector medians.
At the same time, valuation looks demanding on earnings, with a very high P/E ratio compared with the sector median. That said, cash generation appears much stronger than the headline earnings multiple suggests, and the balance sheet looks conservative: debt is low, and net cash metrics are better than many peers. In short, the company combines strong recent execution with a valuation that still requires confidence that the current earnings level is sustainable.
Growth
XD Inc operates in a sector that still has long-term room to grow. Mobile gaming remains one of the largest segments of global digital entertainment, and game discovery platforms are becoming more valuable as competition for user attention rises. In that environment, a company that both develops content and controls an engaged distribution community can build a stronger position than a pure game studio.
The strategy appears logical for future growth. First, the company keeps investing heavily in research and development, which is essential in gaming because fresh content drives user spending. Second, TapTap gives XD a direct relationship with players, which can lower dependence on outside app-store traffic and improve user acquisition efficiency over time. Third, the combination of owned intellectual property, publishing capability, and platform traffic can create a reinforcing loop: successful games attract users, and users make the platform more useful for future launches.
A visible catalyst is the company’s sharp turnaround in profitability. The move from losses in 2021-2023 to strong operating and net income in 2024-2025 suggests that earlier investments are now producing returns. Revenue growth has also continued even after that profitability inflection, which is generally a healthier sign than a turnaround driven only by cost cuts.
Another growth support is financial flexibility. The business appears to have net cash rather than net debt, very low leverage relative to equity, and strong free cash flow. That gives management more room to fund game development, marketing, platform features, and potentially selective partnerships without immediate pressure from lenders.
Recent company communications and public disclosures have continued to emphasize game pipeline development and TapTap ecosystem expansion. For a business like XD, the next major title launch, stronger monetization on TapTap, or deeper user engagement on the platform could materially affect results because successful releases in gaming often have an outsized financial impact.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


