Stock Analysis · Select Energy Services Inc (WTTR)
Overview
Select Energy Services is a U.S. oilfield services company focused on water management and chemical solutions for onshore oil and gas producers. In simple terms, it helps energy companies source, move, treat, recycle, and dispose of the large volumes of water used in hydraulic fracturing and production. It also sells chemicals used in completion and production work, and it provides related wellsite and logistics services.
The business is tied mainly to activity in major shale basins, especially the Permian. That makes Select less of a direct bet on oil prices alone and more of a bet on drilling, completion activity, produced-water handling needs, and the industry's increasing focus on recycling water instead of relying only on fresh water and disposal wells.
Based on the company’s recent annual reporting, revenue is concentrated in three operating segments.
- Water Services: about 64% of revenue. This is the core business and includes water sourcing, transfer, flowback, containment, monitoring, recycling, disposal, and other water-related field services.
- Chemicals: about 22% of revenue. This segment supplies completion, production, and water-treatment chemicals used by exploration and production customers.
- Wellsite Services: about 14% of revenue. This includes accommodations, rental equipment, solids control, surface rental equipment, and other site support services.
The mix matters because water handling is increasingly necessary throughout the life of a shale well, not only at the initial fracking stage. That gives Select a business model with some recurring operational demand, although results still move with the broader U.S. land drilling cycle.
Over the last several years, the company’s revenue base expanded sharply from the post-downturn period, but profit conversion has stayed modest. Gross profit improved meaningfully after 2021, yet a large share of that gross profit continues to be absorbed by operating costs, which helps explain why net earnings and cash generation have been less consistent than revenue alone might suggest.
The long-term picture shows a much larger business than in 2021, but one where stronger scale has not fully translated into durable margin expansion. That is the central theme to watch with Select: a useful niche position in water and chemicals, but still a business working to turn activity levels into stronger cash returns.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Energy | |
| Industry | Oil & Gas Equipment & Services | |
| Market Cap ⓘ | $2.76B | |
| Beta ⓘ | 1.00 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 69.11 | 15.44 |
| P/B Ratio ⓘ | 2.20 | 1.73 |
| FCF Yield ⓘ | -2.97% | 8.20% |
| Dividend Yield ⓘ | 1.45% | 3.59% |
| EBIT / EV ⓘ | 1.61% | 7.46% |
| PEG ⓘ | -3.89 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 8.70% | 26.90% |
| RPS Growth (5Y CAGR) ⓘ | 11.76% | 6.90% |
| EPS Growth (5Y CAGR) ⓘ | -13.28% | -15.73% |
| BVPS Growth (5Y CAGR) ⓘ | 4.35% | 6.07% |
| Margin Growth (5Y Trend) ⓘ | 9.33% | 0.58% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 1.86% |
| DPS Growth (5Y CAGR) ⓘ | 52.90% | 16.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 2.96% | 11.40% |
| ROA (Latest) ⓘ | 1.89% | 6.06% |
| ROIC (5Y Median) ⓘ | 4.94% | 10.30% |
| ROA (5Y Median) ⓘ | 2.37% | 5.42% |
| Net Debt / EBIT (Latest) ⓘ | 5.82 | 1.64 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.61 | 1.83 |
| Net Debt / EBITDA (Latest) ⓘ | 1.09 | 1.08 |
| Net Debt / Assets ⓘ | 14.43% | 17.29% |
| EBITDA / Interest ⓘ | 10.04 | 9.64 |
| Operating Margin (Latest) ⓘ | 3.10% | 16.27% |
| Operating Margin (5Y Median) ⓘ | 3.06% | 20.39% |
| Debt to Equity (Latest) ⓘ | 27.76% | 54.76% |
| Profit Margin (Latest) ⓘ | 2.23% | 8.82% |
| Free Cash Flow (Latest) ⓘ | -$82.00M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +164.11% | +67.38% |
| 12M Return (excl. last month) ⓘ | +126.92% | +49.19% |
| 6M Return ⓘ | +28.10% | +7.07% |
| Price vs. 200-Day MA ⓘ | +11.80% | +9.56% |
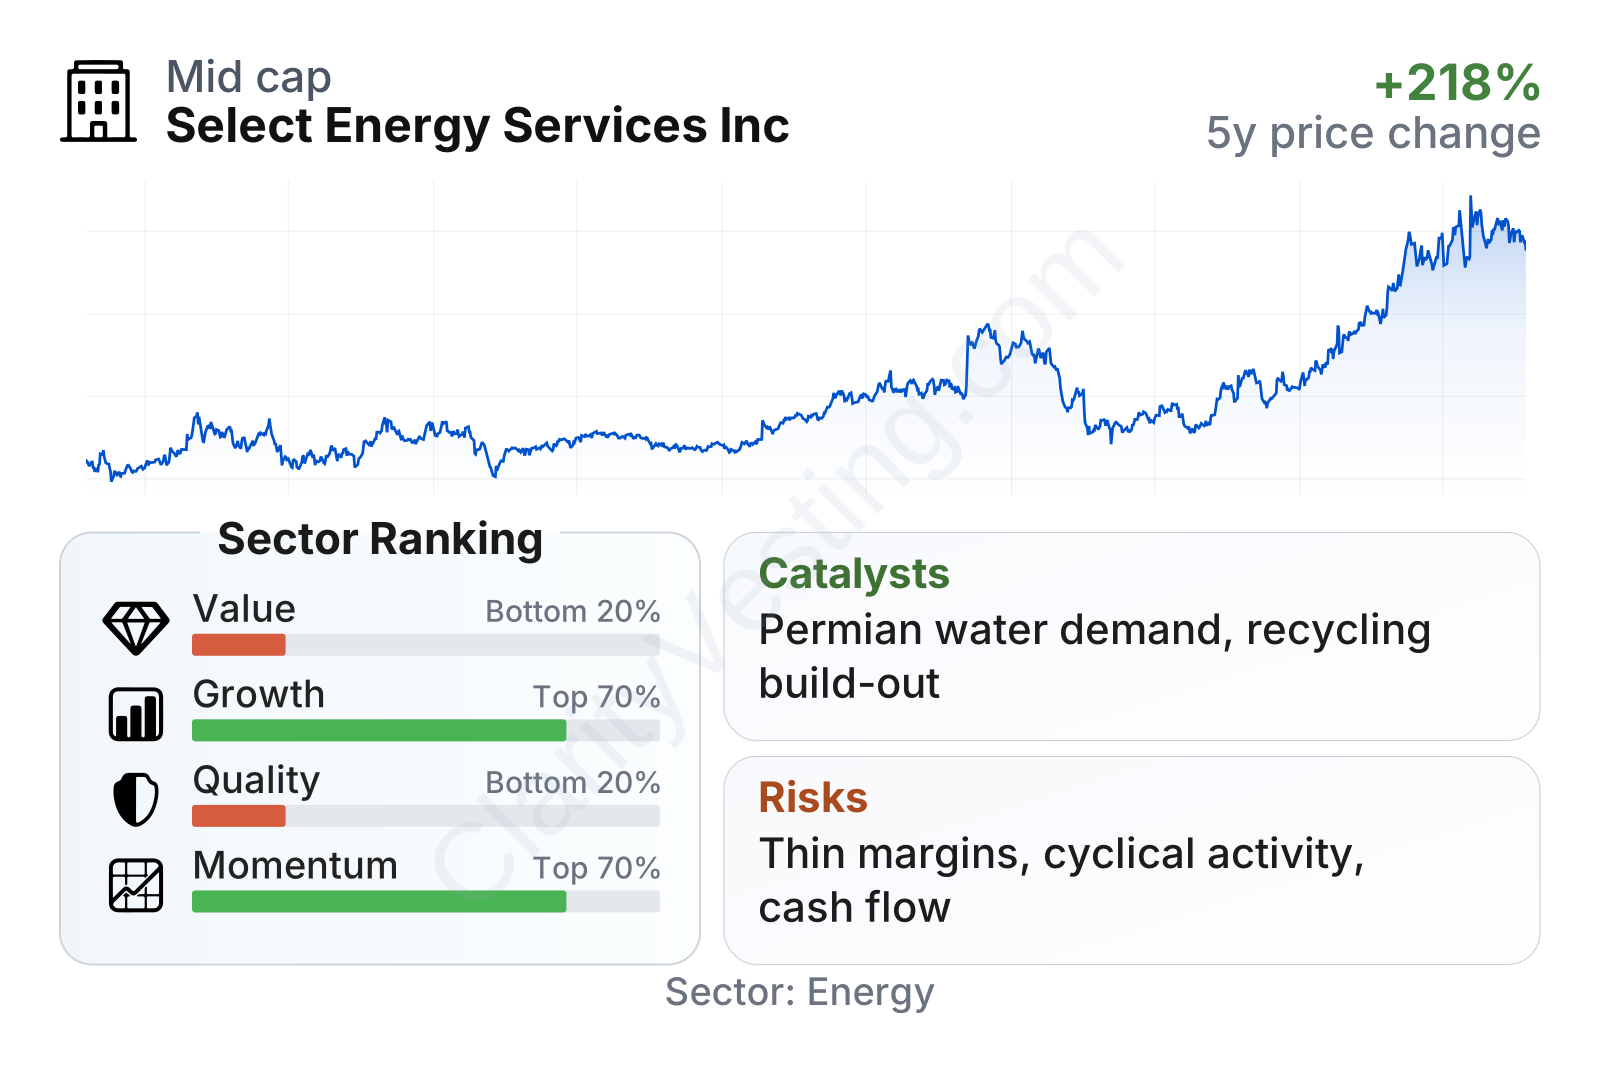
Select is a mid-sized company in its sector, and its recent stock performance has been strong, with gains over the last one-, three-, and six-month periods clearly ahead of the sector median. However, the underlying factor profile is mixed. Growth and momentum rank better than value and quality, while profitability, returns on capital, and free cash flow are weaker than many industry peers. The current valuation multiples also look demanding relative to the sector, especially considering that free cash flow is negative and earnings quality is not especially strong.
Growth
Select operates in a part of the energy service chain that still has room to grow over time. Produced-water volumes tend to rise as unconventional oil and gas basins mature, and operators increasingly need infrastructure for transfer, treatment, recycling, and disposal. That supports the long-term relevance of the company’s water platform. In addition, customers continue to emphasize operational efficiency and water reuse, which can favor providers with an established local network and integrated service offering.
The company’s strategy is sensible for that backdrop. Instead of competing only in the most commoditized drilling-related service lines, Select has built around water logistics, infrastructure, chemicals, and field support. This can create a broader customer relationship and may help smooth some cyclicality compared with businesses tied only to rig counts. The chemicals segment also adds another lever for growth if activity levels improve and customers keep outsourcing fluid and treatment solutions.
Recent growth, however, has not been linear. Revenue growth was exceptionally strong in 2022, then slowed materially, turned negative through much of 2024 and parts of 2025, and has only recently shown a modest return to positive year-over-year growth. That pattern suggests the company is still highly exposed to fluctuations in customer spending, even if its service mix is more specialized than some traditional oilfield service peers.
Cash generation is another important part of the growth debate. Free cash flow has been volatile, moving from a strong positive phase back into negative territory more recently. That does not automatically signal a structural problem, because infrastructure-heavy water businesses can have uneven investment cycles, but it does mean future growth needs to translate into steadier cash conversion to carry more weight.
One notable potential catalyst is the continued build-out of water infrastructure and recycling capacity in major shale basins. If producers favor larger outsourced partners that can handle water at scale, Select is positioned in an area with practical barriers such as basin presence, equipment networks, permits, and customer relationships. Recent company communications have also highlighted ongoing capital returns and the role of acquisitions and infrastructure development in expanding the platform, which can create incremental opportunity if execution remains disciplined.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


