Stock Analysis · WiseTech Global Limited (WTCHF)
Overview
WiseTech Global Limited is an Australian software company best known for CargoWise, a cloud platform used by freight forwarders, customs brokers, logistics providers, importers, exporters, and shipping-related businesses. In simple terms, its software helps companies manage the movement of goods across borders and supply chains. That includes tasks such as bookings, customs compliance, warehousing, transport management, invoicing, and visibility across shipments.
The business model is attractive for long-term analysis because the software is deeply embedded in customers’ daily operations. Once a large logistics company runs core workflows through a single platform, changing systems can be costly, disruptive, and slow. That tends to support recurring revenue and long customer relationships.
Based on company reporting, revenue is dominated by software and related services tied to CargoWise and the broader WiseTech platform. Public filings do not always provide a highly detailed revenue split by product line, but the broad picture is clear:
- Software-as-a-service and transaction-based platform revenue: approximately 85% to 95% of revenue. This includes usage of CargoWise and related logistics execution, customs, compliance, forwarding, warehousing, transport, and visibility modules.
- Implementation, consulting, training, and other services: approximately 5% to 15% of revenue. These activities support customer onboarding, configuration, deployment, and operational use of the platform.
Geographically, WiseTech serves global logistics companies, with exposure spread across Asia-Pacific, Europe, and the Americas. The company has expanded for years through internal development and acquisitions, aiming to build a broad operating system for international logistics rather than a narrow single-purpose application.
The business economics have historically been strong. Revenue has scaled much faster than direct delivery costs, which is typical of high-quality software platforms. At the same time, operating expenses have risen as WiseTech continued to invest heavily in product development. More recently, revenue has continued to grow strongly, but the latest period also shows a sharp rise in cost of revenue and interest expense, which matters for profit quality and needs close monitoring.
The long-term trend is still one of expanding sales and gross profit, supported by recurring software revenue. However, the latest year stands out because revenue jumped sharply while costs rose even faster than in prior years, making the earnings picture less clean than the top-line growth alone suggests.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Technology | |
| Industry | Software - Application | |
| Market Cap ⓘ | $7.43B | |
| Beta ⓘ | 1.11 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 41.68 | 29.95 |
| FCF Yield ⓘ | 14.59% | 4.22% |
| Dividend Yield ⓘ | 0.71% | 1.30% |
| EBIT / EV ⓘ | N/A | 2.83% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 82.00% | 15.80% |
| RPS Growth (5Y CAGR) ⓘ | 33.32% | 8.55% |
| EPS Growth (5Y CAGR) ⓘ | 25.92% | -11.72% |
| Margin Growth (5Y Trend) ⓘ | 1.14% | 0.39% |
| FCF Growth (5Y CAGR) ⓘ | 29.04% | 9.72% |
| DPS Growth (5Y CAGR) ⓘ | 26.55% | 7.73% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.36% |
| ROIC (5Y Median) ⓘ | 13.78% | 8.32% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 0.50 |
| Net Debt / EBIT (5Y Median) ⓘ | -0.11 | 0.46 |
| Net Debt / EBITDA (Latest) ⓘ | 2.00 | 0.28 |
| Net Debt / Assets ⓘ | 38.45% | 3.44% |
| EBITDA / Interest ⓘ | 6.46 | 12.67 |
| Operating Margin (Latest) ⓘ | N/A | 9.81% |
| Operating Margin (5Y Median) ⓘ | 39.01% | 8.50% |
| Debt to Equity (Latest) ⓘ | 115.58% | 33.33% |
| Profit Margin (Latest) ⓘ | 12.80% | 7.15% |
| Free Cash Flow (Latest) ⓘ | $1.08B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -49.44% | +49.46% |
| 12M Return (excl. last month) ⓘ | -56.39% | +16.51% |
| 6M Return ⓘ | -14.72% | +24.29% |
| Price vs. 200-Day MA ⓘ | -54.11% | +4.74% |
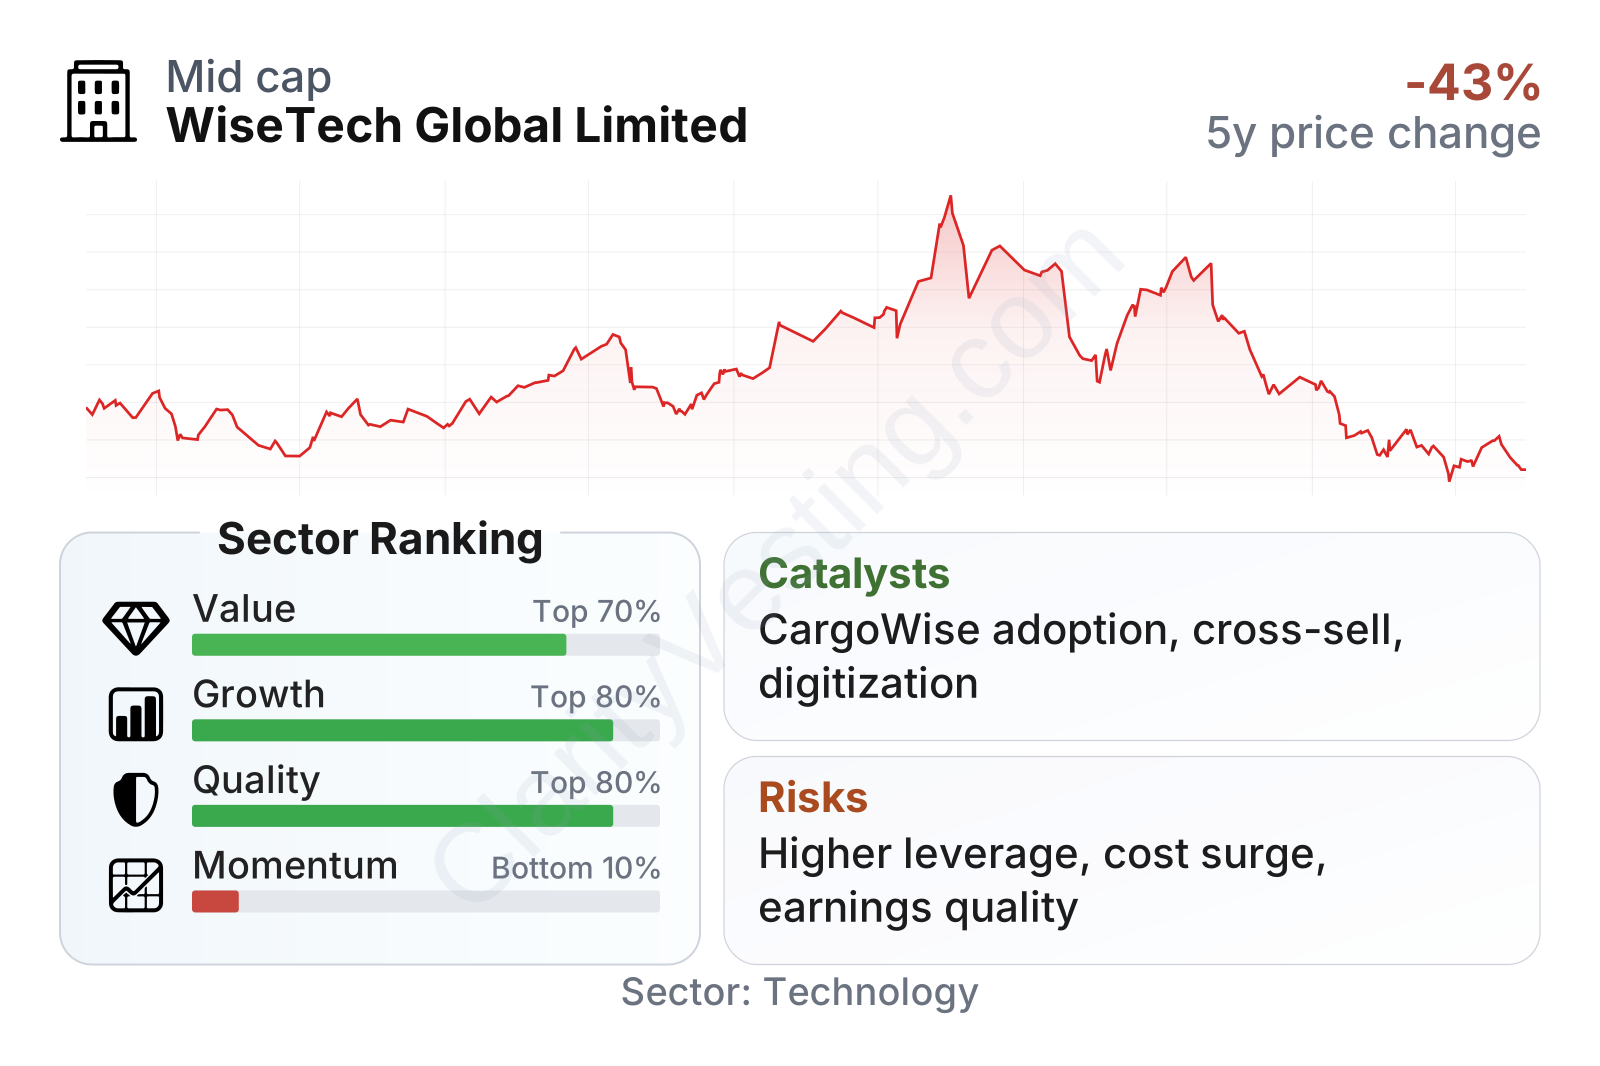
WiseTech stands out for strong growth and solid business quality relative to most software peers, but the market performance has been weak recently. Revenue growth, earnings growth, free cash flow growth, and margin history all rank well above sector medians, showing a company that has scaled effectively over several years. Profitability also looks healthy, with profit margin above the sector median and a five-year median operating margin that is unusually strong for application software.
Balance sheet indicators are more mixed. Free cash flow generation is strong in absolute terms and the company has posted a healthy return on invested capital over time, but leverage measures are less comfortable than many software peers. Debt-to-equity is above the sector median, net debt relative to assets is elevated, and interest coverage is lower than the median. That does not automatically indicate stress, but it does reduce the margin for error if earnings become more volatile.
The share price trend has been notably weak. After reaching much higher levels in 2025, the stock fell sharply into 2026, and momentum ranks near the bottom of the sector. That kind of disconnect usually means the market is reassessing either valuation, governance, profit durability, or all three at once.
Growth
WiseTech operates in a sector with credible long-term growth drivers. Global trade is highly complex, and many logistics processes remain fragmented, manual, or dependent on old on-premise systems. Companies moving freight across countries must manage customs rules, transport modes, documentation, billing, and compliance requirements. Software that can unify these activities on one platform addresses a real and lasting operational need.
WiseTech’s strategy also makes industrial sense. Rather than selling a simple niche tool, it has tried to become a system of record for logistics execution. That creates more value for large customers because each added function can reduce the need for separate software vendors. It can also increase switching costs over time, especially when customers standardize multiple regions and business units on CargoWise.
The company has several visible growth catalysts. One is continued penetration of large global freight forwarders and logistics providers, where even a small number of customer wins can materially expand revenue. Another is cross-selling: once a customer uses the platform for forwarding or customs, WiseTech can add adjacent modules such as warehouse, landside transport, rates management, compliance, and visibility tools. A third catalyst is ongoing digitization pressure across global supply chains, where efficiency and compliance are becoming more important as trade rules evolve.
Recent growth numbers remain very strong. Revenue growth of roughly 82% year over year is far above the software sector median, and five-year compounded growth in revenue per share, earnings per share, and free cash flow has also been well ahead of peers. That points to a business that has not only expanded, but has done so with meaningful economic output rather than growth with little cash generation.
Another favorable element is product investment. Research and development spending has climbed materially over time, indicating that the company is still reinvesting to broaden the platform. For a software firm seeking long duration growth, that is often a healthier sign than maximizing short-term profit at the expense of innovation.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


