Stock Analysis · WisdomTree Inc (WT)
Overview
WisdomTree Inc is an asset manager. In simple terms, it creates and manages investment products that let individuals and institutions put money into baskets of securities rather than selecting stocks or bonds one by one. The company is best known for exchange-traded funds, or ETFs, but it has also expanded into separately managed accounts, model portfolios, and digital asset-related offerings. Its business is tied closely to the amount of client money it manages, called assets under management, because management fees are the main engine of revenue.
Most of WisdomTree’s revenue comes from advisory fees earned on investment products. Based on recent company reporting, the revenue mix is heavily concentrated in recurring fee income, with smaller contributions from other sources such as administration and distribution-related items. A practical breakdown is:
- Advisory and management fees: about 90% to 95% — fees earned on ETFs and other investment products, largely driven by average assets under management and fee rates.
- Other revenues: about 5% to 10% — includes service, administrative, and other less recurring items that support the main asset management franchise.
Within its product lineup, WisdomTree has historically had strength in commodity, currency-hedged equity, fixed income, and thematic ETFs, and it has been building newer businesses around model portfolios and tokenized real-world assets. Geographically, the company operates mainly in the United States, with additional business in Europe and other international markets.
The business model is attractive when markets rise or when the company gathers new client assets: both can lift fee revenue without requiring costs to rise at the same pace. That operating leverage can make earnings move faster than revenue in strong periods, but it also means results can soften when markets fall or investors pull money out.
Over the last several years, revenue has moved up meaningfully, while operating income and net income have been more uneven. The broad pattern still shows a business that has scaled, with total revenue rising from a little above $300 million in 2021 to just under $500 million in 2025.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Financial Services | |
| Industry | Asset Management | |
| Market Cap ⓘ | $3.30B | |
| Beta ⓘ | 1.17 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 39.56 | 12.46 |
| P/B Ratio ⓘ | 7.82 | 1.25 |
| FCF Yield ⓘ | 4.81% | 9.82% |
| Dividend Yield ⓘ | 0.56% | 2.94% |
| EBIT / EV ⓘ | 2.40% | 8.11% |
| PEG ⓘ | 1.54 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 57.30% | 9.10% |
| RPS Growth (5Y CAGR) ⓘ | 12.88% | 12.31% |
| EPS Growth (5Y CAGR) ⓘ | 23.87% | -6.97% |
| BVPS Growth (5Y CAGR) ⓘ | 11.34% | 5.02% |
| Margin Growth (5Y Trend) ⓘ | 13.56% | -4.00% |
| FCF Growth (5Y CAGR) ⓘ | 18.76% | 4.71% |
| DPS Growth (5Y CAGR) ⓘ | -2.87% | 8.92% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 5.14% | 9.18% |
| ROE (Latest) ⓘ | 20.24% | 13.93% |
| ROA (Latest) ⓘ | 1.15% | 1.57% |
| ROIC (5Y Median) ⓘ | 11.75% | 7.80% |
| ROE (5Y Median) ⓘ | 16.52% | 12.15% |
| ROA (5Y Median) ⓘ | 6.74% | 1.28% |
| Net Debt / EBIT (Latest) ⓘ | 7.52 | 1.02 |
| Net Debt / EBIT (5Y Median) ⓘ | 2.90 | 0.72 |
| Net Debt / EBITDA (Latest) ⓘ | 6.86 | 0.88 |
| Operating Margin (Latest) ⓘ | 16.77% | 22.30% |
| Operating Margin (5Y Median) ⓘ | 26.73% | 24.50% |
| Debt to Equity (Latest) ⓘ | 257.67% | 59.34% |
| Profit Margin (Latest) ⓘ | 13.27% | 26.42% |
| Free Cash Flow (Latest) ⓘ | $158.51M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +227.21% | +95.73% |
| 12M Return (excl. last month) ⓘ | +61.76% | +17.30% |
| 6M Return ⓘ | +23.39% | +6.07% |
| Price vs. 200-Day MA ⓘ | +12.64% | +5.36% |
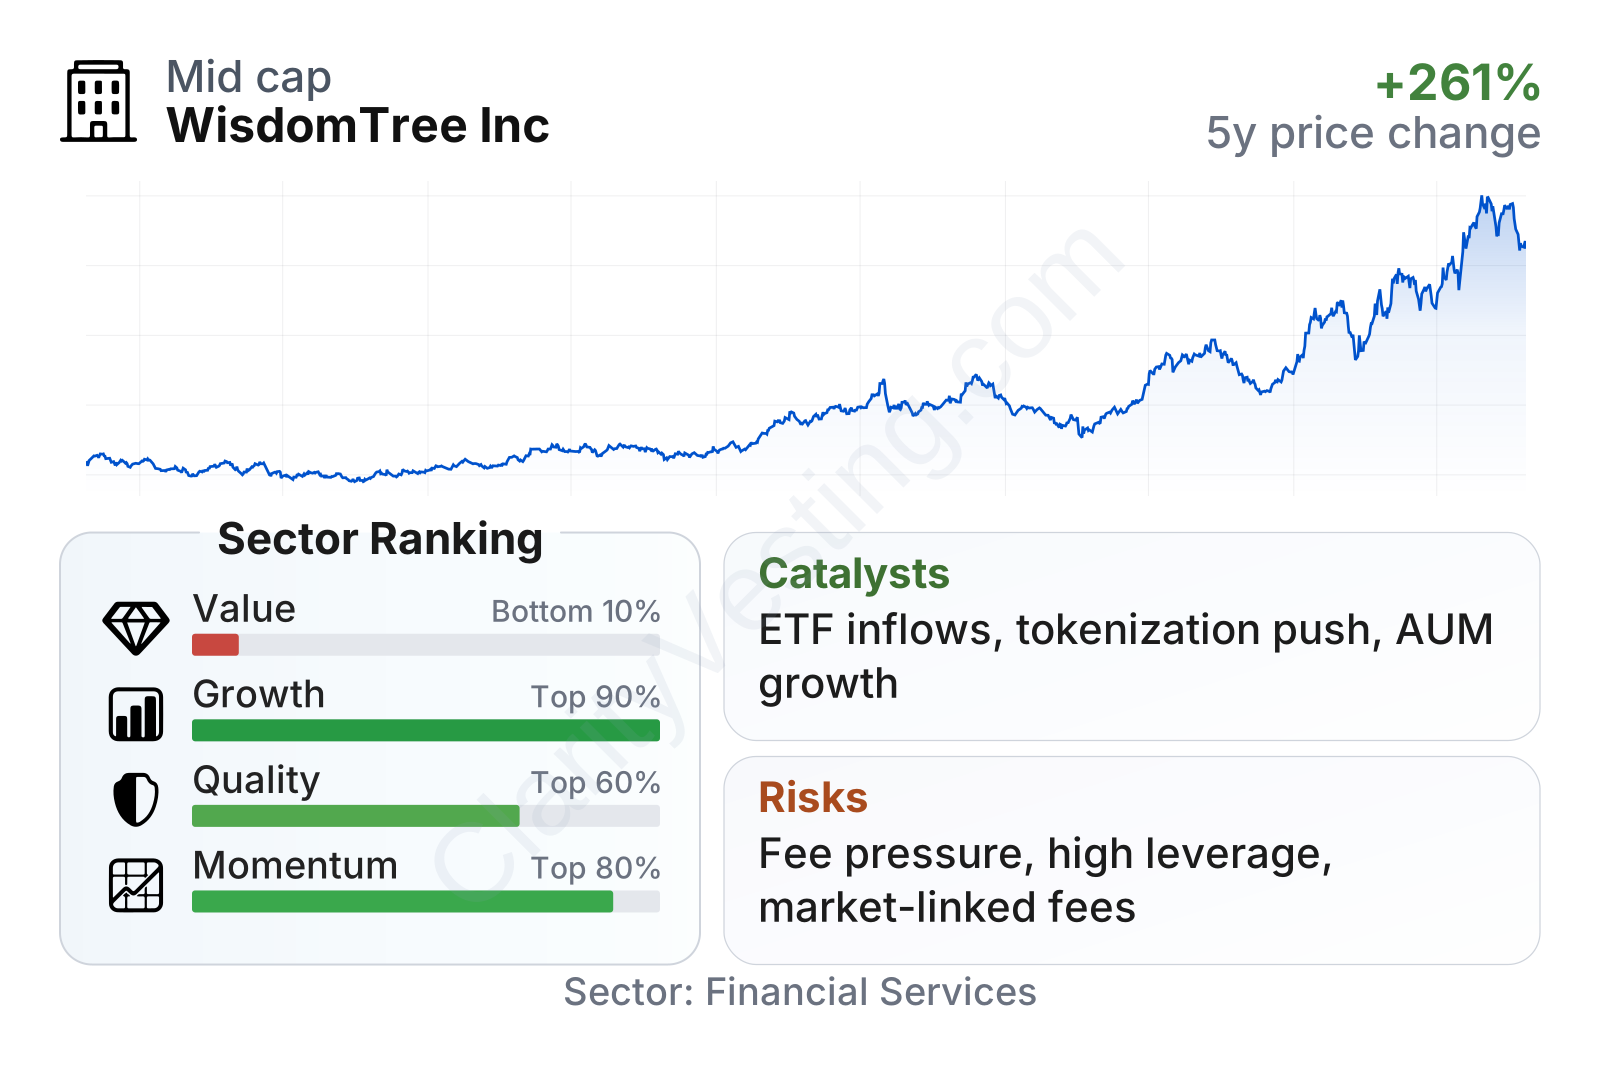
WisdomTree is a mid-sized asset manager with a market value in the low single-digit billions of dollars. The table shows a company with strong growth and strong market momentum compared with most financial peers, but a much weaker value profile. In other words, the market is paying a clear premium for recent progress. Quality is mixed: returns on equity look solid, but leverage is elevated and profit margins are not especially high versus the sector.
The share price trend has been powerful over the last three years, especially since 2024. That move reflects improving business performance, optimism around product growth, and a much richer valuation multiple than in earlier periods. The stock has also been more volatile than the market overall, as suggested by a beta a little above 1.2.
Growth
WisdomTree operates in a sector with a long runway: low-cost and specialized investment vehicles continue to gain share globally, and ETFs remain one of the most important structural growth areas in asset management. That matters because ETF providers can grow through several channels at once: rising markets, net inflows from clients, new product launches, and expansion into new distribution platforms.
WisdomTree’s strategy has logic for future growth because it is not relying on only one theme. The company combines established ETF categories with newer areas such as model portfolios and tokenized investment infrastructure. Its digital asset and tokenization efforts are especially notable. Instead of competing only on plain-vanilla index funds, WisdomTree is trying to occupy niches where branding, product design, and early institutional relationships can matter more.
Recent operating performance supports the idea that the business has been gaining traction. Revenue growth has been far above the sector median, and five-year growth in earnings per share, free cash flow, and book value per share has also been strong. Margin trends over the last five years have improved as well, even if the most recent margin level remains below some larger peers.
Earnings per share have trended higher after the 2022 dip, rising strongly through 2024 and 2025. That pattern suggests the company has benefited from a larger asset base and better operating leverage. Sustaining that trajectory will depend on whether asset growth continues and whether fee pressure remains manageable.
Book value per share has increased over the long term, though not in a straight line. That is consistent with a financial company that has been building franchise value while also dealing with acquisition effects, market movements, and capital structure changes. The longer-term increase is still favorable when viewed over a five-year period.
A meaningful catalyst is the continued push into tokenized real-world assets and digital finance rails. WisdomTree has publicly positioned itself as more than a traditional ETF sponsor, aiming to connect regulated asset management with blockchain-based infrastructure. If that market develops further, the company could gain visibility beyond its current size. Another catalyst is simple but powerful: in asset management, higher markets and positive net inflows can lift revenue quickly because fees are charged on asset balances.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


