Stock Analysis · Wheaton Precious Metals Corp (WPM)
Overview
Wheaton Precious Metals Corp is a precious-metals streaming company. That means it does not usually build or operate mines itself. Instead, it provides upfront financing to mining companies and, in return, secures the right to buy a portion of future metal production at preset low costs. Wheaton then sells that metal into the market. This model gives the company exposure to gold, silver, and other metals while avoiding many of the direct operating risks that traditional miners face, such as mine labor issues, cost overruns, and day-to-day site management.
The business is mainly tied to precious metals, but the portfolio also includes some exposure to other metals through streaming agreements. Based on recent company disclosures, revenue is primarily generated from the sale of metals received under these contracts, with gold clearly leading the mix.
- Gold: approximately 55% to 60% of revenue. This is the largest contributor and comes from streams tied to producing mines in multiple countries.
- Silver: approximately 35% to 40% of revenue. Silver remains a core part of Wheaton’s identity and portfolio.
- Palladium, cobalt, and other metals: approximately 3% to 8% combined, depending on period and deliveries.
Geographically, Wheaton’s cash flow is diversified across mines operated by partners in the Americas and other mining regions. That diversification matters because the company depends on counterparties to produce and deliver metal. Its portfolio structure is one of the main reasons the company has historically posted very high margins relative to most mining businesses.
The business model also explains why reported costs can stay comparatively low even when metal prices rise. Wheaton’s purchase prices under streaming contracts are generally fixed or only lightly variable, so higher gold and silver prices can translate into wider profit spreads.
The overall earnings structure has become more favorable over time. Revenue expanded strongly into 2025, while cost of sales increased much more slowly, which helped lift gross profit materially. The pattern is consistent with a streaming model that can scale well when metal prices rise and delivery volumes improve.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Gold | |
| Market Cap ⓘ | $59.60B | |
| Beta ⓘ | 1.24 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 29.10 | 16.92 |
| P/B Ratio ⓘ | 6.21 | 1.66 |
| FCF Yield ⓘ | -4.91% | 5.83% |
| Dividend Yield ⓘ | 0.55% | 2.07% |
| EBIT / EV ⓘ | 3.58% | 6.38% |
| PEG ⓘ | 0.43 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 84.70% | 11.25% |
| RPS Growth (5Y CAGR) ⓘ | 17.58% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | 23.49% | -15.24% |
| BVPS Growth (5Y CAGR) ⓘ | 8.33% | 5.49% |
| Margin Growth (5Y Trend) ⓘ | 10.79% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 15.28% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 7.76% | 5.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 22.08% | 9.59% |
| ROA (Latest) ⓘ | 19.93% | 4.92% |
| ROIC (5Y Median) ⓘ | 10.32% | 7.91% |
| ROA (5Y Median) ⓘ | 10.25% | 3.92% |
| Net Debt / EBIT (Latest) ⓘ | 0.77 | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | -1.00 | 1.69 |
| Net Debt / EBITDA (Latest) ⓘ | 0.67 | 0.93 |
| Net Debt / Assets ⓘ | 15.43% | 13.69% |
| EBITDA / Interest ⓘ | 83.50 | 12.38 |
| Operating Margin (Latest) ⓘ | 76.74% | 13.24% |
| Operating Margin (5Y Median) ⓘ | 62.83% | 11.82% |
| Debt to Equity (Latest) ⓘ | 20.40% | 40.30% |
| Profit Margin (Latest) ⓘ | 64.66% | 6.38% |
| Free Cash Flow (Latest) ⓘ | -$2.93B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +214.49% | +73.47% |
| 12M Return (excl. last month) ⓘ | +37.99% | +27.59% |
| 6M Return ⓘ | -6.53% | -4.02% |
| Price vs. 200-Day MA ⓘ | -1.15% | -0.65% |
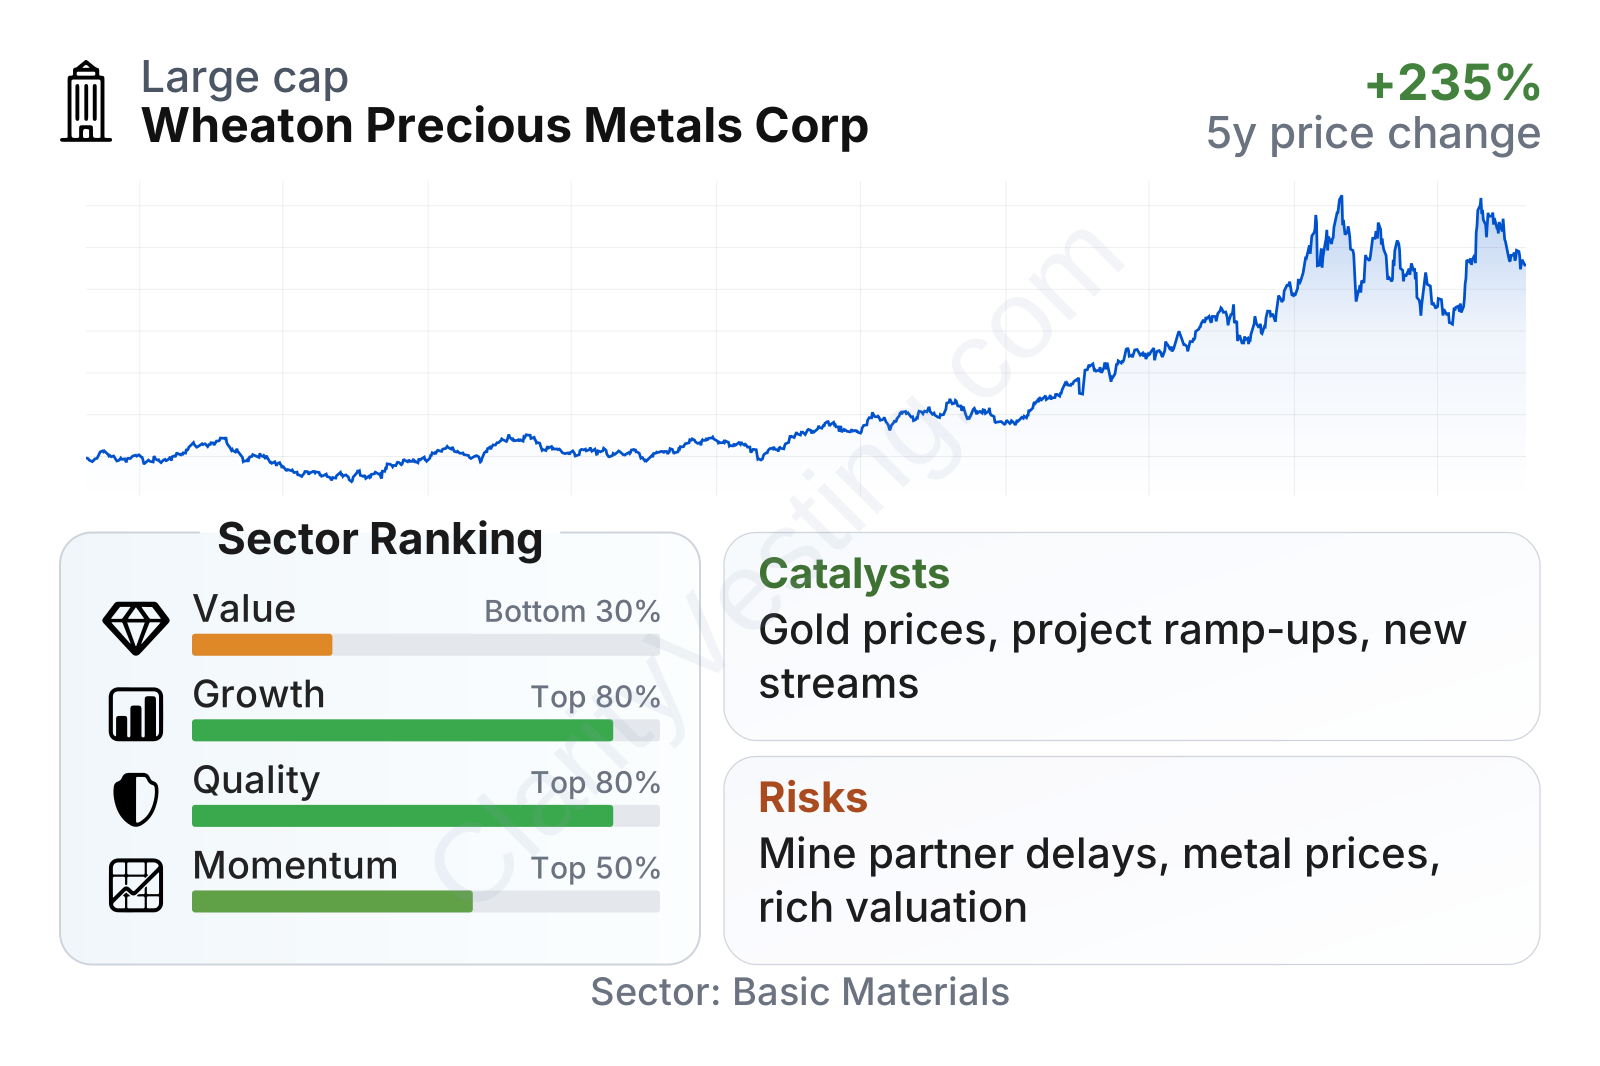
Wheaton stands out for quality and growth more than for cheapness. Profitability, returns on capital, and balance-sheet strength rank well above much of the sector, while recent growth has also been notably stronger than many peers. By contrast, valuation multiples remain elevated, and income yield is modest. In simple terms, the market is paying up for a large, profitable, lower-risk way to gain exposure to precious metals.
The share price trend over the last several years has been strong, although not smooth. Like most precious-metals names, the stock can move sharply as market expectations for gold prices, interest rates, and global uncertainty change.
Growth
Wheaton operates in a sector with long-term support from several forces. Gold demand is often helped by central-bank buying, inflation concerns, geopolitical uncertainty, and the role of gold as a store of value. Silver adds another angle because it is both a precious metal and an industrial metal, with demand linked to electronics, solar panels, and electrification. This gives Wheaton exposure to both defensive and industrial demand trends.
Its strategy for future expansion is straightforward and sensible for this business model: keep signing new streaming deals, expand exposure to high-quality mines, and benefit from rising production at existing partner assets. Because Wheaton does not need to build and run mines itself, growth can come from capital allocation rather than direct operating execution. That tends to make the company more scalable and less operationally heavy than a traditional miner.
Revenue growth has accelerated sharply after a weaker period in 2022 and early 2023. The recent pace is far above the sector median, showing a mix of stronger metal prices, better delivery volumes, and portfolio contributions from underlying assets. That kind of rebound is important because it shows the company is not relying on just one mine or one quarter to improve results.
Free cash flow has been volatile, which is normal when a streaming company commits capital to new agreements. However, the broader multi-year pattern remains favorable, and the latest trailing figures indicate strong cash generation. This matters because Wheaton’s growth model depends on having financial capacity available when attractive deals appear.
A meaningful catalyst is its development pipeline. Wheaton has interests linked to major mining projects that are expected to contribute over time as they move toward production or ramp-up. In this type of business, future value often comes from streams already signed but not yet producing at full levels. That creates a built-in growth runway if partner projects stay on schedule.
Recent company updates have also pointed to continued confidence in long-term attributable production targets. For a streamer, visible future production from contracted assets is one of the clearest indicators that growth can extend beyond short-term metal price moves.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


