Stock Analysis · Advanced Drainage Systems Inc (WMS)
Overview
Advanced Drainage Systems Inc. designs and manufactures water management products used in construction and infrastructure. In simple terms, the company helps move, store, and manage stormwater and wastewater. Its products are used in residential building, commercial construction, agriculture, roads and highways, and large infrastructure projects. A major part of its business is high-performance thermoplastic pipe, especially corrugated pipe, which often serves as a lighter and more durable alternative to traditional materials such as concrete or metal.
The company operates through two reportable segments: Pipe and Infiltrator. Pipe is the larger business and includes pipes, fittings, water control structures, and related drainage products. Infiltrator focuses on septic and on-site wastewater systems, chambers, and related products. Based on the latest annual filing for fiscal 2026, revenue is concentrated as follows:
- Domestic Pipe: approximately 70% of total revenue. This includes the core U.S. pipe business, drainage products, and stormwater solutions sold into construction, infrastructure, and agricultural markets.
- Infiltrator: approximately 23% of total revenue. This business includes septic leachfield chambers, tanks, and wastewater treatment components for residential and commercial on-site systems.
- International: approximately 7% of total revenue. This includes sales outside the United States, mainly drainage and water management products.
One important feature of the business model is vertical integration. Advanced Drainage Systems not only makes finished products, but also benefits from a large recycling operation that turns used plastic into raw material for pipe production. That helps support costs, supply security, and sustainability claims at the same time.
The business has shown an ability to keep a strong share of revenue as operating profit over time. Revenue has moved around with construction demand and pricing, but profitability has remained well above many peers, which suggests the company has meaningful pricing power and manufacturing efficiency.
Key Figures
Metric Value Sector ⓘ Date Oct 17, 2026 Context Sector Industrials Industry Building Products & Equipment Market Cap ⓘ $9.56B Beta ⓘ 1.29 P/E Ratio ⓘ 21.59 22.10 P/B Ratio ⓘ 5.25 1.97 FCF Yield ⓘ 5.76% 6.38% Dividend Yield ⓘ 0.59% 1.94% EBIT / EV ⓘ 6.14% 4.79% PEG ⓘ 1.22 Revenue Growth ⓘ 20.60% 9.30% RPS Growth (5Y CAGR) ⓘ 0.58% 7.81% EPS Growth (5Y CAGR) ⓘ -22.76% -13.06% BVPS Growth (5Y CAGR) ⓘ 13.41% 6.14% Margin Growth (5Y Trend) ⓘ 6.53% 0.88% FCF Growth (5Y CAGR) ⓘ 45.85% 11.01% DPS Growth (5Y CAGR) ⓘ 7.88% 9.48% ROIC (Latest) ⓘ 15.97% 10.84% ROA (Latest) ⓘ 10.50% 5.41% ROIC (5Y Median) ⓘ 19.19% 9.38% ROA (5Y Median) ⓘ 12.94% 4.95% Net Debt / EBIT (Latest) ⓘ 2.29 2.08 Net Debt / EBIT (5Y Median) ⓘ 1.54 2.27 Net Debt / EBITDA (Latest) ⓘ 1.73 1.39 Net Debt / Assets ⓘ 35.55% 19.28% EBITDA / Interest ⓘ 9.47 9.58 Operating Margin (Latest) ⓘ 21.70% 10.50% Operating Margin (5Y Median) ⓘ 23.46% 10.29% Debt to Equity (Latest) ⓘ 94.75% 65.48% Profit Margin (Latest) ⓘ 14.00% 6.67% Free Cash Flow (Latest) ⓘ $550.15M 3Y Return ⓘ +9.51% +61.68% 12M Return (excl. last month) ⓘ -10.96% +12.58% 6M Return ⓘ -19.32% 0.00% Price vs. 200-Day MA ⓘ -13.34% +0.02%
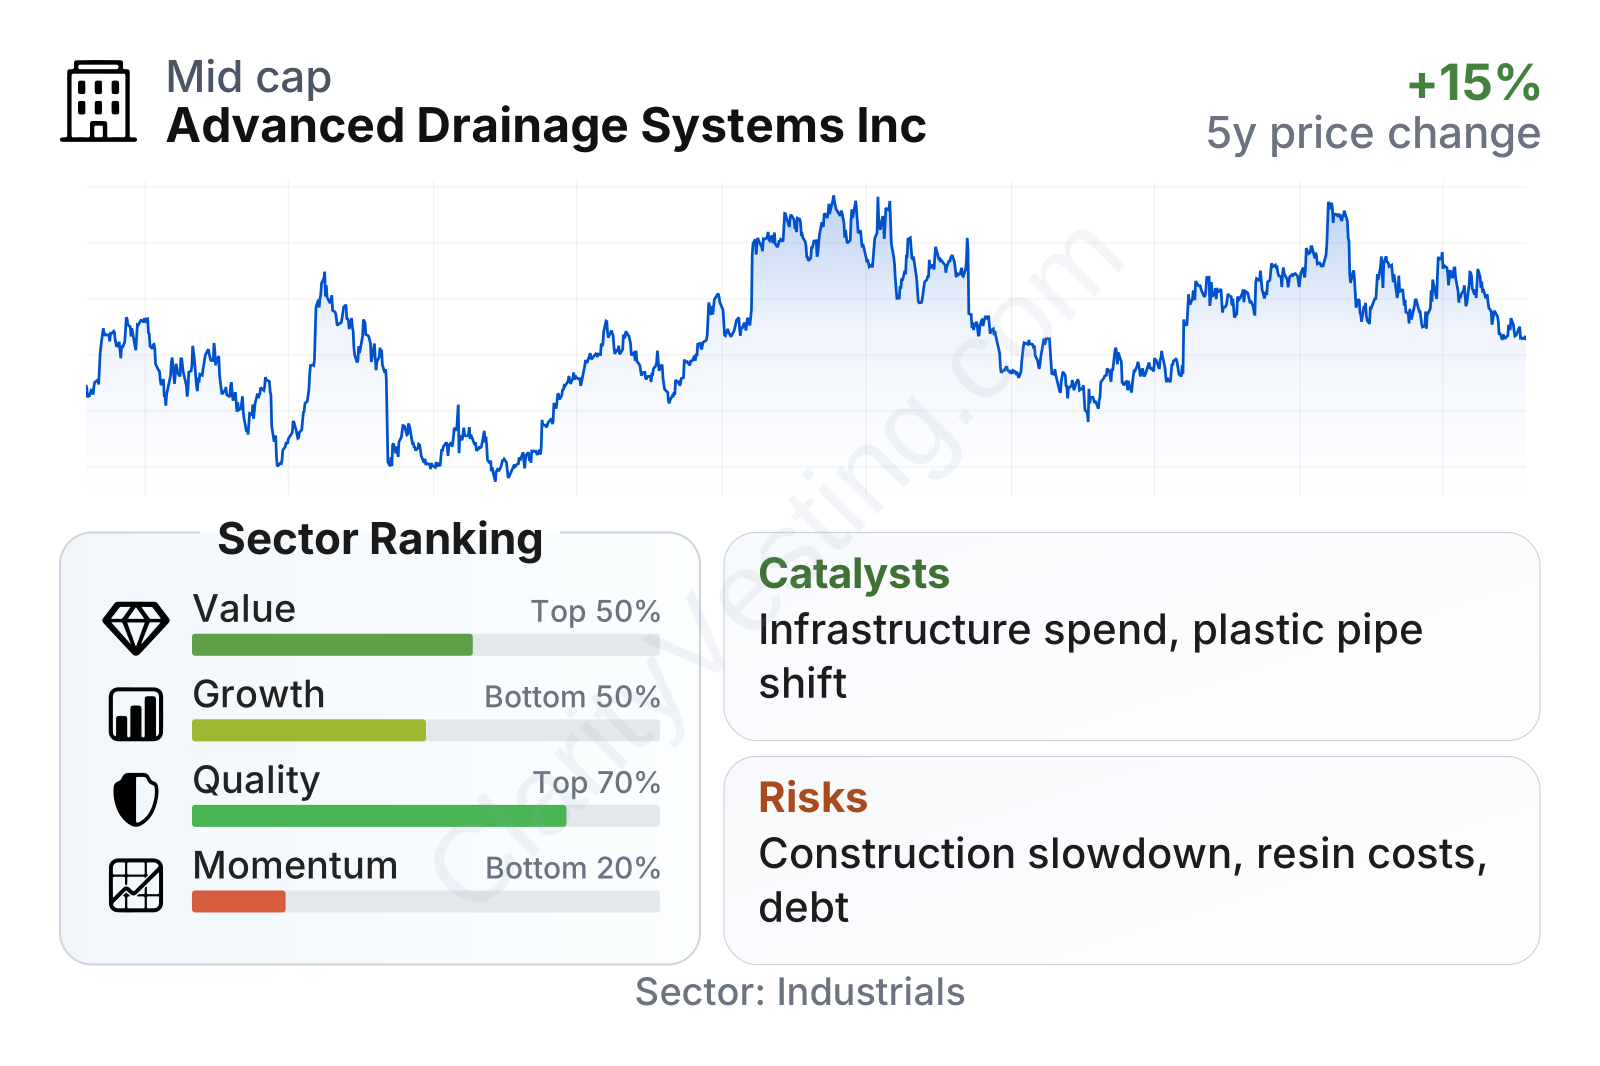
Advanced Drainage Systems is a large mid-cap to lower large-cap industrial company with a stock that has been more volatile than the broader market. The overall profile is mixed but interesting: profitability and returns on capital are strong, valuation is close to the sector on earnings, and free cash flow generation is solid. On the other hand, recent share price momentum has been weak versus the sector, and leverage is somewhat higher than typical industry levels.
The quality indicators stand out the most. Returns on assets and invested capital are clearly above sector medians, and operating margins are far stronger than what is common in the broader industrial peer group. Growth metrics look less impressive over a five-year lens because earnings were unusually strong during prior peak periods, making comparisons harder, even though recent year-over-year revenue growth has improved again.
Growth
Advanced Drainage Systems operates in a part of the market with long-term structural support. Stormwater management, water conservation, aging infrastructure replacement, and stricter environmental rules all create demand for modern drainage systems. Population growth in many U.S. regions, continued residential development, data center and industrial site construction, and public infrastructure spending also support the category over time.
The company’s strategy is logical for this setting. It continues to push engineered plastic products as substitutes for legacy materials, expand its presence in higher-value water management systems, and use acquisitions to broaden product offerings and geographic reach. The Infiltrator business is especially relevant because on-site wastewater treatment is a recurring need in areas without municipal sewer access. Combined with the core drainage franchise, that gives the company exposure to both new construction and repair or replacement demand.
Revenue growth has not been smooth, which is normal for a business linked to construction cycles, weather, and raw material pass-through pricing. Still, the recent direction is better, with year-over-year growth rebounding into positive territory and the latest reading well above the sector median. That suggests demand conditions have improved and that the company is recovering from a softer patch rather than facing a broken business model.
Cash generation also supports the growth case. Free cash flow has risen sharply from the level seen a few years ago and remains robust even after a temporary dip. That matters because it gives the company flexibility to fund plant investments, acquisitions, debt reduction, and shareholder returns without depending heavily on external financing.
A notable catalyst is U.S. infrastructure and water-related spending. Federal and state funding for roads, drainage, resiliency, and wastewater systems can create a multi-year pipeline of projects that fit the company’s products. Another support factor is the company’s recycling network, which can strengthen margins and reinforce its position with customers increasingly focused on sustainability and lifecycle cost.
Recent company communications in 2026 also point to continued investment in capacity, distribution, and product breadth. That does not guarantee rapid expansion, but it does indicate management is positioning the business for demand beyond a single cycle.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


