Stock Analysis · Willdan Group Inc (WLDN)
Overview
Willdan Group Inc is a consulting and technical services company that helps public agencies, utilities, and private customers plan, design, and carry out infrastructure and energy projects. In simple terms, the company works on problems such as improving electric grid efficiency, managing energy use in buildings, modernizing public infrastructure, and providing engineering support for transportation, water, and municipal projects.
Over the last several years, Willdan has increasingly centered its business on energy and sustainability work. That includes energy efficiency programs, electrification, grid modernization, clean energy planning, and related advisory and implementation services. Its older engineering and consulting operations remain important, but the company today is much more tied to the long-term push for lower energy use, cleaner power systems, and infrastructure upgrades.
Based on recent company reporting, revenue is mainly generated from the following areas:
- Energy, sustainability, and utility program services: approximately 70% to 80% of revenue in recent periods. This includes utility-sponsored energy efficiency programs, advisory work, program management, electrification, and technical support tied to the energy transition.
- Engineering and consulting services: approximately 20% to 30% of revenue. This covers civil engineering, municipal and public infrastructure work, transportation, water, and other technical consulting assignments.
The broad direction is clear even if the exact mix moves from quarter to quarter: Willdan is no longer just a traditional engineering consultant. It is increasingly a specialized service provider connected to utility spending, public-sector infrastructure, and energy transition programs.
The multiyear financial flow also shows a meaningful business shift. Revenue has climbed strongly since 2021, while profitability improved from losses to solid positive earnings by 2025. Gross profit expanded faster than overhead for much of that period, suggesting that scale and mix are helping the model.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Engineering & Construction | |
| Market Cap ⓘ | $1.13B | |
| Beta ⓘ | 1.19 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 17.34 | 22.10 |
| P/B Ratio ⓘ | 3.25 | 1.97 |
| FCF Yield ⓘ | 5.54% | 6.38% |
| Dividend Yield ⓘ | N/A | 1.94% |
| EBIT / EV ⓘ | 4.09% | 4.79% |
| PEG ⓘ | 0.48 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 33.20% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 12.34% | 7.81% |
| EPS Growth (5Y CAGR) ⓘ | 39.35% | -13.06% |
| BVPS Growth (5Y CAGR) ⓘ | 8.89% | 6.14% |
| Margin Growth (5Y Trend) ⓘ | 9.12% | 0.88% |
| FCF Growth (5Y CAGR) ⓘ | 171.35% | 11.01% |
| DPS Growth (5Y CAGR) ⓘ | -68.35% | 9.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 18.65% | 10.84% |
| ROA (Latest) ⓘ | 11.43% | 5.41% |
| ROIC (5Y Median) ⓘ | 6.13% | 9.38% |
| ROA (5Y Median) ⓘ | 2.65% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | 0.94 | 2.08 |
| Net Debt / EBIT (5Y Median) ⓘ | 0.97 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 0.63 | 1.39 |
| Net Debt / Assets ⓘ | 7.87% | 19.28% |
| EBITDA / Interest ⓘ | 21.62 | 9.58 |
| Operating Margin (Latest) ⓘ | 7.14% | 10.50% |
| Operating Margin (5Y Median) ⓘ | 4.71% | 10.29% |
| Debt to Equity (Latest) ⓘ | 25.45% | 65.48% |
| Profit Margin (Latest) ⓘ | 8.80% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $62.33M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +261.63% | +61.68% |
| 12M Return (excl. last month) ⓘ | -19.94% | +12.58% |
| 6M Return ⓘ | -3.50% | 0.00% |
| Price vs. 200-Day MA ⓘ | -18.81% | +0.02% |
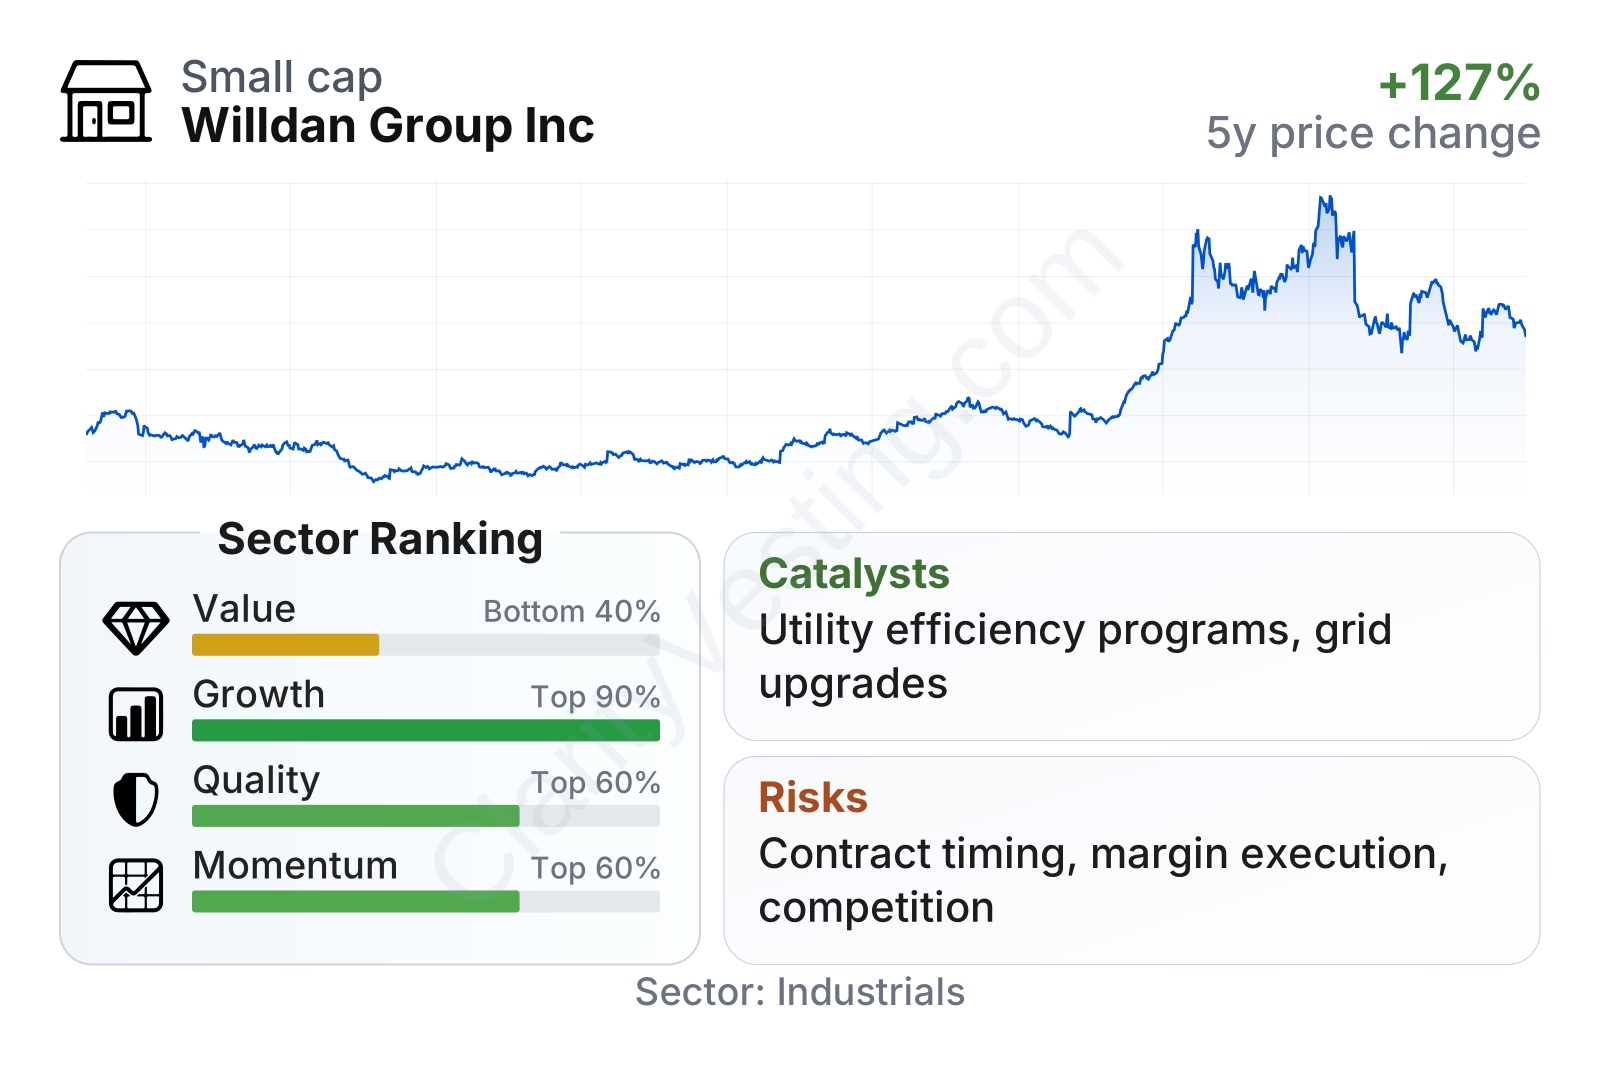
Willdan is a small-cap industrial company with a market value a little above $1 billion, so it sits in a size range where strong execution can move results quickly, but share-price swings can also be sharper than with larger peers. The stock’s volatility is somewhat above the broader market, and the price history reflects that clearly: the shares fell hard in 2022, recovered through 2024 and 2025, then pulled back again in 2026.
On the operating side, the latest profile looks stronger than the company’s earlier years. Growth ranks near the top of its sector, quality appears above average, and leverage is notably lower than many industry peers. Value measures are more mixed: the earnings multiple is below the sector median, but asset-based valuation is higher, which often happens when the market gives credit for improving margins and future growth potential rather than just current book value.
Growth
Willdan operates in areas that appear structurally attractive for long-term expansion. Utilities and public agencies are spending on grid modernization, energy efficiency, building decarbonization, distributed energy resources, wildfire and resilience planning, and broader infrastructure upgrades. These are not one-time themes. They are backed by regulatory requirements, aging assets, reliability concerns, and long planning cycles, which can support demand even when the general economy slows.
The company’s strategy broadly fits these trends. Willdan has spent years building expertise in utility and public-sector energy programs, where customers often need both technical advice and program execution. That creates a more specialized position than a plain engineering contractor. It also helps that many projects are tied to policy goals and mandated spending programs rather than only discretionary capital budgets.
Revenue growth has been strong overall, even though quarterly comparisons can be uneven. The latest year-over-year pace is far above the sector median, and the longer-term picture also looks favorable, with five-year revenue-per-share growth ahead of the typical peer. That matters because it suggests expansion is not coming only from issuing more shares or from a single short-lived contract cycle.
Cash generation has also improved materially. Free cash flow was negative in earlier periods but turned positive and has remained positive, which is an important sign for a project-based service business. In plain language, Willdan is not just reporting accounting profits; it is also converting more of its work into actual cash that can support debt reduction, acquisitions, and internal investment.
A notable catalyst is the company’s exposure to utility-backed energy efficiency and electrification programs. These programs can scale over multiple years and often expand when states and utilities raise efficiency targets or grid investment plans. Another catalyst is public infrastructure spending, especially where engineering work overlaps with resilience, transportation, and environmental upgrades. Recent company communications have also pointed to contract wins and program demand tied to clean energy and grid-related work, reinforcing the idea that Willdan is participating in an active market rather than waiting for a turnaround.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


