Stock Analysis · West African Resources Limited (WFRSF)
Overview
West African Resources Limited is a gold mining company focused on West Africa. Its core business is discovering, developing, and operating gold mines, then selling the produced gold into the market. The company’s main operating base is in Burkina Faso, where its flagship Sanbrado gold operation has driven most of its recent financial performance. For a general reader, this is a relatively straightforward mining business: find gold deposits, build or expand mines, extract ore, process it, and generate revenue from gold sales.
Revenue is overwhelmingly tied to one source, which makes the business easy to understand but also concentrated. Based on recent company reporting and operating disclosures, the revenue mix is approximately:
- Gold sales from Sanbrado: about 95% to 100% of revenue. This includes doré gold produced from open-pit and underground mining, processed and sold at prevailing gold prices.
- Other mining-related income: typically 0% to 5%. This can include by-product, service, or miscellaneous operating items, but these are not the economic driver of the business.
The company is still primarily a single-asset producer from a revenue perspective, although that is intended to change as new projects move forward. This matters because long-term outcomes depend not only on the current mine, but also on whether management can successfully turn its broader project pipeline into additional producing assets.
Financially, the business has shown a strong conversion of revenue into operating profit in recent years. Revenue moved from roughly the low hundreds of millions earlier in the decade to well above $1 billion in 2025, while profitability expanded sharply as well. That combination usually reflects a mix of higher production, stronger gold prices, and solid cost control.
The financial flow also shows a useful pattern for long-term analysis: revenue and gross profit dipped during the middle of the period, then recovered strongly, with 2025 standing out as a major step up in both sales and earnings. Even after taxes and interest, the company kept a large share of operating profit, which points to a business that has recently been highly cash generative.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 10, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Gold | |
| Market Cap ⓘ | $2.33B | |
| Beta ⓘ | 1.12 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 5.35 | 17.36 |
| P/B Ratio ⓘ | 1.20 | 1.73 |
| FCF Yield ⓘ | 44.92% | 5.81% |
| Dividend Yield ⓘ | N/A | 1.98% |
| EBIT / EV ⓘ | N/A | 6.34% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 206.50% | 11.15% |
| RPS Growth (5Y CAGR) ⓘ | 14.40% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -12.80% |
| BVPS Growth (5Y CAGR) ⓘ | 26.31% | 5.49% |
| Margin Growth (5Y Trend) ⓘ | -1.60% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 5.04% | 0.20% |
| DPS Growth (5Y CAGR) ⓘ | -58.85% | 5.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.26% |
| ROA (Latest) ⓘ | 32.28% | 4.92% |
| ROIC (5Y Median) ⓘ | 29.53% | 7.82% |
| ROA (5Y Median) ⓘ | 19.54% | 3.88% |
| Net Debt / EBIT (Latest) ⓘ | -0.26 | 1.37 |
| Net Debt / EBIT (5Y Median) ⓘ | -0.17 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | -0.24 | 0.92 |
| Net Debt / Assets ⓘ | -15.27% | 13.56% |
| EBITDA / Interest ⓘ | N/A | 12.28 |
| Operating Margin (Latest) ⓘ | 55.70% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 47.61% | 11.82% |
| Debt to Equity (Latest) ⓘ | 21.00% | 39.91% |
| Profit Margin (Latest) ⓘ | 25.29% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $1.05B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +212.92% | +68.93% |
| 12M Return (excl. last month) ⓘ | +27.54% | +36.53% |
| 6M Return ⓘ | -5.17% | 0.00% |
| Price vs. 200-Day MA ⓘ | +4.68% | -0.18% |
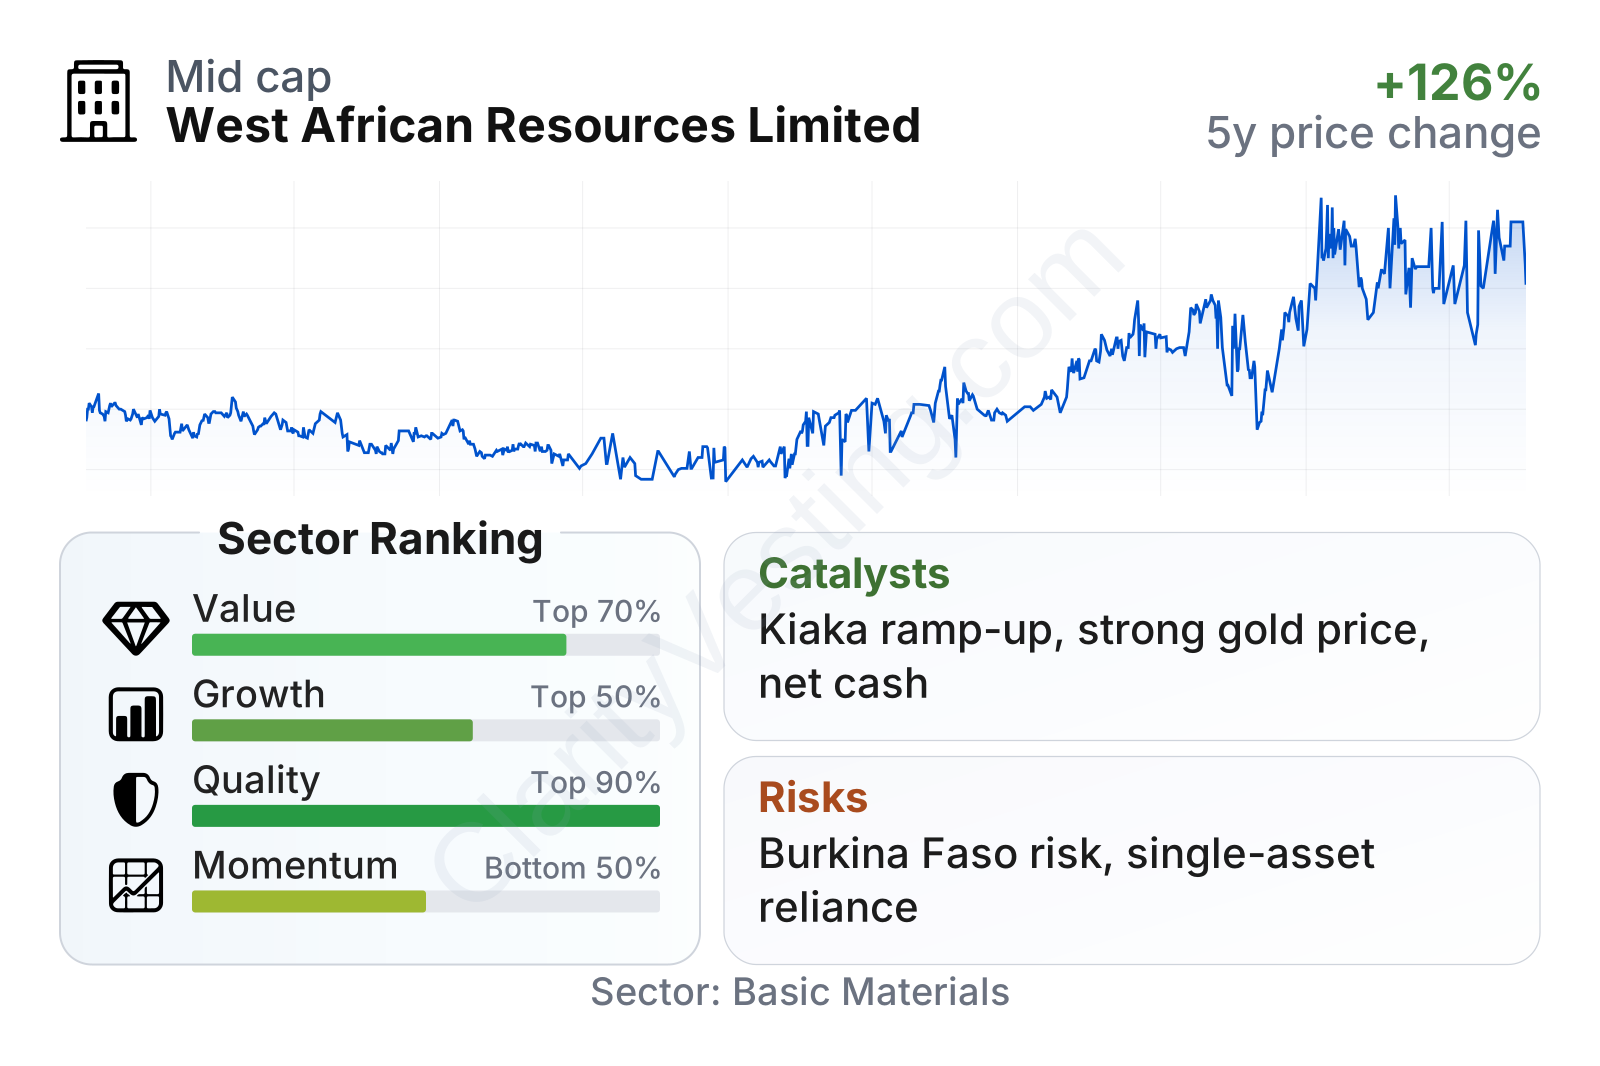
On the market side, the shares have climbed sharply over the past three years, with gains far ahead of the sector median. The shorter-term picture is also constructive, although the strongest acceleration appears relatively recent, which means sentiment has already improved materially.
The broader fundamentals remain notable. Profitability and balance-sheet quality rank very well against most gold peers. Operating margin is far above the sector median, return on assets is unusually strong for a miner, and the company is in a net cash position rather than being heavily leveraged. Free cash flow generation is also well above typical sector levels.
Valuation looks undemanding compared with many mining companies. The earnings multiple is materially below the sector median, while the price-to-book ratio is also modest. That low valuation stands alongside very strong recent revenue growth, which suggests the market is still weighing the usual risks attached to single-region gold producers and mine development execution.
Growth
Gold mining is a cyclical industry, but it is also one with durable relevance. Gold remains important as a store of value, a reserve asset for central banks, and a hedge during periods of inflation, currency weakness, or geopolitical stress. That does not make the sector automatically attractive at all times, but it does mean West African Resources operates in an industry with continuing global demand rather than a fading niche.
The company’s strategy for future growth is coherent. Instead of trying to build a highly diversified mining group all at once, it has focused on establishing a profitable producing base and then using that platform to fund expansion. In practical terms, this means generating cash from Sanbrado while advancing other assets, particularly the Kiaka project in Burkina Faso. If Kiaka ramps up as planned, West African Resources could move from being viewed mainly as a one-mine producer to a more meaningful multi-asset regional operator.
That shift is the main catalyst. A second large producing mine can change how a gold company is valued because it reduces dependence on a single operation, increases production scale, and can spread overhead across a broader asset base. The company has also benefited from a strong gold price environment, which can amplify the cash flow coming from each ounce produced and help fund development internally rather than relying too heavily on new debt or share issuance.
Recent operating updates and company communications have pointed to continued progress on expansion activities and production growth ambitions. In a business like this, the most significant opportunities often come from relatively simple drivers: bringing a new mine into production on time, keeping costs disciplined, and maintaining reserve life through exploration success near existing infrastructure. West African Resources has exposure to all three.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


