Stock Analysis · Waters Corporation (WAT)
Overview
Waters Corporation is a scientific instruments and software company focused on laboratories. Its products help customers separate, identify, and measure chemical and biological substances with high precision. In practical terms, Waters sells tools used in drug development, quality control, food testing, environmental analysis, and clinical research. The company operates in the diagnostics and research area of healthcare, but its customer base also extends into industrial and academic laboratories.
Its business is mainly organized around analytical instruments, recurring consumables, service, and a smaller microbiology-focused segment. Based on recent company reporting, revenue is concentrated in the following sources:
- Waters segment instruments: approximately 44% of revenue. This includes liquid chromatography systems, mass spectrometry instruments, thermal analysis tools, and related laboratory hardware.
- Recurring service revenue: approximately 29%. This includes maintenance contracts, qualification services, support, and repairs tied to the installed base of instruments.
- Recurring chemistry and consumables: approximately 21%. This covers columns, sample preparation products, and other laboratory supplies used repeatedly in testing workflows.
- TA instruments and software: approximately 6%. This includes thermal analysis, rheology, calorimetry, and software used in materials science and research applications.
- Clinical and microbiology products from Wyatt and BD Biosciences assets: still a smaller contribution, but strategically important as the company expands into adjacent testing markets.
That mix matters for long-term analysis because a meaningful share of Waters’ sales comes from recurring activity after the initial instrument sale. Once laboratories install a system, they often continue buying consumables, software, and service for years, which can make revenue more resilient than a pure equipment business.
The longer-term financial pattern also shows a business with consistently high gross profit, but with operating costs rising over time. Revenue moved from roughly $2.8 billion in 2021 to just over $3.1 billion in 2025, while net income stayed solid but did not rise at the same pace. That suggests the company still has attractive economics, yet margin expansion has become harder than it was earlier in the cycle.
Waters has maintained strong gross profitability over several years, which reflects the pricing power usually found in specialized laboratory tools and consumables. At the same time, selling, administrative, and research spending have climbed faster than ideal, which helps explain why earnings growth has been less impressive than revenue growth.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Diagnostics & Research | |
| Market Cap ⓘ | $43.14B | |
| Beta ⓘ | 1.19 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 111.24 | 24.06 |
| P/B Ratio ⓘ | 2.75 | 3.08 |
| FCF Yield ⓘ | 0.92% | 3.07% |
| Dividend Yield ⓘ | N/A | 2.05% |
| EBIT / EV ⓘ | 0.73% | 0.63% |
| PEG ⓘ | 1.57 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 113.40% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | 4.23% | 8.70% |
| EPS Growth (5Y CAGR) ⓘ | -17.88% | -18.20% |
| BVPS Growth (5Y CAGR) ⓘ | 64.03% | 3.95% |
| Margin Growth (5Y Trend) ⓘ | -5.10% | -0.58% |
| FCF Growth (5Y CAGR) ⓘ | -1.74% | 0.88% |
| DPS Growth (5Y CAGR) ⓘ | 140.37% | 6.80% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 2.49% | 3.29% |
| ROA (Latest) ⓘ | 1.12% | 3.02% |
| ROIC (5Y Median) ⓘ | 28.08% | 4.75% |
| ROA (5Y Median) ⓘ | 16.24% | 1.93% |
| Net Debt / EBIT (Latest) ⓘ | 13.97 | 1.33 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.33 | 1.83 |
| Net Debt / EBITDA (Latest) ⓘ | 5.26 | 0.99 |
| Net Debt / Assets ⓘ | 19.05% | 5.33% |
| EBITDA / Interest ⓘ | 6.48 | 9.63 |
| Operating Margin (Latest) ⓘ | 7.27% | 9.25% |
| Operating Margin (5Y Median) ⓘ | 28.55% | 7.80% |
| Debt to Equity (Latest) ⓘ | 34.58% | 28.99% |
| Profit Margin (Latest) ⓘ | 3.59% | 3.60% |
| Free Cash Flow (Latest) ⓘ | $398.45M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +57.30% | +37.48% |
| 12M Return (excl. last month) ⓘ | +34.47% | +20.85% |
| 6M Return ⓘ | +41.90% | +9.73% |
| Price vs. 200-Day MA ⓘ | +17.11% | +4.69% |
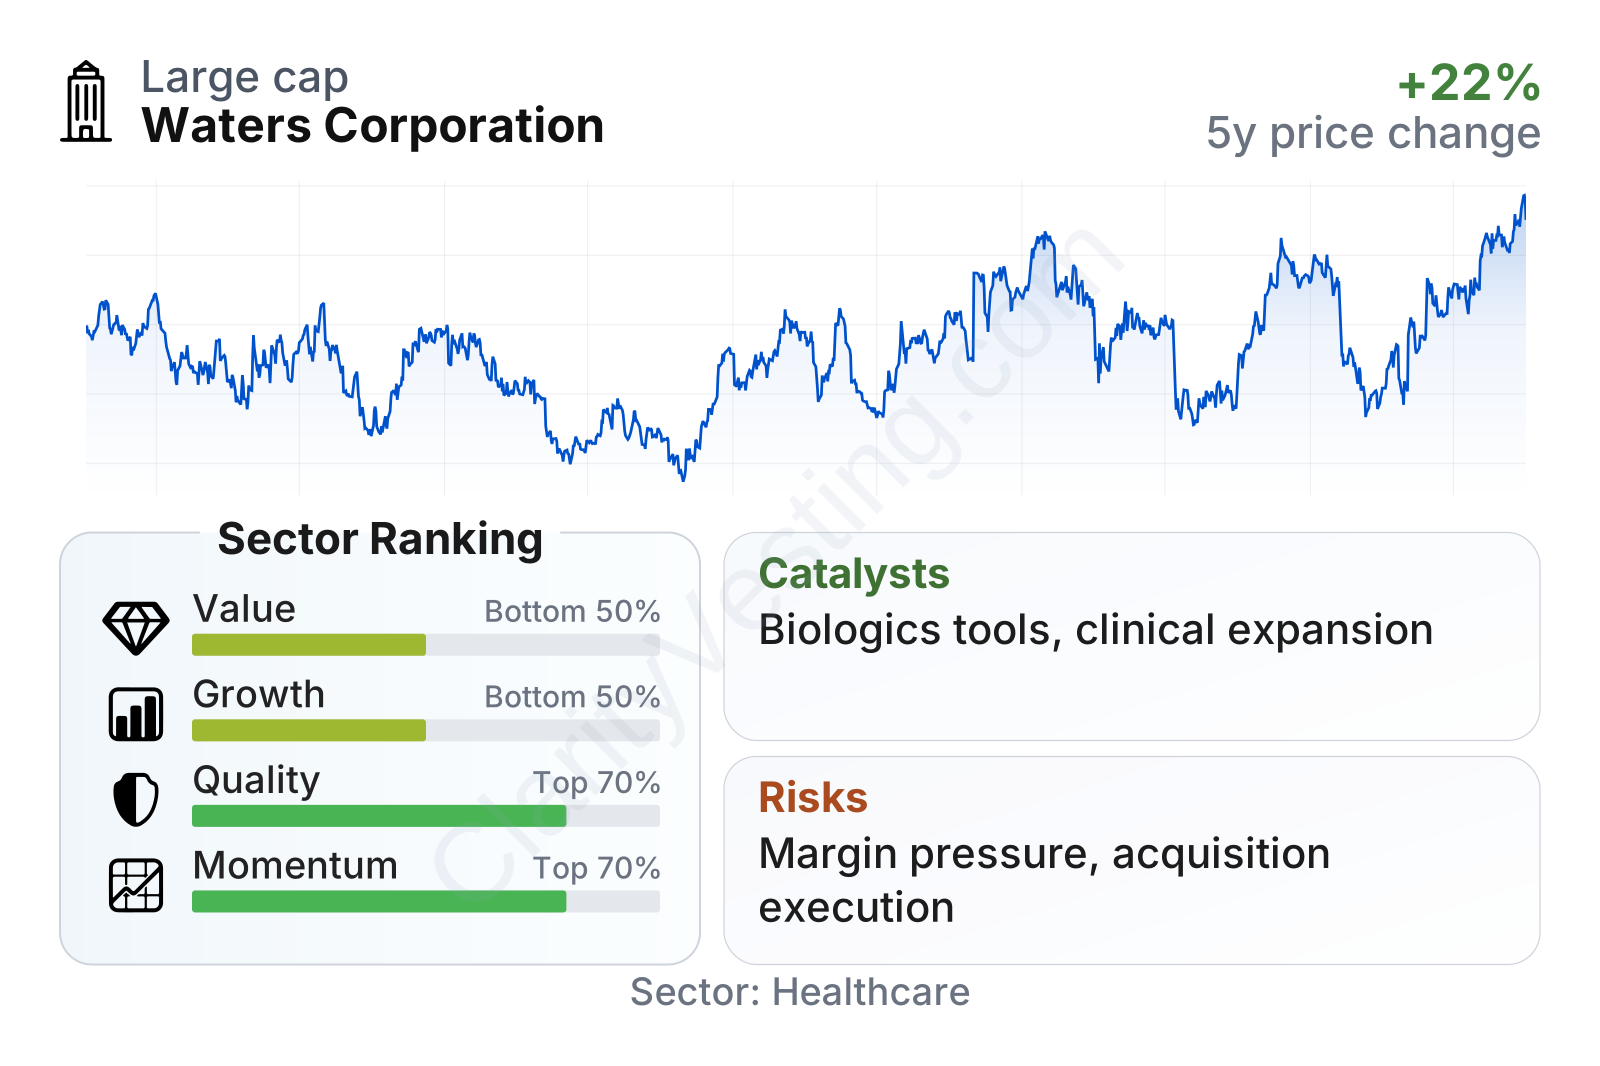
Waters is a large diagnostics and research company with a stock that has outperformed much of its sector over the last several years, but the underlying financial picture is more mixed than the share price alone suggests. The company ranks relatively well on quality and momentum, while value and growth metrics look less favorable versus the broader healthcare peer group. The most important takeaway is that the market is currently placing a premium on the durability of the franchise despite slower medium-term operating progress.
Growth
Waters operates in a sector with durable long-term demand. Pharmaceutical research, biologics, quality assurance, environmental testing, food safety, and regulated laboratory workflows all depend on highly precise analytical tools. These are not short-lived trends. Over time, more complex drugs, stricter manufacturing standards, and rising testing intensity tend to support demand for high-end chromatography, mass spectrometry, and software.
The company’s strategy also has a clear industrial logic. Waters has historically been strong in liquid chromatography and mass spectrometry, and it has been expanding into adjacent areas that can deepen customer relationships. Recent portfolio moves, including Wyatt’s analytical technologies and the acquisition of certain BD Biosciences assets, broaden its reach in bioanalytical characterization and clinical or microbiology-related applications. That can create more cross-selling opportunities and reduce dependence on any single laboratory budget cycle.
Recent sales growth has become much stronger after a softer period in 2023 and 2024. The sharp acceleration visible in 2026 likely reflects a step change rather than normal organic expansion, which points to portfolio additions and integration effects playing a major role. That is important because it means future comparisons may become tougher once the acquired revenue is fully absorbed.
Cash generation remains one of the company’s more attractive features, although it has become less steady recently. Waters has produced meaningful free cash flow over time, which gives it flexibility for debt repayment, acquisitions, and share repurchases. However, the latest trailing figure is notably below prior peaks, so the question is not whether the business can generate cash, but whether it can return to a stronger and more stable level as integration work and operating adjustments move forward.
A notable catalyst for future growth is the company’s deeper push into higher-growth testing categories such as biologics characterization, large molecule analysis, and regulated clinical laboratory workflows. Another potential support is the large installed base already in customer labs. Even when capital spending on new instruments slows, service and consumables can keep expanding as utilization rises. The company has also emphasized innovation in software-enabled workflows and instrument productivity, which matters because laboratories increasingly want automation, compliance support, and easier data handling rather than just standalone hardware.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


