Stock Analysis · Vertex Pharmaceuticals Inc (VRTX)
Overview
Vertex Pharmaceuticals is a biotechnology company focused on serious diseases where it believes it can make a large clinical difference. The business was built around cystic fibrosis, a rare genetic disease, and that remains the company’s economic engine. Over time, Vertex has expanded into other areas such as severe pain, kidney disease, and type 1 diabetes through internal research, partnerships, and acquisitions.
The company’s revenue is still highly concentrated in its cystic fibrosis medicines. Based on the latest annual results and company reporting, the main sources of revenue are approximately:
- Trikafta/Kaftrio: about 80% to 82% of total revenue. This is Vertex’s flagship cystic fibrosis treatment and by far its largest product.
- Symdeko/Symkevi: about 8% to 9%. Another cystic fibrosis therapy used in specific patient groups and markets.
- Orkambi: about 5% to 6%. An older cystic fibrosis medicine that still contributes meaningful sales.
- Kalydeco: about 4% to 5%. Vertex’s earlier cystic fibrosis treatment for certain mutations and age groups.
- Other revenue: currently less than 1%, including newer commercial products that are still at an early stage relative to the cystic fibrosis franchise.
This revenue mix shows a company with an exceptionally strong position in one specialized market, but also a business that is still in transition as it tries to build meaningful second and third growth pillars outside cystic fibrosis.
The multi-year income profile also shows a notable pattern: revenue has continued to rise, gross margins remain very strong, and research spending has stayed elevated. Profitability dipped sharply in 2024 because of large acquisition-related and development-related costs, but earnings recovered in 2025 as the core business kept expanding.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Biotechnology | |
| Market Cap ⓘ | $132.95B | |
| Beta ⓘ | 0.28 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 30.37 | 25.42 |
| P/B Ratio ⓘ | 6.76 | 3.08 |
| FCF Yield ⓘ | 2.86% | 3.12% |
| Dividend Yield ⓘ | N/A | 1.85% |
| EBIT / EV ⓘ | 4.23% | 0.56% |
| PEG ⓘ | 1.90 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 12.50% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | 12.57% | 8.60% |
| EPS Growth (5Y CAGR) ⓘ | -13.44% | -17.73% |
| BVPS Growth (5Y CAGR) ⓘ | 16.81% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | 1.70% | -0.57% |
| FCF Growth (5Y CAGR) ⓘ | 7.31% | 0.96% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.69% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 23.34% | 3.17% |
| ROA (Latest) ⓘ | 16.85% | 2.98% |
| ROIC (5Y Median) ⓘ | 23.22% | 4.56% |
| ROA (5Y Median) ⓘ | 17.71% | 1.87% |
| Net Debt / EBIT (Latest) ⓘ | -0.79 | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | -2.16 | 1.86 |
| Net Debt / EBITDA (Latest) ⓘ | -0.76 | 1.00 |
| Net Debt / Assets ⓘ | -15.19% | 5.06% |
| EBITDA / Interest ⓘ | N/A | 9.55 |
| Operating Margin (Latest) ⓘ | 41.84% | 9.25% |
| Operating Margin (5Y Median) ⓘ | 38.56% | 7.33% |
| Debt to Equity (Latest) ⓘ | 9.77% | 26.68% |
| Profit Margin (Latest) ⓘ | 35.00% | 3.34% |
| Free Cash Flow (Latest) ⓘ | $3.80B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +45.56% | +51.61% |
| 12M Return (excl. last month) ⓘ | +34.42% | +19.90% |
| 6M Return ⓘ | +22.28% | +10.10% |
| Price vs. 200-Day MA ⓘ | +12.15% | +6.44% |
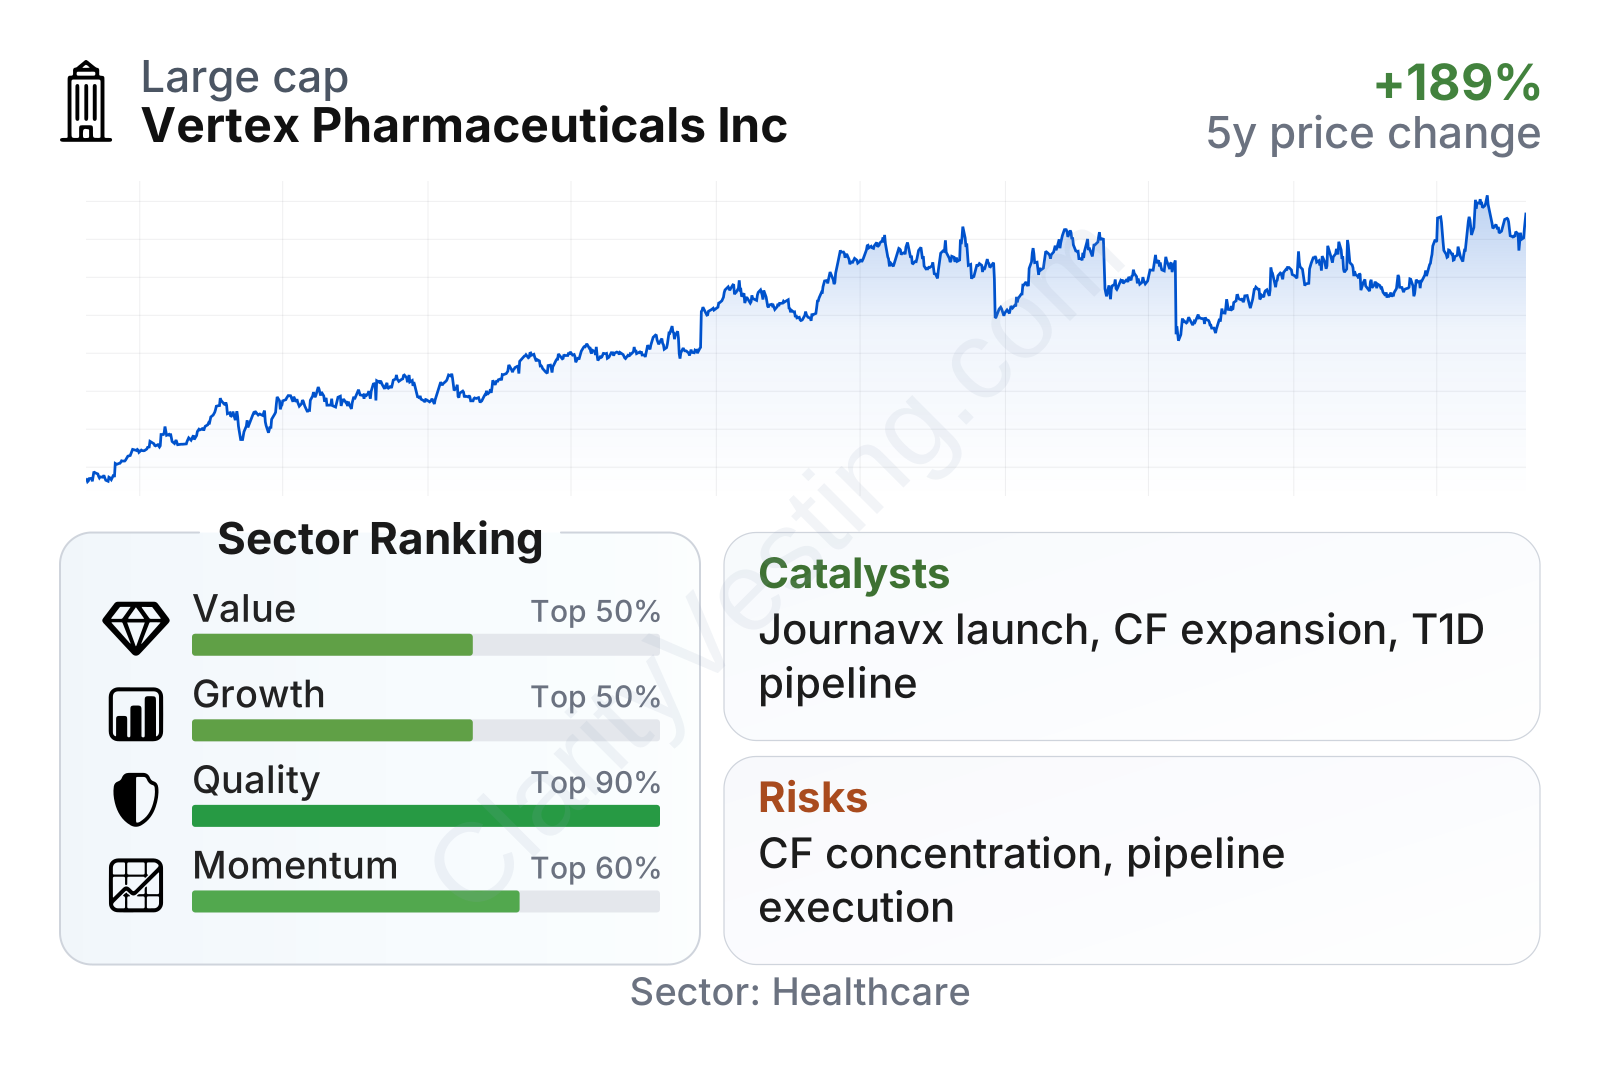
Vertex stands out as a very large biotechnology company with unusually strong quality metrics for its sector. Returns on capital and assets are far above typical biotech levels, margins are also much stronger than the industry median, and the balance sheet remains conservative. Growth has been solid rather than explosive, while valuation sits somewhat above sector medians on earnings and book value multiples. The overall picture is a financially strong business that the market already recognizes as higher quality than many peers.
Growth
Biotechnology remains a structurally growing sector because demand for advanced treatments is supported by aging populations, better diagnosis, broader access to specialty medicines, and continuing scientific progress in genetic and precision medicine. Vertex is especially exposed to one of the more durable parts of that trend: high-value therapies for severe diseases with limited treatment options.
Its strategy for future growth is straightforward and logical. The company is defending and extending its cystic fibrosis franchise while trying to create new revenue platforms in adjacent high-need areas. That matters because Vertex already has very deep relationships with specialists, global commercial capabilities in rare disease, and strong cash generation to fund more research. In simple terms, the company is using the cash from an established leadership position to finance the next generation of products.
Revenue growth has moderated from the very strong gains seen earlier in the decade, but it has remained positive and generally ahead of the healthcare sector median. That suggests Vertex is no longer in its fastest expansion phase, yet it is still delivering healthy top-line progress for a company of its size.
Cash generation reinforces that view. Free cash flow has mostly stayed in the multi-billion-dollar range, with a temporary setback during the period affected by heavier investment and transaction activity. The rebound afterward indicates that the underlying business remains highly cash generative, which is important because biotechnology pipelines often require patience and significant spending before new products contribute at scale.
The strongest current catalysts are tied to diversification beyond cystic fibrosis. Vertex has been advancing its acute pain medicine Journavx, which gives the company entry into a very large market outside rare disease. It also has major long-term optionality in gene-edited and cell-based therapies, particularly in type 1 diabetes through islet cell programs, though these opportunities are earlier and carry more execution risk. In addition, continued geographic expansion and broader patient eligibility in cystic fibrosis can still support incremental growth even in a mature franchise.
Recent company updates have also pointed to continued progress in commercial launches and pipeline development. For long-term analysis, the key significance is not one quarter of sales variation, but whether Vertex can prove that at least one non-cystic-fibrosis product can become a durable multi-billion-dollar business. That is the main bridge from a dominant single-franchise biotech to a broader rare-disease and specialty-medicine platform.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


