Stock Analysis · Vertiv Holdings Co (VRT)
Overview
Vertiv Holdings Co designs and services the equipment that keeps digital infrastructure running. Its products are used in data centers, communication networks, and industrial facilities where power must stay stable, heat must be removed, and operations must continue even during outages. In simple terms, Vertiv helps customers keep critical computing and networking equipment powered, cooled, monitored, and maintained.
The business is closely tied to the buildout of modern digital infrastructure. Demand comes from hyperscale data centers, enterprise server rooms, telecom networks, and industrial sites. The company operates globally and combines equipment sales with installation, lifecycle services, software, and aftermarket support, which helps create recurring revenue beyond the initial hardware sale.
Based on the company’s latest annual disclosures, revenue is mainly organized by product and service categories rather than by a very detailed public line-item split. The broad mix can be summarized as follows:
- Power management and power infrastructure: approximately 45% to 55% of revenue. This includes uninterruptible power supplies, switchgear, busways, power distribution units, and related systems used to protect uptime.
- Thermal management: approximately 30% to 40% of revenue. This includes precision cooling, heat rejection, and liquid cooling solutions used in high-density computing environments.
- Services and software: approximately 15% to 25% of revenue. This includes maintenance, monitoring, project services, spare parts, and other lifecycle support.
Geographically, Vertiv is also diversified, with revenue spread across the Americas, Asia Pacific, and Europe, Middle East and Africa. That matters because data center spending is a global trend rather than a single-country opportunity.
The company’s recent financial progression has been notable. Revenue has moved from about $5.0 billion in 2021 to more than $10.2 billion in 2025, while operating income expanded much faster than sales. That suggests Vertiv is not only growing, but also improving pricing, mix, and efficiency at the same time.
The flow of revenue and costs shows a clear shift over the past few years: sales have roughly doubled since 2021, while operating income and net income have risen much faster. Gross profit has widened materially, and interest expense has fallen from earlier peaks, which points to a business that has become more efficient and financially stronger.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Electrical Equipment & Parts | |
| Market Cap ⓘ | $78.37B | |
| Beta ⓘ | 2.05 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 46.05 | 22.29 |
| P/B Ratio ⓘ | 17.51 | 1.98 |
| FCF Yield ⓘ | 3.73% | 6.26% |
| Dividend Yield ⓘ | 0.08% | 1.92% |
| EBIT / EV ⓘ | 2.26% | 4.83% |
| PEG ⓘ | 0.84 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 24.10% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 16.83% | 7.76% |
| EPS Growth (5Y CAGR) ⓘ | 54.25% | -13.17% |
| BVPS Growth (5Y CAGR) ⓘ | 26.12% | 6.13% |
| Margin Growth (5Y Trend) ⓘ | 12.73% | 0.74% |
| FCF Growth (5Y CAGR) ⓘ | 96.61% | 10.79% |
| DPS Growth (5Y CAGR) ⓘ | 99.85% | 9.41% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 25.20% | 10.75% |
| ROA (Latest) ⓘ | 12.97% | 5.41% |
| ROIC (5Y Median) ⓘ | 11.50% | 9.37% |
| ROA (5Y Median) ⓘ | 5.79% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | 0.24 | 2.04 |
| Net Debt / EBIT (5Y Median) ⓘ | 3.29 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 0.21 | 1.39 |
| Net Debt / Assets ⓘ | 3.32% | 19.27% |
| EBITDA / Interest ⓘ | N/A | 9.58 |
| Operating Margin (Latest) ⓘ | 18.87% | 10.49% |
| Operating Margin (5Y Median) ⓘ | 10.40% | 10.30% |
| Debt to Equity (Latest) ⓘ | 70.17% | 64.82% |
| Profit Margin (Latest) ⓘ | 15.09% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $2.92B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +479.67% | +67.77% |
| 12M Return (excl. last month) ⓘ | +74.88% | +12.05% |
| 6M Return ⓘ | -32.07% | 0.00% |
| Price vs. 200-Day MA ⓘ | -21.06% | +0.67% |
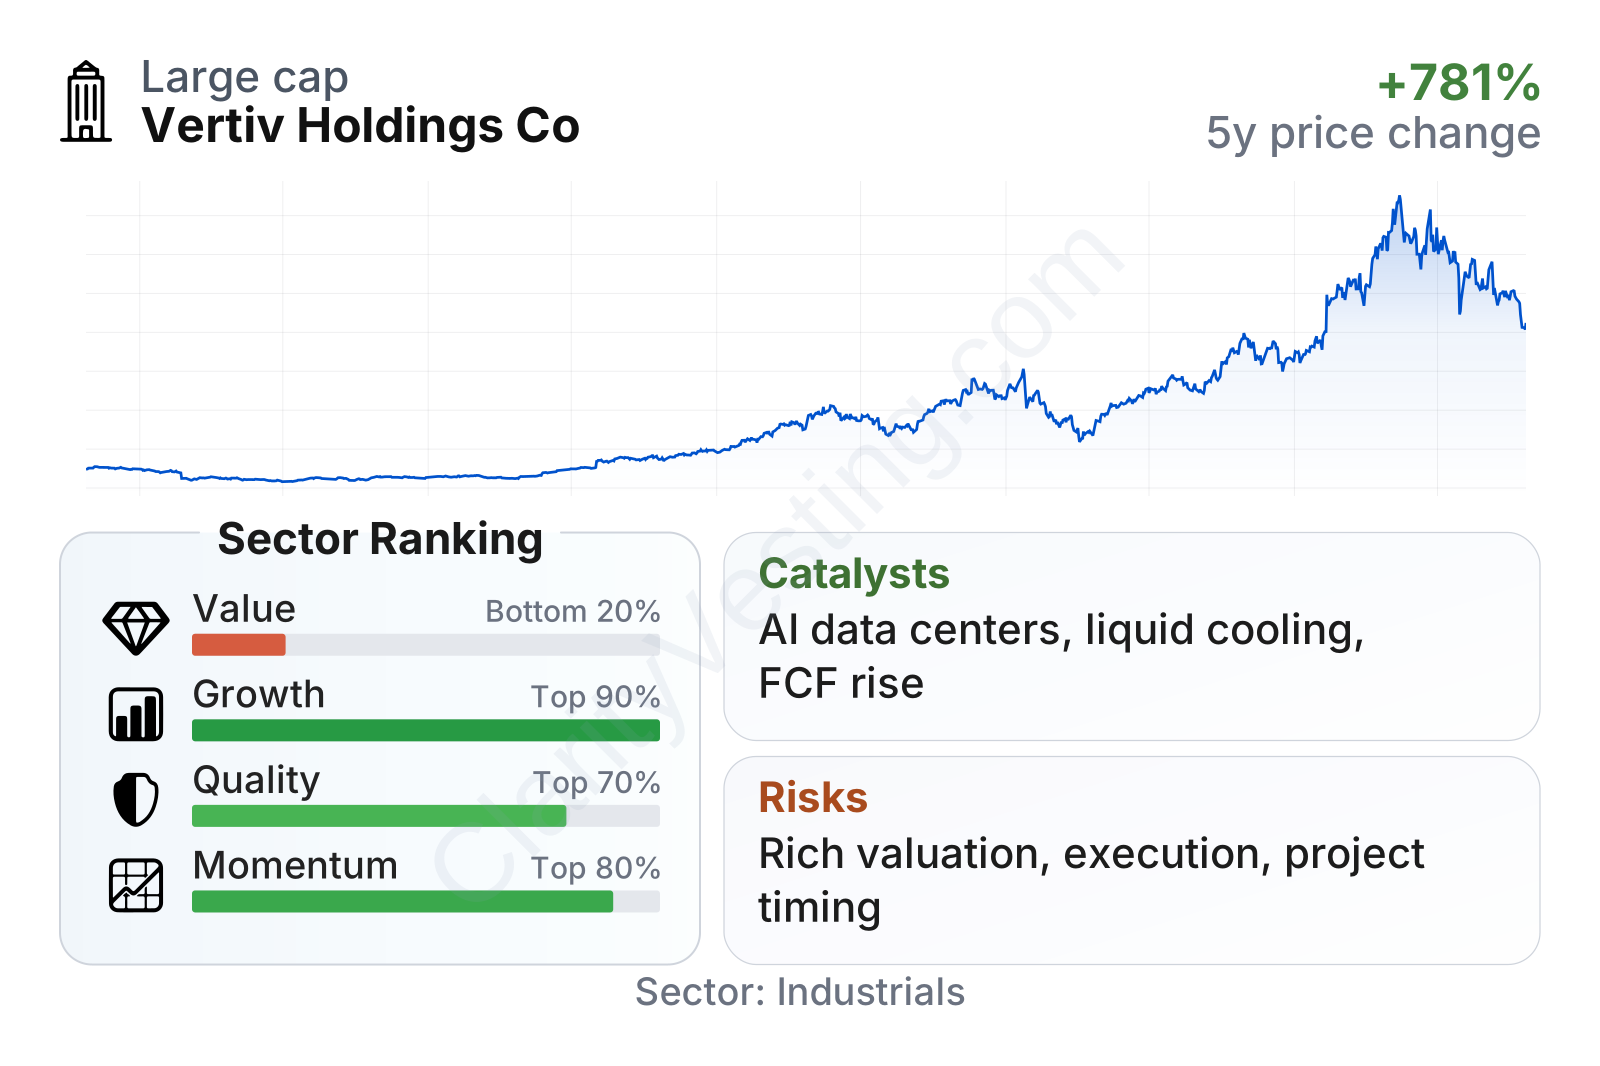
Vertiv stands out for strong growth, improving quality, and exceptional long-term share price momentum, but it does not screen as cheap. The company ranks near the top of its sector on growth and momentum, while profitability and returns on capital are also comfortably above industry norms. The tradeoff is valuation: earnings and book-value multiples are far above the sector median, and the dividend yield is minimal. In other words, the market is already recognizing the company’s improved business profile.
Another important point is volatility. Vertiv is a very large company, but its beta is above 2, which means the stock has tended to move much more sharply than the broader market. That does not change the business fundamentals, but it does affect how the stock behaves in periods of market stress or changing sentiment.
Growth
Vertiv operates in one of the strongest infrastructure themes in the market: the expansion of data centers and the rising power and cooling needs created by artificial intelligence workloads. As computing density increases, customers need more advanced electrical and thermal systems. This is exactly where Vertiv is positioned. AI servers consume more electricity and generate more heat than traditional installations, which increases the value of high-performance power architecture and liquid cooling solutions.
The company’s strategy appears aligned with that demand. Vertiv has been pushing into higher-value solutions, especially in thermal management for dense computing environments, while also strengthening service capabilities. This mix matters because services can deepen customer relationships and support more stable revenue through maintenance and upgrades.
Revenue growth has remained consistently strong, often well above the sector median, and recent annual growth has stayed in the 20% to 35% range. That is a powerful signal that Vertiv is benefiting from structural demand rather than a short-lived rebound.
Cash generation has improved dramatically. Free cash flow was negative earlier in the cycle, then turned strongly positive and climbed above $2 billion on a trailing basis. That is important because it shows growth is not coming only from accounting profits; the business is increasingly converting sales into real cash that can support debt reduction, investment, and financial flexibility.
A recent and important opportunity comes from industry-wide AI infrastructure spending. Public company commentary from Vertiv and major computing and data center ecosystem participants has pointed to continued demand for high-density power and cooling deployments. Vertiv has also highlighted a growing pipeline tied to liquid cooling and next-generation data center architecture. That does not guarantee a straight line upward, but it does reinforce that the company’s products are tied to one of the most capital-intensive areas of digital infrastructure.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


