Stock Analysis · Valeura Energy Inc (VLERF)
Overview
Valeura Energy Inc. is an upstream oil and gas company focused on Southeast Asia, with producing assets mainly in the Gulf of Thailand and additional exploration acreage in Thailand, Türkiye, and Egypt. In simple terms, it finds, develops, and produces hydrocarbons, then sells that production into regional energy markets. The company changed shape materially after acquiring producing Thai assets in 2023, moving from a smaller exploration-oriented profile to a cash-generating producer.
The business is now driven primarily by crude oil and natural gas output from its Thai fields. Based on recent annual reporting, revenue is heavily concentrated in Thailand and in petroleum sales, while exploration assets outside Thailand contribute little or no meaningful revenue at this stage.
- Crude oil sales in Thailand: approximately 70% to 80% of revenue. This comes from offshore fields where Valeura produces and sells oil cargoes.
- Natural gas sales in Thailand: approximately 20% to 30% of revenue. This includes gas produced alongside oil and sold under local arrangements.
- Condensate and other petroleum-related sales: a small share of revenue, likely below 10% depending on the period and field mix.
- Exploration portfolio in Türkiye and Egypt: currently strategic rather than revenue-generating, with value tied to future drilling results or portfolio development.
One notable financial change is how sharply the company’s earnings profile improved after the Thai acquisitions. Revenue and gross profit scaled up quickly from 2023 onward, although net income became more uneven in 2025 as oil prices, lifting patterns, and non-cash charges affected results.
The operating picture changed dramatically after 2022: the company moved from minimal revenue and losses to a much larger production base with substantial gross profit. More recently, revenue stayed sizable, but net income became far less consistent, showing how sensitive results remain to commodity prices, cargo timing, and accounting effects.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Energy | |
| Industry | Oil & Gas E&P | |
| Market Cap ⓘ | $1.24B | |
| Beta ⓘ | -1.59 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 20.05 | 15.44 |
| P/B Ratio ⓘ | 2.06 | 1.73 |
| FCF Yield ⓘ | 10.18% | 8.20% |
| Dividend Yield ⓘ | N/A | 3.59% |
| EBIT / EV ⓘ | 13.74% | 7.46% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 101.00% | 26.90% |
| RPS Growth (5Y CAGR) ⓘ | 253.41% | 6.90% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -15.73% |
| BVPS Growth (5Y CAGR) ⓘ | 79.26% | 6.07% |
| Margin Growth (5Y Trend) ⓘ | 152.74% | 0.58% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 1.86% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 16.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 17.15% | 11.40% |
| ROA (Latest) ⓘ | 6.99% | 6.06% |
| ROIC (5Y Median) ⓘ | 18.56% | 10.30% |
| ROA (5Y Median) ⓘ | 2.61% | 5.42% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.64 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.83 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 1.08 |
| Net Debt / Assets ⓘ | N/A | 17.29% |
| EBITDA / Interest ⓘ | 24.19 | 9.64 |
| Operating Margin (Latest) ⓘ | 18.53% | 16.27% |
| Operating Margin (5Y Median) ⓘ | 16.22% | 20.39% |
| Debt to Equity (Latest) ⓘ | N/A | 54.76% |
| Profit Margin (Latest) ⓘ | 9.25% | 8.82% |
| Free Cash Flow (Latest) ⓘ | $125.78M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +420.00% | +67.38% |
| 12M Return (excl. last month) ⓘ | +99.51% | +49.19% |
| 6M Return ⓘ | +24.18% | +7.07% |
| Price vs. 200-Day MA ⓘ | +32.66% | +9.56% |
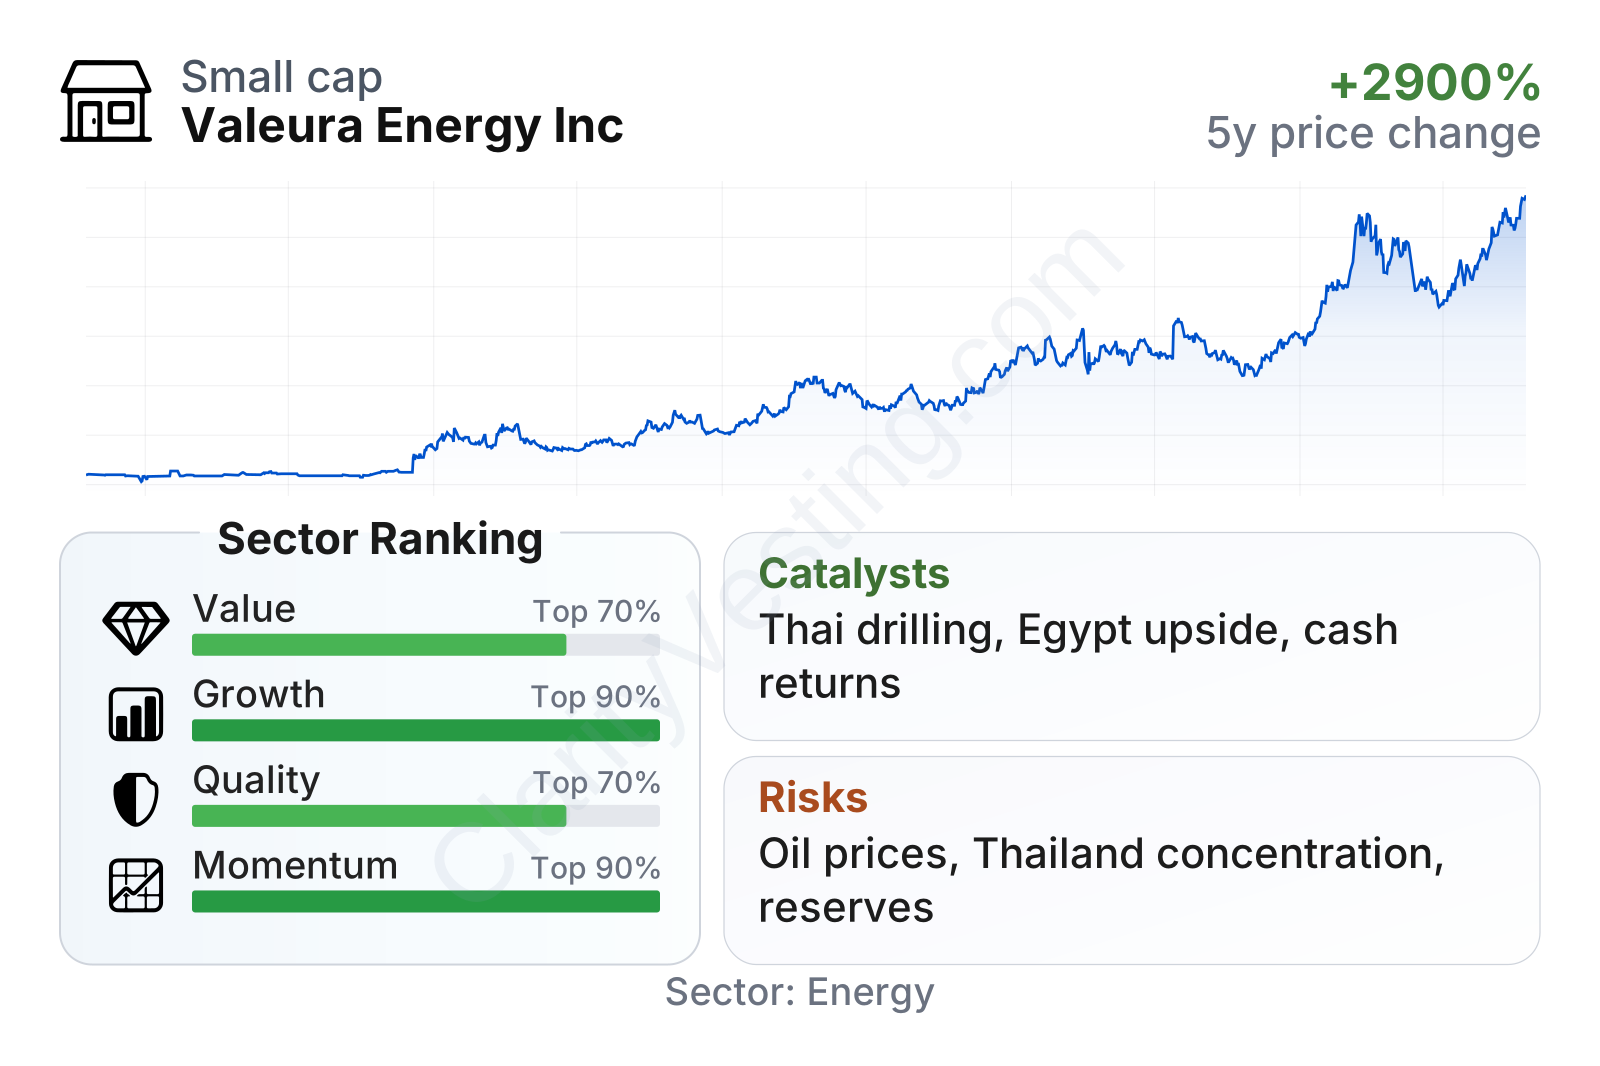
Valeura sits in the higher end of the sector on growth and momentum, while value and quality are also better than many peers, though not at the very top. The market is assigning a somewhat richer earnings multiple than the sector median, but that is partly supported by strong free cash flow yield, solid returns on capital, and relatively strong interest coverage. The company is mid-sized within its niche rather than a major integrated energy group, which makes operational progress more visible in the share price.
The long-term stock chart reflects that re-rating clearly. After trading at very low levels in 2021 and 2022, the shares climbed sharply through 2023 to 2026 as the company transformed into a profitable producer. That kind of move can indicate improving fundamentals, but it also means expectations are no longer as low as they once were.
Growth
Valeura operates in a sector that is mature globally but still relevant in Southeast Asia, where domestic production remains important for energy security and where existing offshore infrastructure can support additional field development. This matters because companies with established producing hubs can sometimes add lower-risk growth through infill drilling, workovers, and tie-backs rather than relying only on large frontier discoveries.
The company’s current strategy is fairly easy to understand: generate cash from producing Thai assets, optimize output through development drilling, and keep exploration exposure that could add upside without dominating the financial profile. That approach is more balanced than a pure exploration model because it combines current cash generation with optional future discoveries.
Revenue growth has been volatile quarter to quarter, which is normal for a smaller producer that sells output in cargoes and is exposed to oil price swings. Even so, the latest year-over-year rebound is very strong, and the broader multi-year growth profile is far ahead of the sector median. That suggests the company is still benefiting from the step-change created by its asset base expansion.
Cash generation also improved materially after the transformation of the business. Free cash flow moved from negative levels in earlier periods to clearly positive territory, although it has pulled back from its recent high. For a long-term assessment, the key point is that Valeura now appears capable of funding operations, development spending, and shareholder distributions from internally generated cash when commodity conditions are supportive.
Recent company updates have also pointed to development drilling and field optimization in Thailand as important catalysts. In this type of business, production gains from successful wells can feed through quickly to cash flow because much of the infrastructure is already in place. In addition, any commercial progress in the exploration portfolio, especially in Egypt or Türkiye, could create upside that is not central to current production economics.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


