Stock Analysis · United States Lime & Minerals Inc (USLM)
Overview
United States Lime & Minerals Inc. is a U.S. producer of lime and limestone products. These materials are used in construction, road building, environmental treatment, industrial processes, and oil and gas services. The company operates lime and limestone plants and quarries in Arkansas, Colorado, Louisiana, Oklahoma, and Texas, and it also has natural gas interests through royalty and working interests located mainly in Texas.
The business is fairly simple to understand: it extracts stone, processes it into lime and other products, and sells those materials to customers that need them for infrastructure, manufacturing, and energy-related activity. Lime is an essential input in many heavy industries, which gives the company exposure to basic economic activity rather than consumer trends.
Based on recent annual reporting, revenue is concentrated in two main streams:
- Lime and limestone operations: approximately 95% to 97% of total revenue. This includes quicklime, hydrated lime, limestone, and related products sold to construction, environmental, industrial, and oil and gas customers.
- Natural gas royalties and working interests: approximately 3% to 5% of total revenue. This comes from the company’s interests in gas wells and depends largely on production volumes and natural gas prices.
Within the core lime and limestone segment, the largest end markets have historically included construction-related demand, environmental uses, and oil and gas services, though exact percentages by end market are not always disclosed with enough precision to present a reliable breakdown.
What stands out is how dominant the core materials business is. The gas-related activity can add profit and cash flow, but the long-term case is mainly tied to the company’s ability to grow pricing, maintain quarry and kiln efficiency, and benefit from infrastructure and industrial demand.
The business has become meaningfully more profitable over the last several years. Revenue has expanded steadily, but operating income and net income have grown even faster, showing that pricing and cost control have improved at the same time.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Building Materials | |
| Market Cap ⓘ | $3.05B | |
| Beta ⓘ | 0.65 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 22.79 | 16.90 |
| P/B Ratio ⓘ | 4.34 | 1.65 |
| FCF Yield ⓘ | 3.01% | 5.76% |
| Dividend Yield ⓘ | 0.22% | 2.13% |
| EBIT / EV ⓘ | 5.90% | 6.30% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 8.30% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | 18.06% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | -28.63% | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | 22.29% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | 21.17% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 41.14% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 16.98% | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 20.35% | 9.26% |
| ROA (Latest) ⓘ | 19.20% | 4.91% |
| ROIC (5Y Median) ⓘ | 20.88% | 7.70% |
| ROA (5Y Median) ⓘ | 18.44% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | -2.36 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | -2.15 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | -2.05 | 0.95 |
| Net Debt / Assets ⓘ | -53.44% | 13.69% |
| EBITDA / Interest ⓘ | N/A | 12.34 |
| Operating Margin (Latest) ⓘ | 44.81% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 33.19% | 11.80% |
| Debt to Equity (Latest) ⓘ | 0.47% | 40.56% |
| Profit Margin (Latest) ⓘ | 35.66% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $91.81M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +153.96% | +68.89% |
| 12M Return (excl. last month) ⓘ | -7.91% | +30.21% |
| 6M Return ⓘ | -23.53% | -4.16% |
| Price vs. 200-Day MA ⓘ | -9.58% | -1.27% |
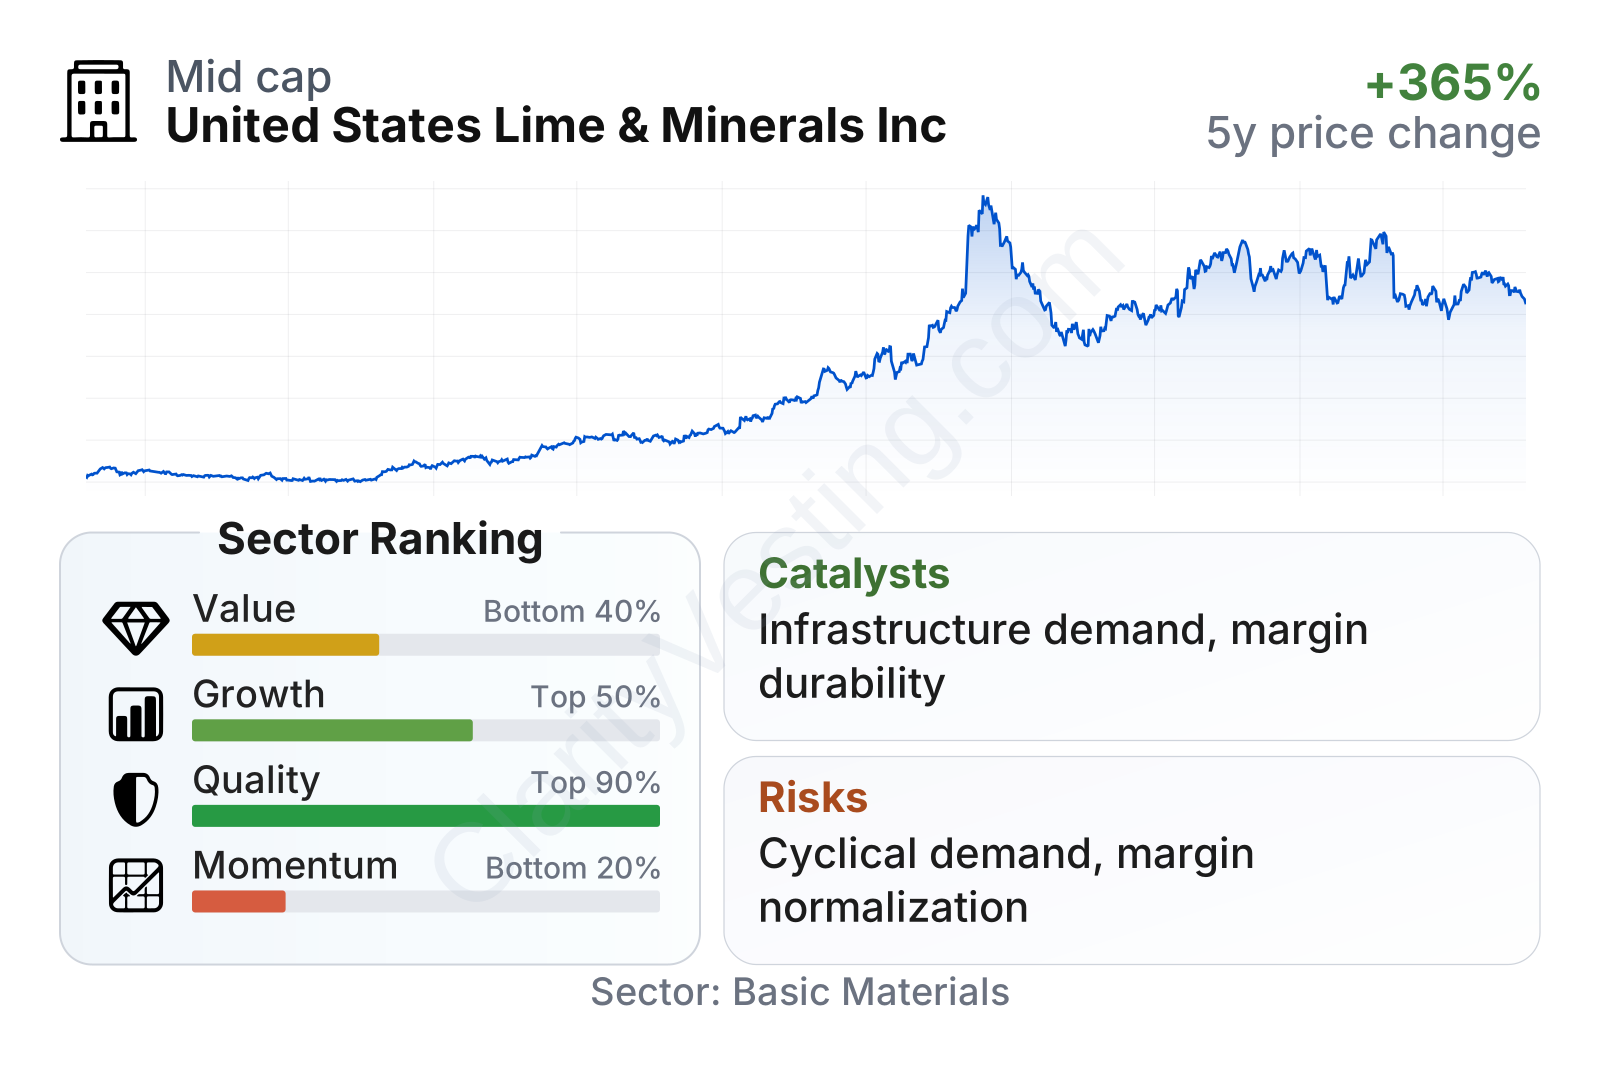
United States Lime & Minerals is a mid-sized company with unusually strong quality metrics for the building materials space. Profitability, returns on capital, and balance-sheet strength are all well above sector norms. Growth metrics are mixed in the short term but remain solid over a multiyear period, while valuation measures sit on the richer side of the sector. Recent share-price momentum has cooled after a very strong multiyear run.
The stock’s long-term performance has been exceptional, with the share price rising several times over since 2021, although the most recent months show a notable pullback from the highs. That matters because it suggests the market has already recognized the company’s stronger earnings profile, even if near-term enthusiasm has moderated.
Growth
United States Lime & Minerals operates in a sector that is mature but still capable of durable growth. Demand for lime and limestone is supported by construction activity, public infrastructure work, environmental regulation, industrial production, and drilling-related services. This is not a high-tech market, but it is an essential-input market, which can still produce attractive long-term expansion when a company controls good reserves, runs efficient plants, and serves local markets where transportation costs matter.
The company’s recent trajectory supports that view. Revenue growth has remained positive overall, even though the pace has become less consistent quarter to quarter as comparisons have become tougher.
The bigger point is not just that sales increased, but that the business has been able to convert that growth into much stronger profitability. Over the last five years, revenue per share, book value per share, operating margin, and free cash flow have all grown much faster than the sector median, which suggests expansion has been driven by real business improvement rather than only by cyclical pricing.
Cash generation has also moved sharply higher over time. Even after some moderation from peak levels, free cash flow remains far above where it stood a few years ago. That gives the company flexibility to fund capital spending, preserve a conservative balance sheet, and continue regular dividends without relying on outside financing.
The strategy for future growth appears sensible. Lime and limestone are heavy, low-value-per-ton products relative to transportation cost, so regional production footprints and proximity to customers matter. Companies with established quarries, kilns, and reserves can defend their position and benefit when local demand strengthens. For United States Lime & Minerals, that can translate into further gains from pricing discipline, plant utilization, and selective capacity investment rather than constant acquisitions.
A meaningful catalyst is continued U.S. infrastructure and nonresidential construction activity, especially in states where the company already operates. Environmental applications also remain important because lime is used in water treatment, emissions control, and other compliance-related processes. If industrial and energy activity stay healthy in its operating regions, the company can continue to benefit from a mix of volume support and pricing strength.
Recent corporate updates have also highlighted ongoing operating strength rather than distress. There has been no obvious sign in public filings of a major strategic disruption, and the company continues to post margins that are rare for its industry.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


