Stock Analysis · Americas Silver Corp (USAS)
Overview
Americas Silver Corp is a North American mining company focused on producing silver and zinc, with additional exposure to lead, copper, and gold. Its assets are located mainly in the United States and Canada. For long-term readers, the key point is that this is not a diversified global mining giant; it is a smaller metals producer whose results can change sharply depending on mine performance, metal prices, and project execution.
The company’s revenue comes primarily from selling concentrates and ore containing several metals. Based on recent annual results, the business mix is centered on base metals rather than pure silver exposure, even though silver remains an important part of the company’s identity and investment appeal.
- Zinc: approximately 35% to 45% of revenue. This is typically the largest contributor, mainly tied to production from the Galena complex and other polymetallic operations.
- Silver: approximately 20% to 30% of revenue. This includes payable silver produced from the company’s mining operations and is the metal most directly linked to the company’s market profile.
- Lead: approximately 15% to 25% of revenue. Lead is usually a meaningful by-product in polymetallic deposits and helps support overall mine economics.
- Copper: approximately 5% to 15% of revenue. Copper exposure has become more relevant with asset positioning and can add upside when industrial metal prices strengthen.
- Gold and other: usually a smaller share. This includes gold and other payable metals recovered from ore processing.
Operationally, Americas Silver has been reshaping itself around the Galena Complex in Idaho and the newly added Cosalá operations in Mexico through the acquisition of Sierra Madre Gold and Silver. That matters because the company is moving from a difficult multi-year turnaround period toward a broader operating base with more production sources.
The long-running pattern has been weak profitability despite rising revenue. Revenue improved notably from 2021 through 2025, but costs absorbed most of that benefit, and operating losses remained large. The one encouraging change is that gross profit turned positive in 2025, suggesting that mine-level economics may be improving even if corporate-level profitability is still not there.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Other Industrial Metals & Mining | |
| Market Cap ⓘ | $1.36B | |
| Beta ⓘ | 2.25 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 16.90 |
| P/B Ratio ⓘ | 4.12 | 1.65 |
| FCF Yield ⓘ | -5.12% | 5.76% |
| Dividend Yield ⓘ | N/A | 2.13% |
| EBIT / EV ⓘ | -1.25% | 6.30% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 72.10% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | -13.66% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | -15.68% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | N/A | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -7.43% | 9.26% |
| ROA (Latest) ⓘ | -14.54% | 4.91% |
| ROIC (5Y Median) ⓘ | -35.45% | 7.70% |
| ROA (5Y Median) ⓘ | -24.09% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | -11.40 | 0.95 |
| Net Debt / Assets ⓘ | -7.67% | 13.69% |
| EBITDA / Interest ⓘ | 0.55 | 12.34 |
| Operating Margin (Latest) ⓘ | -10.79% | 13.20% |
| Operating Margin (5Y Median) ⓘ | -46.66% | 11.80% |
| Debt to Equity (Latest) ⓘ | 18.83% | 40.56% |
| Profit Margin (Latest) ⓘ | -26.28% | 6.43% |
| Free Cash Flow (Latest) ⓘ | -$69.55M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +348.48% | +68.89% |
| 12M Return (excl. last month) ⓘ | +68.18% | +30.21% |
| 6M Return ⓘ | -38.64% | -4.16% |
| Price vs. 200-Day MA ⓘ | -36.49% | -1.27% |
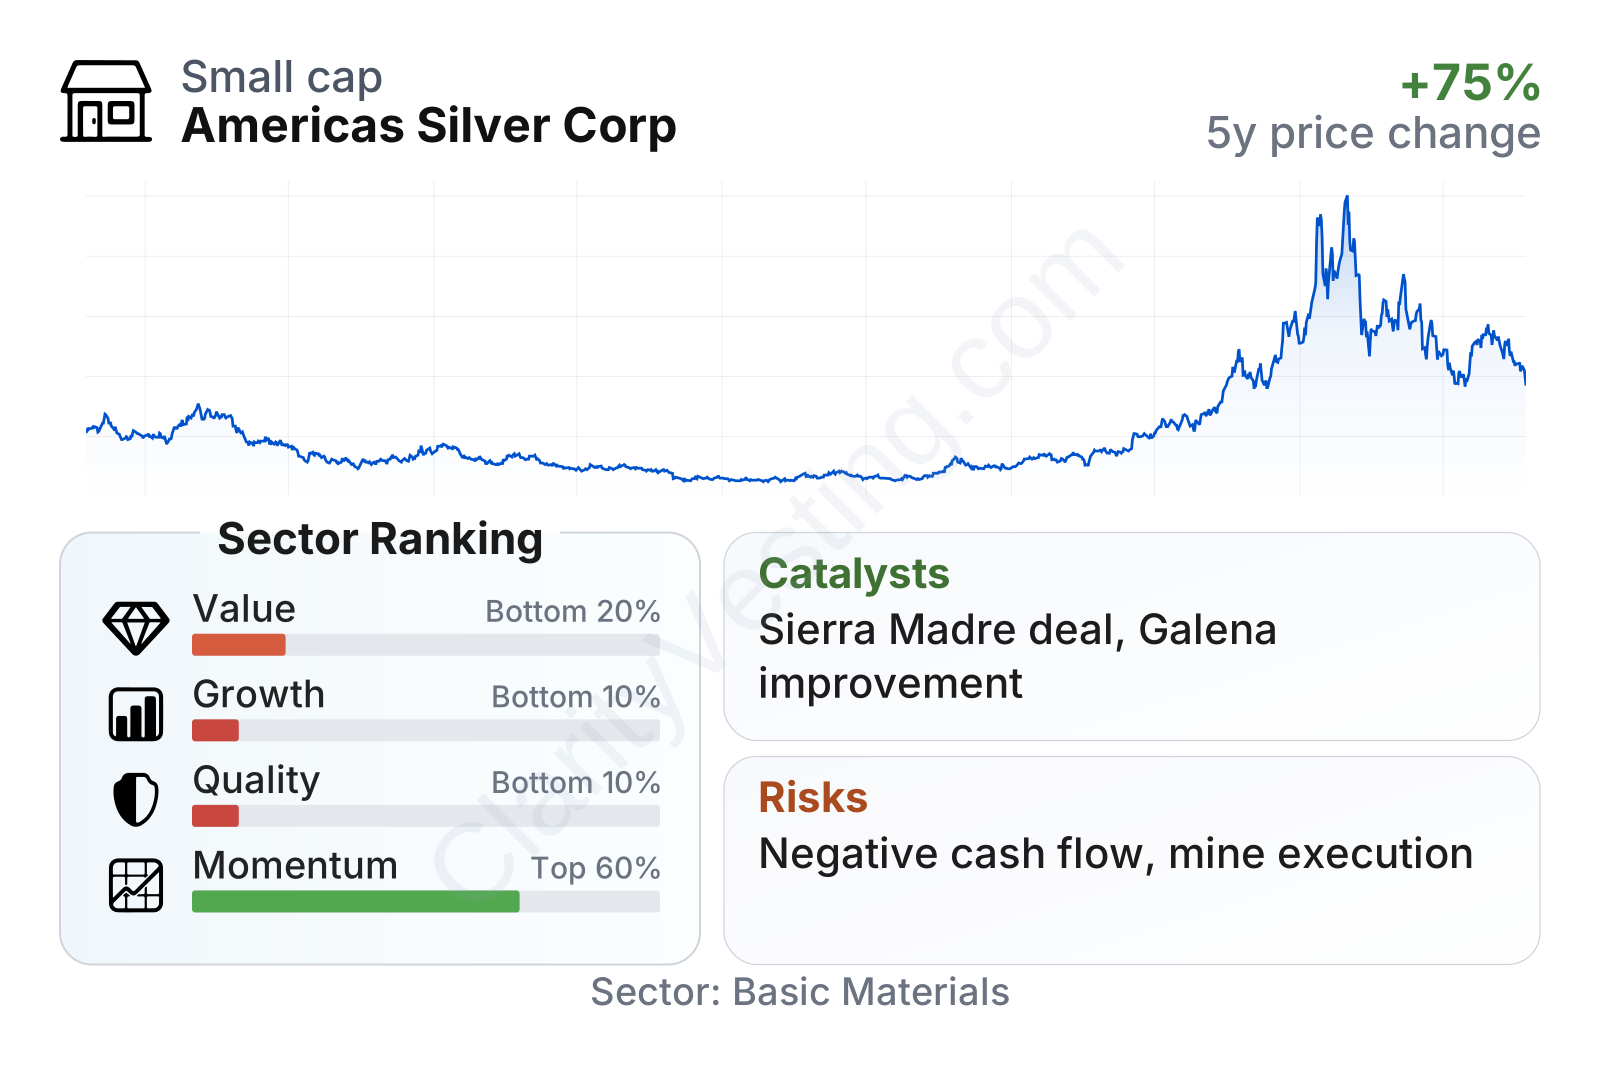
The market is treating Americas Silver as a higher-risk metals name. The company’s share price has risen very strongly over the last three years, but volatility is high, with a beta above 2. In the factor breakdown, value, quality, and long-term growth rank in the lower end of the sector, while momentum is better than average. In simple terms, the stock has benefited from improving sentiment and major corporate changes, but the underlying business still shows weak profitability, negative free cash flow, and returns on capital well below sector norms.
Growth
Americas Silver operates in a sector with long-term relevance. Silver benefits from both precious-metals demand and industrial uses such as solar applications and electronics, while zinc, copper, and lead are tied to construction, infrastructure, and electrification. That does not guarantee smooth growth, but it does mean the company is exposed to metals that remain important in the global economy.
The company’s strategy for future growth is centered on two ideas: improving the performance of existing mines and broadening its production base through acquisitions. The Sierra Madre transaction is especially important because it brings the producing Guitarra mine and district into the portfolio. For a company of this size, adding a producing asset can be more meaningful than for a large miner because it can materially change total output, asset diversification, and market visibility.
Recent revenue growth has been highly uneven but clearly stronger in the most recent periods. The latest year-over-year figures are far above the sector median, which points to a real step-up in business activity rather than a stable, mature production profile. That said, the five-year picture remains weak, showing that growth has not yet been consistent enough to erase the company’s earlier setbacks.
Cash generation remains the main missing piece. Free cash flow has stayed negative and has worsened recently, which suggests that the company is still in a capital-heavy phase and has not yet converted higher revenue into self-funding growth. For a miner, this often happens when spending is needed to restart, develop, or integrate assets, but it also raises the standard the company must meet over the next few reporting periods.
A major recent catalyst is the completion of the Sierra Madre Gold and Silver combination in 2025, which created a larger silver-focused platform with operations in multiple jurisdictions. In addition, company updates around Galena have highlighted improvement initiatives, including higher-grade mining areas and operational optimization. If these efforts translate into steadier production and lower unit costs, the company’s earnings profile could look very different from its historical record.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


