Stock Analysis · Uni-President China Holdings Ltd (UPCHY)
Overview
Uni-President China Holdings Ltd is a packaged food and beverage company focused on mainland China. It is best known for ready-to-drink tea, juices, bottled water, milk beverages, coffee drinks, and instant noodles. The company operates in everyday consumer categories, which usually makes demand steadier than in more cyclical industries because people continue to buy drinks and convenient meals even during weaker economic periods.
Its business mix is led by beverages, with food as the second pillar. Based on recent annual reporting, the revenue structure is approximately:
- Beverages: about 63% to 66% of revenue. This includes ready-to-drink tea, juice, milk tea, coffee, and packaged water.
- Instant noodles and other food: about 34% to 37% of revenue. This mainly includes instant noodles and related convenience food products.
That mix matters because beverages generally offer broader product extension opportunities, while noodles provide a large installed customer base and repeat purchases. Over the last several years, total revenue has continued to edge upward, while gross profit has improved faster than sales, suggesting a better product mix and tighter cost control. Interest expense has also stayed very low, showing that the business is not heavily burdened by debt.
The profit flow highlights a useful trend: revenue has grown from roughly RMB 25 billion in 2021 to above RMB 30 billion in 2025, while gross profit has expanded more quickly than sales. Net income has also recovered strongly from the 2022 dip, which points to improving efficiency rather than growth driven only by volume.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Consumer Defensive | |
| Industry | Beverages - Non-Alcoholic | |
| Market Cap ⓘ | $4.01B | |
| Beta ⓘ | 0.14 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 12.95 | 17.88 |
| P/B Ratio ⓘ | 0.00 | 1.29 |
| FCF Yield ⓘ | 129.50% | 12.39% |
| Dividend Yield ⓘ | 7.55% | 2.85% |
| EBIT / EV ⓘ | N/A | 6.43% |
| PEG ⓘ | 1.01 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 1.40% | 4.10% |
| RPS Growth (5Y CAGR) ⓘ | 5.16% | 6.18% |
| EPS Growth (5Y CAGR) ⓘ | -21.82% | -13.59% |
| BVPS Growth (5Y CAGR) ⓘ | -0.28% | 3.20% |
| Margin Growth (5Y Trend) ⓘ | 0.20% | -0.15% |
| FCF Growth (5Y CAGR) ⓘ | 1.92% | 4.10% |
| DPS Growth (5Y CAGR) ⓘ | 3.35% | 6.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 25.12% | 12.34% |
| ROA (Latest) ⓘ | 17.57% | 6.30% |
| ROIC (5Y Median) ⓘ | 12.05% | 10.49% |
| ROA (5Y Median) ⓘ | 7.59% | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | 0.19 | 1.96 |
| Net Debt / EBIT (5Y Median) ⓘ | -1.08 | 2.35 |
| Net Debt / EBITDA (Latest) ⓘ | 0.13 | 1.38 |
| Net Debt / Assets ⓘ | 3.69% | 21.51% |
| EBITDA / Interest ⓘ | N/A | 9.46 |
| Operating Margin (Latest) ⓘ | 7.85% | 8.87% |
| Operating Margin (5Y Median) ⓘ | 7.44% | 9.53% |
| Debt to Equity (Latest) ⓘ | 19.73% | 72.35% |
| Profit Margin (Latest) ⓘ | 6.78% | 5.40% |
| Free Cash Flow (Latest) ⓘ | $5.19B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +54.60% | +20.92% |
| 12M Return (excl. last month) ⓘ | -12.04% | +2.13% |
| 6M Return ⓘ | +7.77% | +1.26% |
| Price vs. 200-Day MA ⓘ | +7.58% | +1.39% |
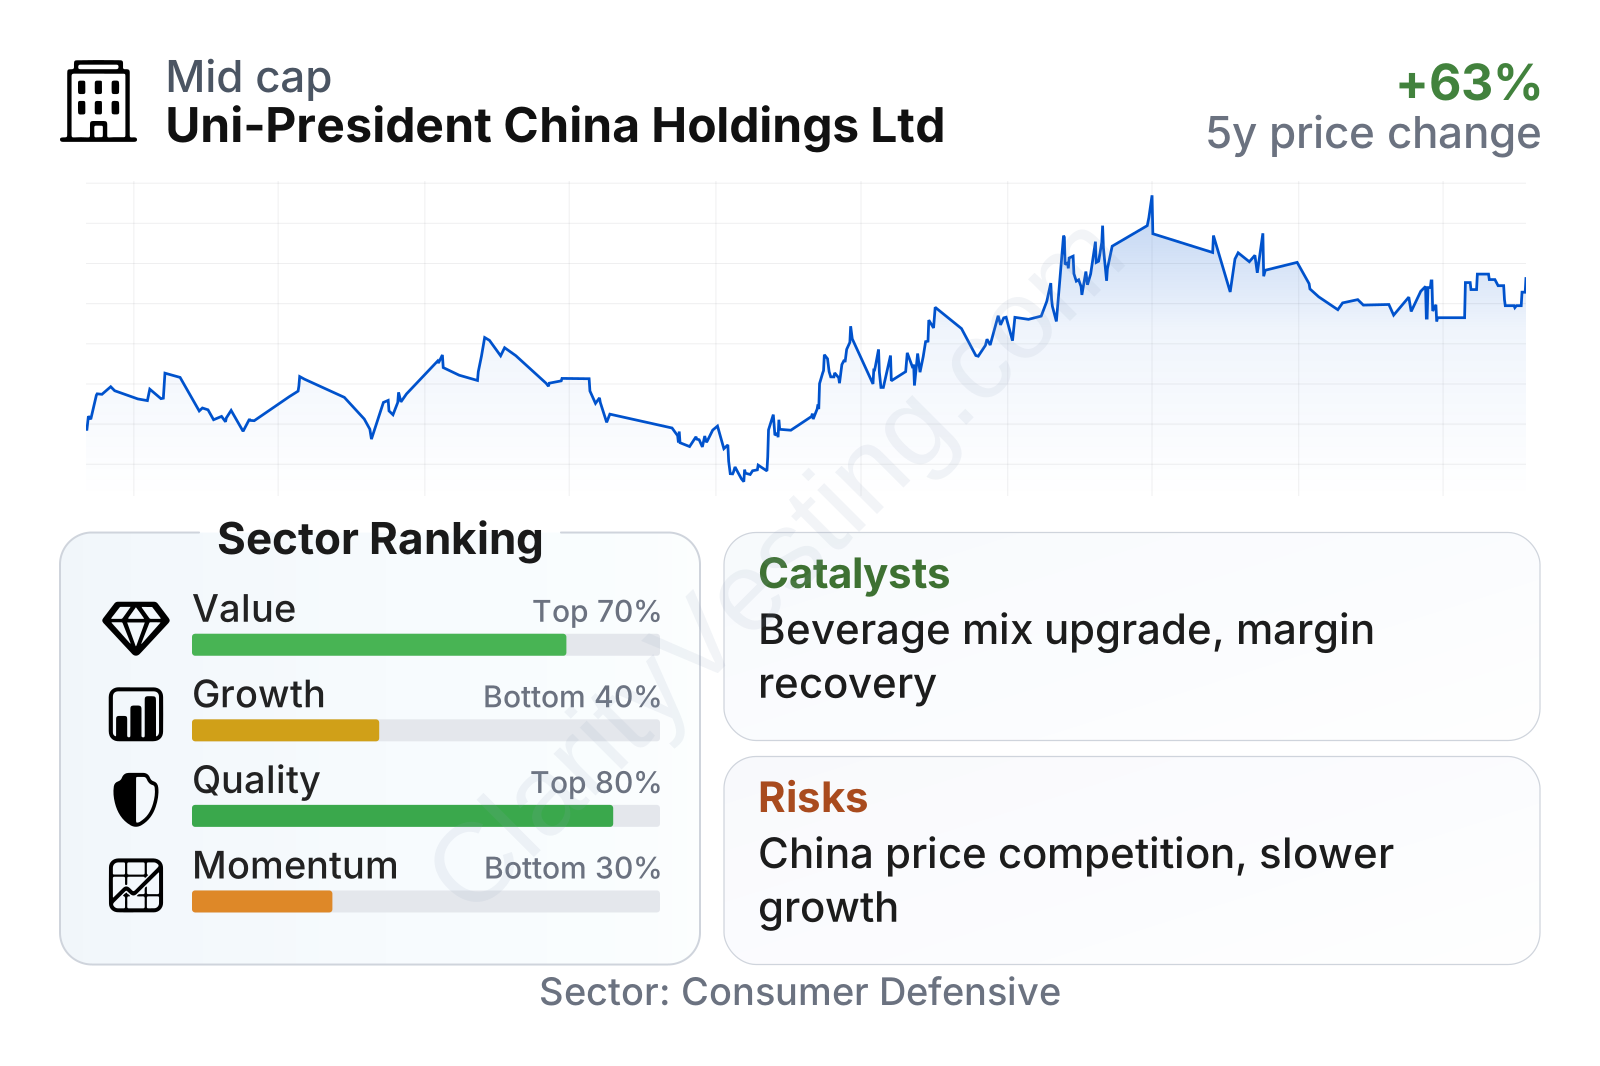
Uni-President China is a mid-sized consumer staples company with unusually low share-price volatility, reflected in a beta close to 0.15. Profitability and balance-sheet quality stand out more than growth. Returns on capital and assets are well above sector medians, profit margin is ahead of many peers, and leverage is very modest, with debt-to-equity around 20% and net debt very low relative to earnings. Free cash flow is solid, and the trailing dividend yield is notably higher than the sector median.
The weaker area is growth. Recent revenue growth has been positive but modest, and several five-year growth measures trail the broader sector. The share price has still delivered a strong multi-year gain, although shorter-term momentum has softened after the run-up into 2025.
Growth
Uni-President China operates in a mature but still relevant segment of consumer goods: affordable packaged beverages and convenience foods. This is not a high-growth technology market, but it is a large category supported by frequent purchases, wide distribution, and brand recognition. In China, non-alcoholic ready-to-drink beverages remain a major shelf-space battle, with companies competing through flavor innovation, healthier formulations, package sizes, and deeper penetration into lower-tier cities and convenience channels.
The company’s strategy appears sensible for this environment. It has a two-engine structure, pairing beverages with instant noodles, and can use established distribution networks across supermarkets, convenience stores, and other retail points. For long-term business development, the clearest catalyst is premiumization within beverages: newer tea, juice, coffee, and health-oriented drink categories can support better pricing and stronger margins than basic commodity-style products.
Another positive sign is that profitability has improved even though top-line expansion has not been rapid. That suggests management has been selective about product mix, promotions, and cost discipline. In a staples business, margin improvement can matter as much as volume growth because small changes in pricing, packaging, and channel efficiency can translate into meaningful earnings gains.
Recent annual results also indicate continued resilience rather than a one-year rebound. Revenue has moved higher for several years, and net income has climbed from the lower 2022 level to roughly RMB 2.0 billion in 2025. That does not make Uni-President China a fast grower, but it does support the case for a steady, cash-generative business with room for gradual earnings expansion.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


