Stock Analysis · Uni-President China Holdings Ltd (UNPSF)
Overview
Uni-President China Holdings Ltd is a large packaged food and beverage company focused on mainland China. It is best known for ready-to-drink tea, juice, milk-based beverages, bottled water, instant noodles, and other convenience foods sold through supermarkets, convenience stores, and other retail channels. The business sits in the consumer staples category, which usually means demand is tied more to everyday consumption than to economic cycles.
The company’s revenue mainly comes from beverages and instant noodles, with beverages clearly the larger business. Based on the company’s recent annual reporting structure, the revenue mix is approximately:
- Beverages: about 65% to 70% of revenue. This includes ready-to-drink tea, juice, milk tea, coffee, water, and other non-alcoholic drinks.
- Instant noodles: about 30% to 35% of revenue. This covers cup noodles, bag noodles, and related convenience food products.
That mix matters because beverages tend to offer broader brand extension opportunities and more premiumization potential, while noodles add scale and recurring everyday demand. Over the last several years, the company has also shown improving profitability within this structure, helped by a better gross margin profile and disciplined financing costs.
The financial flow over recent years suggests a business that has kept expanding revenue, from roughly RMB 25 billion in 2021 to around RMB 31 billion in 2025, while gross profit has improved faster than sales. Interest expense has also become very small relative to operating earnings, which supports earnings quality.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Consumer Defensive | |
| Industry | Beverages - Non-Alcoholic | |
| Market Cap ⓘ | $3.89B | |
| Beta ⓘ | 0.12 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 12.86 | 18.16 |
| P/B Ratio ⓘ | 0.30 | 1.27 |
| FCF Yield ⓘ | 133.90% | 12.39% |
| Dividend Yield ⓘ | 52.78% | 2.83% |
| EBIT / EV ⓘ | N/A | 6.45% |
| PEG ⓘ | 1.02 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 1.40% | 3.80% |
| RPS Growth (5Y CAGR) ⓘ | 5.19% | 6.20% |
| EPS Growth (5Y CAGR) ⓘ | -21.82% | -14.64% |
| BVPS Growth (5Y CAGR) ⓘ | -0.29% | 3.26% |
| Margin Growth (5Y Trend) ⓘ | 0.20% | -0.25% |
| FCF Growth (5Y CAGR) ⓘ | 1.86% | 4.65% |
| DPS Growth (5Y CAGR) ⓘ | 3.35% | 6.86% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 25.11% | 12.58% |
| ROA (Latest) ⓘ | 17.57% | 6.35% |
| ROIC (5Y Median) ⓘ | 9.06% | 10.36% |
| ROA (5Y Median) ⓘ | 7.59% | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | 0.19 | 1.91 |
| Net Debt / EBIT (5Y Median) ⓘ | -1.08 | 2.32 |
| Net Debt / EBITDA (Latest) ⓘ | 0.13 | 1.36 |
| Net Debt / Assets ⓘ | 3.69% | 21.25% |
| EBITDA / Interest ⓘ | N/A | 9.61 |
| Operating Margin (Latest) ⓘ | 7.85% | 8.96% |
| Operating Margin (5Y Median) ⓘ | 7.24% | 9.53% |
| Debt to Equity (Latest) ⓘ | 19.73% | 71.66% |
| Profit Margin (Latest) ⓘ | 6.78% | 5.40% |
| Free Cash Flow (Latest) ⓘ | $5.21B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +42.43% | +15.25% |
| 12M Return (excl. last month) ⓘ | +167.46% | +2.63% |
| 6M Return ⓘ | +167.46% | +2.43% |
| Price vs. 200-Day MA ⓘ | +60.51% | +0.43% |
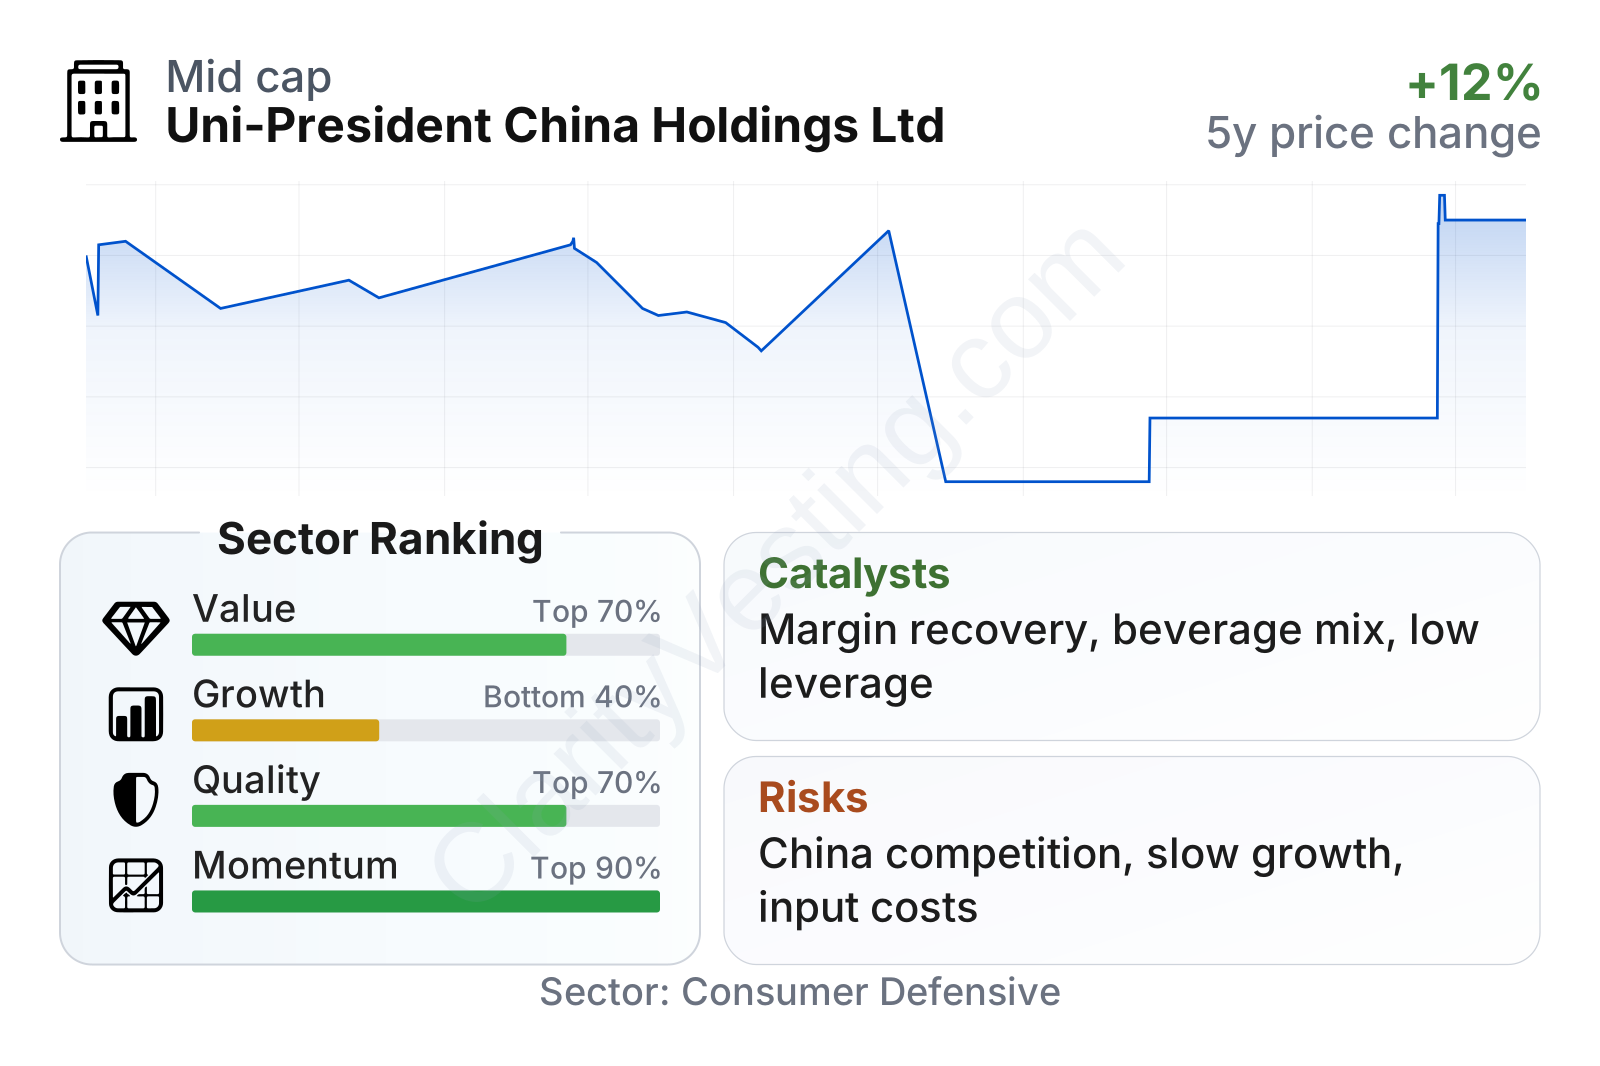
The market profile stands out in two ways. First, the shares have shown unusually strong recent momentum after a long weak period, so the stock is no longer in the same depressed position seen earlier. Second, valuation multiples still look modest against the sector on earnings and especially on book value, while balance-sheet strength is clearly better than many peers. Growth metrics, however, are not as strong as the valuation and quality signals: recent revenue expansion is positive but relatively slow for the sector, and longer-term earnings compounding has been uneven.
Financial quality appears solid. Profit margin is above the sector median, returns on assets and invested capital are strong on a trailing basis, and leverage is low, with debt-to-equity near 20% and net debt very limited relative to operating profit. Free cash flow is meaningful for a company of this size, which helps explain the strong cash-generation profile shown in the table.
Growth
Uni-President China operates in a sector that is still structurally relevant for long-term growth, even if it is not a high-growth industry in the usual sense. China’s non-alcoholic beverage and convenience food markets benefit from urbanization, large-scale retail distribution, on-the-go consumption, and a steady stream of product upgrades. Demand does not need to surge for the company to progress; even low- to mid-single-digit category growth can translate into meaningful earnings expansion when a company manages pricing, mix, and costs well.
The company’s strategy broadly makes sense for that environment. In beverages, brand depth and shelf presence matter, and Uni-President China already has both. In noodles, convenience and affordability keep the category relevant, while product segmentation can support margins. The more encouraging part of the recent profile is not rapid sales growth, but better conversion of revenue into profit. Gross profit has risen over the last few years, and operating income improved sharply in 2024 before staying at a healthy level in 2025. That suggests execution has recently mattered more than headline volume growth.
A practical catalyst is margin resilience. If input costs remain manageable and the company continues shifting sales toward stronger brands and better-priced products, earnings can grow faster than revenue. Another positive factor is financial flexibility: low leverage reduces pressure from financing costs and gives management room to absorb volatility in commodities or competition.
Recent annual reporting also points to continued profitability progress versus the weaker period seen earlier in the decade. That does not create a dramatic transformation case, but it does support the view that the company is operating from a healthier base than before.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


