Stock Analysis · CVR Partners LP (UAN)
Overview
CVR Partners LP is a U.S. fertilizer producer focused on nitrogen products used by farmers. Its two main manufacturing facilities are in Coffeyville, Kansas and East Dubuque, Illinois. The partnership sells products that help raise crop yields, especially for corn, wheat, and other large-acre crops. In simple terms, it turns natural gas or petroleum coke into nitrogen fertilizer and sells that fertilizer into the agricultural market.
The business is concentrated, which makes it easy to understand but also more exposed to swings in fertilizer pricing and plant operating conditions. Revenue comes mainly from a small number of product categories.
- UAN solution: approximately 50% to 60% of revenue in a typical year. UAN is a liquid nitrogen fertilizer used heavily in row crops.
- Ammonia: approximately 30% to 40% of revenue. Ammonia can be sold directly as fertilizer or upgraded into other nitrogen products.
- Other revenue: usually less than 10%. This can include freight, by-products, and other smaller commercial items.
That revenue mix can shift from year to year depending on market prices, product volumes, and planned or unplanned downtime at its two plants. One notable operating feature is that Coffeyville uses petroleum coke gasification rather than relying entirely on natural gas, which can matter when energy prices move sharply.
Over the last several years, the business has shown how sensitive earnings are to the fertilizer cycle. Revenue rose sharply in 2022, then cooled in 2023 and 2024, before recovering in 2025. Even with that volatility, the company has maintained strong operating margins relative to many peers when market conditions are favorable.
The long-term pattern is clear: sales and profits can expand quickly when nitrogen prices are strong, but they also contract when pricing normalizes. Operating costs have stayed relatively contained compared with the swings in revenue, which helps explain why profitability can rebound fast in better markets.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Agricultural Inputs | |
| Market Cap ⓘ | $1.33B | |
| Beta ⓘ | 0.24 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 8.33 | 16.90 |
| P/B Ratio ⓘ | 3.89 | 1.65 |
| FCF Yield ⓘ | 10.84% | 5.76% |
| Dividend Yield ⓘ | 11.53% | 2.13% |
| EBIT / EV ⓘ | 10.19% | 6.30% |
| PEG ⓘ | -1.30 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 20.00% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | 3.56% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | -19.40% | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | -5.87% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | -4.85% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | -12.44% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 26.54% | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 17.36% | 9.26% |
| ROA (Latest) ⓘ | 15.30% | 4.91% |
| ROIC (5Y Median) ⓘ | 15.59% | 7.70% |
| ROA (5Y Median) ⓘ | 9.92% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | 2.26 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | 3.58 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | 1.56 | 0.95 |
| Net Debt / Assets ⓘ | 40.81% | 13.69% |
| EBITDA / Interest ⓘ | 3.61 | 12.34 |
| Operating Margin (Latest) ⓘ | 28.26% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 26.13% | 11.80% |
| Debt to Equity (Latest) ⓘ | 163.98% | 40.56% |
| Profit Margin (Latest) ⓘ | 23.67% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $144.59M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +114.15% | +68.89% |
| 12M Return (excl. last month) ⓘ | +70.96% | +30.21% |
| 6M Return ⓘ | +16.09% | -4.16% |
| Price vs. 200-Day MA ⓘ | +11.46% | -1.27% |
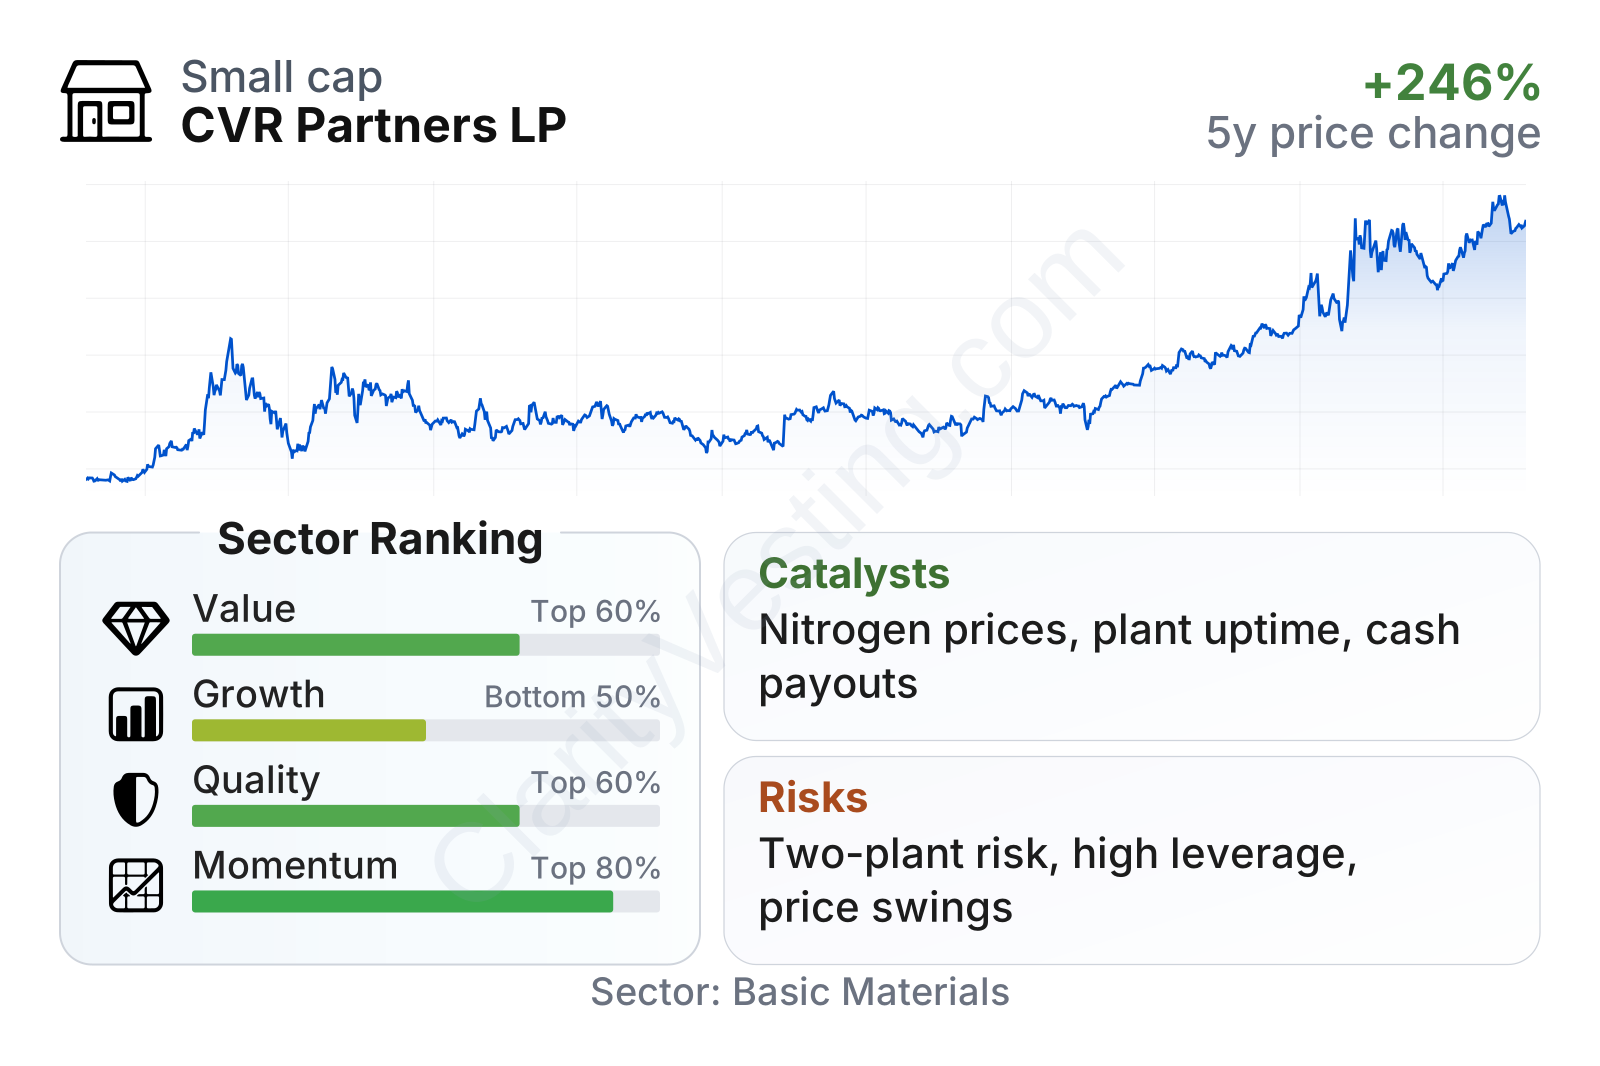
CVR Partners is a small-cap company with unusually low share-price sensitivity to the broader market, but that does not mean the business itself is stable. The stock has climbed strongly over the last several years, while the underlying fundamentals still reflect a cyclical commodity producer. On valuation, earnings and cash flow measures look inexpensive versus the sector, helped by a low P/E ratio and a free cash flow yield above the sector median. Quality is also better than it may first appear, with returns on capital and assets well ahead of typical agricultural-input peers. The weaker area is growth: longer-term earnings, book value, and free cash flow trends have been inconsistent, which fits a business driven heavily by fertilizer pricing rather than steady volume expansion.
Growth
Nitrogen fertilizer is part of a sector with durable long-term demand because global agriculture needs to keep improving crop yields. That gives CVR Partners a supportive base market. Farmers may delay purchases or shift application timing, but they cannot avoid nutrient demand indefinitely without affecting production. In that sense, the company operates in a necessary industry rather than a discretionary one.
Its strategy for growth is less about rapid expansion and more about maximizing output, reliability, and margin from a small asset base. That approach makes sense for this type of business. A fertilizer producer often creates more value through high plant utilization, disciplined maintenance, and feedstock cost advantages than through aggressive expansion projects. CVR Partners also benefits from being located close to major U.S. agricultural regions, which can support distribution economics and customer relevance.
Recent revenue trends show a rebound after the downturn seen through much of 2023 and 2024. Year-over-year growth has turned positive again in the latest periods, including growth rates above the sector median. That improvement suggests pricing and/or operating conditions have become more favorable, although the recovery is still happening within a cyclical market rather than a straight-line expansion.
Free cash flow remains positive, which is important for a partnership that is often judged on its capacity to produce cash and distribute it. However, the broader direction over several years has been downward from the unusually strong levels reached earlier in the cycle. In other words, the business is still generating cash, but not at the exceptional pace seen during the fertilizer price spike.
The most relevant catalysts are tied to nitrogen market fundamentals rather than a single transformative event. Strong corn acreage, firm grain economics, constrained global fertilizer supply, or elevated natural gas costs for overseas producers can all improve the company’s relative position. On the company-specific side, smooth operations at both plants can have a meaningful effect because the asset base is concentrated. When both facilities run well during favorable market conditions, financial results can move materially.
Recent company updates have also highlighted regular cash distributions, reflecting the partnership structure and the link between operating results and payouts. That can attract market attention during periods of high fertilizer margins, though distributions can change sharply with business conditions.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


