Stock Analysis · 10X Genomics Inc (TXG)
Overview
10x Genomics is a life science tools company that makes instruments, consumables, and software used by researchers to study biology at very high resolution. Its platforms help scientists analyze individual cells, gene activity, immune responses, and tissue samples in ways that are useful for academic research, drug discovery, and translational medicine. In simple terms, the company sells the tools that let researchers see what is happening inside complex biological samples with much more detail than older methods.
The business model is built around an installed base of instruments that drives recurring sales of higher-margin consumables and related services. This matters because once a laboratory adopts a platform, ongoing experiments typically require repeat purchases of kits, chips, reagents, and analysis tools.
Based on the company’s recent reporting structure, revenue mainly comes from the following sources:
- Consumables and related products: about 75% to 80% of revenue. This includes single-cell and spatial biology reagent kits, chips, slides, and other workflow products used repeatedly after an instrument is installed.
- Instruments: about 15% to 20% of revenue. These are the hardware systems placed in laboratories, including platforms tied to single-cell and spatial analysis workflows.
- Services and other: about 3% to 7% of revenue. This includes service contracts, support, and smaller ancillary revenue streams.
Within product families, the company is best known for single-cell analysis, which has historically been its largest business, and spatial biology, a fast-developing area focused on understanding where cells and gene activity are located inside tissue. Spatial biology has become especially important because it expands 10x Genomics beyond cell profiling into tissue-level insight, a field with growing relevance in oncology, immunology, and neuroscience.
The financial profile shows a company that has kept gross profit relatively strong while spending heavily on research, commercial expansion, and legal matters. Revenue climbed meaningfully from 2021 through 2025, but operating losses remained a feature of the model as the company prioritized innovation and market development.
One notable pattern is that gross profit has stayed solid while operating losses narrowed considerably by 2025. That suggests the core products still carry attractive economics, but the path to durable profitability depends on controlling operating expenses more tightly than in earlier years.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Medical Devices | |
| Market Cap ⓘ | $9.85B | |
| Beta ⓘ | 1.99 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 25.42 |
| P/B Ratio ⓘ | 10.98 | 3.08 |
| FCF Yield ⓘ | 1.23% | 3.12% |
| Dividend Yield ⓘ | N/A | 1.85% |
| EBIT / EV ⓘ | -0.09% | 0.56% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -12.70% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | 3.76% | 8.60% |
| EPS Growth (5Y CAGR) ⓘ | -28.80% | -17.73% |
| BVPS Growth (5Y CAGR) ⓘ | -3.66% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | N/A | -0.57% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.96% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.69% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -0.80% | 3.17% |
| ROA (Latest) ⓘ | -7.30% | 2.98% |
| ROIC (5Y Median) ⓘ | -15.52% | 4.56% |
| ROA (5Y Median) ⓘ | -16.21% | 1.87% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.86 |
| Net Debt / EBITDA (Latest) ⓘ | -11.25 | 1.00 |
| Net Debt / Assets ⓘ | -41.13% | 5.06% |
| EBITDA / Interest ⓘ | N/A | 9.55 |
| Operating Margin (Latest) ⓘ | -1.34% | 9.25% |
| Operating Margin (5Y Median) ⓘ | -29.09% | 7.33% |
| Debt to Equity (Latest) ⓘ | 9.54% | 26.68% |
| Profit Margin (Latest) ⓘ | -12.18% | 3.34% |
| Free Cash Flow (Latest) ⓘ | $121.44M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +74.99% | +51.61% |
| 12M Return (excl. last month) ⓘ | +518.87% | +19.90% |
| 6M Return ⓘ | +205.52% | +10.10% |
| Price vs. 200-Day MA ⓘ | +79.35% | +6.44% |
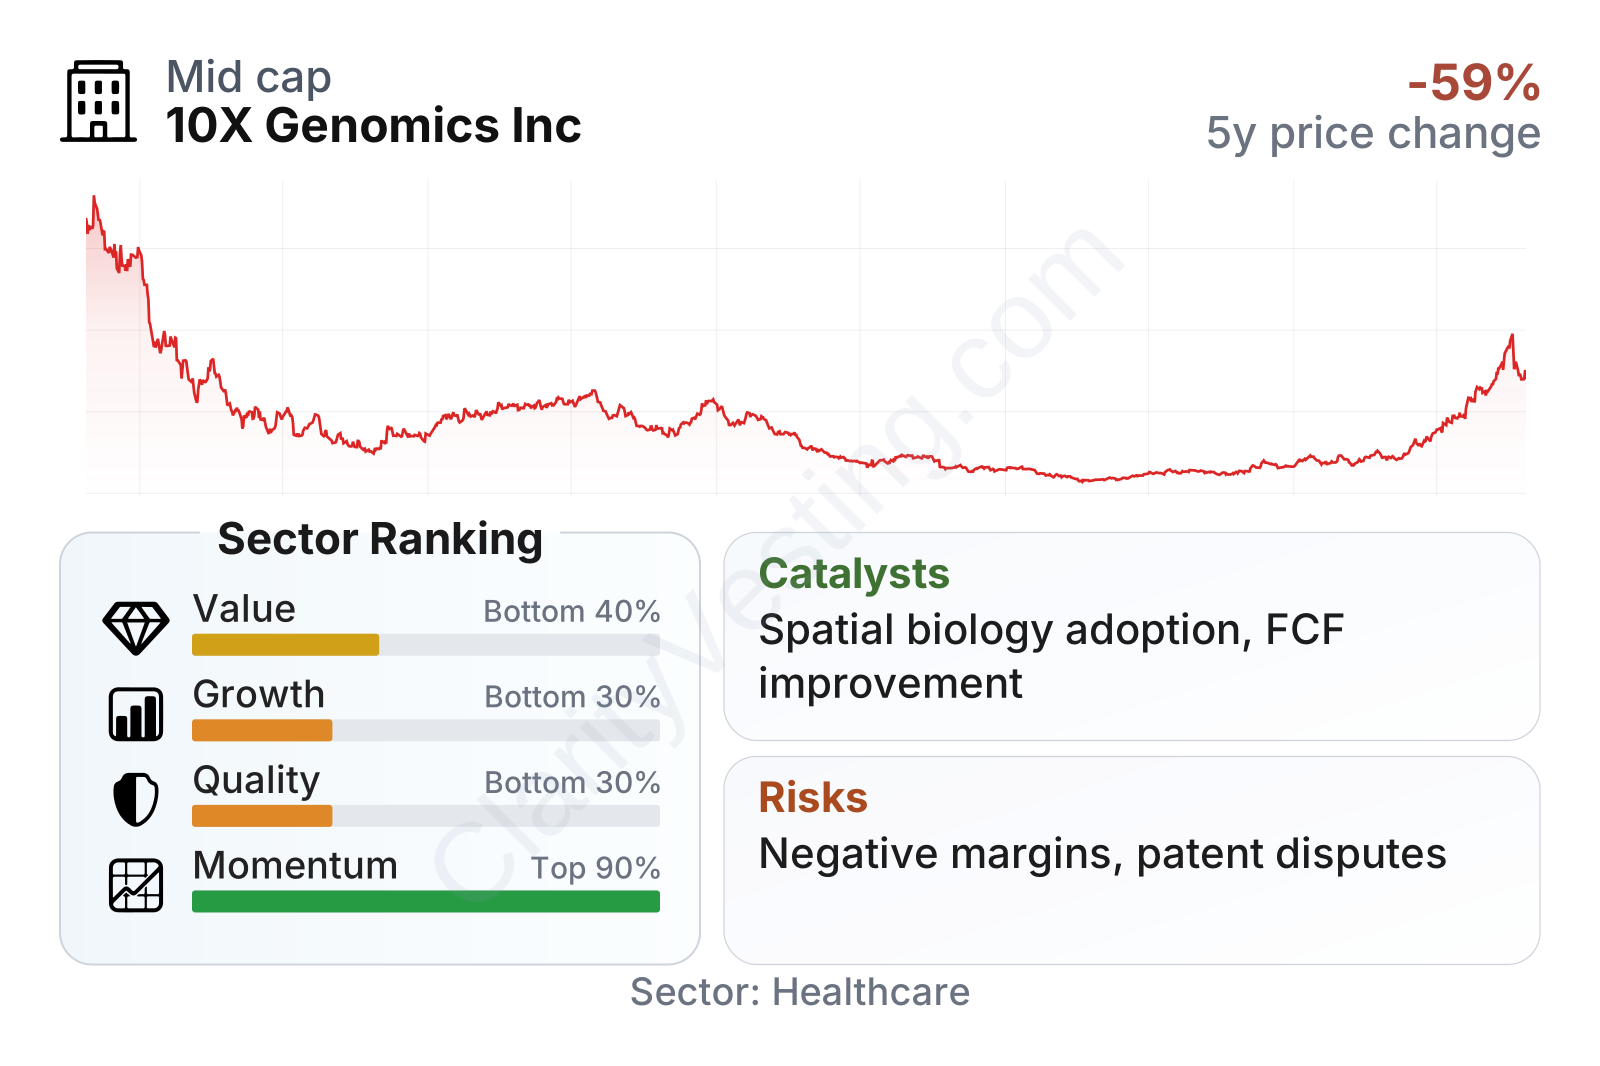
10x Genomics is a mid-sized healthcare tools company with a stock that has been extremely volatile. The recent share price rebound has been very strong, and momentum ranks well above most healthcare peers, but that comes after a deep multiyear decline. On fundamentals, the picture is more mixed: valuation remains demanding on book value and cash flow measures, while growth and quality metrics still rank in the lower part of the sector. The balance sheet is a brighter point, with low leverage and net cash providing financial flexibility.
Growth
10x Genomics operates in areas that are still considered long-term growth markets within life science research. Single-cell analysis and spatial biology are supported by broad trends in precision medicine, biomarker discovery, immunology, oncology research, and the push to understand disease at much finer resolution. These are not niche themes likely to disappear quickly; they are tied to how modern biological research is increasingly done.
The company’s strategy broadly makes sense for future expansion. It focuses on building a platform ecosystem rather than selling one-off equipment. Instruments can help widen adoption, but the more important economic engine is recurring consumables. If the installed base grows and existing customers run more experiments, revenue can compound without requiring the same pace of instrument placements every year. That creates a potentially attractive model once utilization stabilizes and laboratory budgets improve.
Another key growth driver is spatial biology. 10x Genomics has continued investing in this area because it can become a larger market over time and may deepen the company’s presence in drug research and clinical-adjacent applications. Spatial tools are often seen as a natural complement to single-cell workflows, which gives 10x cross-selling opportunities into existing customer relationships.
Recent revenue trends have been uneven. After a strong phase in 2023, growth slowed materially, and the latest year-over-year readings turned negative. That does not automatically mean the long-term market is weakening; in life science tools, demand can be heavily affected by academic funding cycles, customer budget pressure, and timing of large orders. Still, the recent slowdown shows that 10x is not currently delivering the kind of consistent expansion that would remove all doubt around the long-term trajectory.
A more encouraging sign is cash generation. Free cash flow moved from clearly negative territory to positive territory over the last two years, which suggests operating discipline is improving. That shift is important because it reduces dependence on outside financing and gives the company more room to keep funding product development during softer demand periods.
As for catalysts, one of the most important is continued adoption of newer platforms and workflow enhancements that increase customer spending per instrument. Another is a broader recovery in research funding and capital budgets across universities, medical centers, and biotech customers. The company has also highlighted product launches and upgrades in spatial biology and single-cell applications, which can refresh demand even when instrument spending is cautious.
Recent company communications have also pointed to ongoing platform innovation and expansion of application areas, especially where tissue analysis and multi-omics can add value. If these products become standard tools in more laboratories, 10x Genomics could strengthen recurring revenue and improve operating leverage over time.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


