Stock Analysis · Tetra Tech Inc (TTEK)
Overview
Tetra Tech is an engineering and consulting company focused on water, environmental services, sustainable infrastructure, and government-related technical work. In simple terms, it helps public agencies and private clients plan, design, manage, and improve complex projects such as water systems, environmental cleanup, resilience against floods and wildfires, renewable energy support, and digital tools used to monitor infrastructure and natural resources.
The company operates through two main segments. According to its latest annual filing, the larger business is Government Services Group, which works mainly for U.S. federal, state, and local agencies as well as international development clients. The second is Commercial/International Services Group, which serves private-sector and international customers in areas such as water, environmental remediation, energy transition, and asset management. Based on the latest full-year filing, revenue is approximately split as follows:
- Government Services Group: about 58% of revenue. This includes U.S. federal civil and defense work, disaster recovery, environmental programs, water-related public projects, and international development contracts.
- Commercial/International Services Group: about 42% of revenue. This includes consulting and engineering for utilities, industrial clients, commercial customers, and international infrastructure and environmental work.
Across end markets, water is one of the company’s most important themes, alongside environmental services and resilience-related work. Tetra Tech’s model is more consulting- and technology-led than heavy construction-led, which usually means lower capital intensity and higher margins than many traditional contractors. Recent years also show a business that has expanded revenue meaningfully while keeping profitability relatively solid.
The flow of revenue into profit has generally improved over the last several years, with total sales rising from a little above $3 billion earlier in the period to more than $5 billion recently. Gross profit has grown as well, although net income has been more uneven, reflecting acquisition effects, financing costs, and project mix.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 10, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Engineering & Construction | |
| Market Cap ⓘ | $8.55B | |
| Beta ⓘ | 0.95 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 20.11 | 22.32 |
| P/B Ratio ⓘ | 4.59 | 1.98 |
| FCF Yield ⓘ | 6.41% | 6.34% |
| Dividend Yield ⓘ | 0.80% | 1.95% |
| EBIT / EV ⓘ | 6.42% | 4.71% |
| PEG ⓘ | 2.10 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -3.90% | 9.25% |
| RPS Growth (5Y CAGR) ⓘ | 14.74% | 7.75% |
| EPS Growth (5Y CAGR) ⓘ | 5.09% | -13.37% |
| BVPS Growth (5Y CAGR) ⓘ | 10.21% | 6.12% |
| Margin Growth (5Y Trend) ⓘ | -1.02% | 0.81% |
| FCF Growth (5Y CAGR) ⓘ | 10.38% | 11.01% |
| DPS Growth (5Y CAGR) ⓘ | 13.55% | 9.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 17.27% | 10.70% |
| ROA (Latest) ⓘ | 10.06% | 5.38% |
| ROIC (5Y Median) ⓘ | 16.60% | 9.26% |
| ROA (5Y Median) ⓘ | 8.48% | 4.94% |
| Net Debt / EBIT (Latest) ⓘ | 1.27 | 2.08 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.54 | 2.29 |
| Net Debt / EBITDA (Latest) ⓘ | 1.16 | 1.43 |
| Net Debt / Assets ⓘ | 18.06% | 19.34% |
| EBITDA / Interest ⓘ | 22.78 | 9.54 |
| Operating Margin (Latest) ⓘ | 12.31% | 10.34% |
| Operating Margin (5Y Median) ⓘ | 9.77% | 10.29% |
| Debt to Equity (Latest) ⓘ | 55.25% | 65.52% |
| Profit Margin (Latest) ⓘ | 10.00% | 6.63% |
| Free Cash Flow (Latest) ⓘ | $548.21M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +7.34% | +61.33% |
| 12M Return (excl. last month) ⓘ | +0.32% | +14.82% |
| 6M Return ⓘ | +6.35% | +3.53% |
| Price vs. 200-Day MA ⓘ | -0.56% | +0.88% |
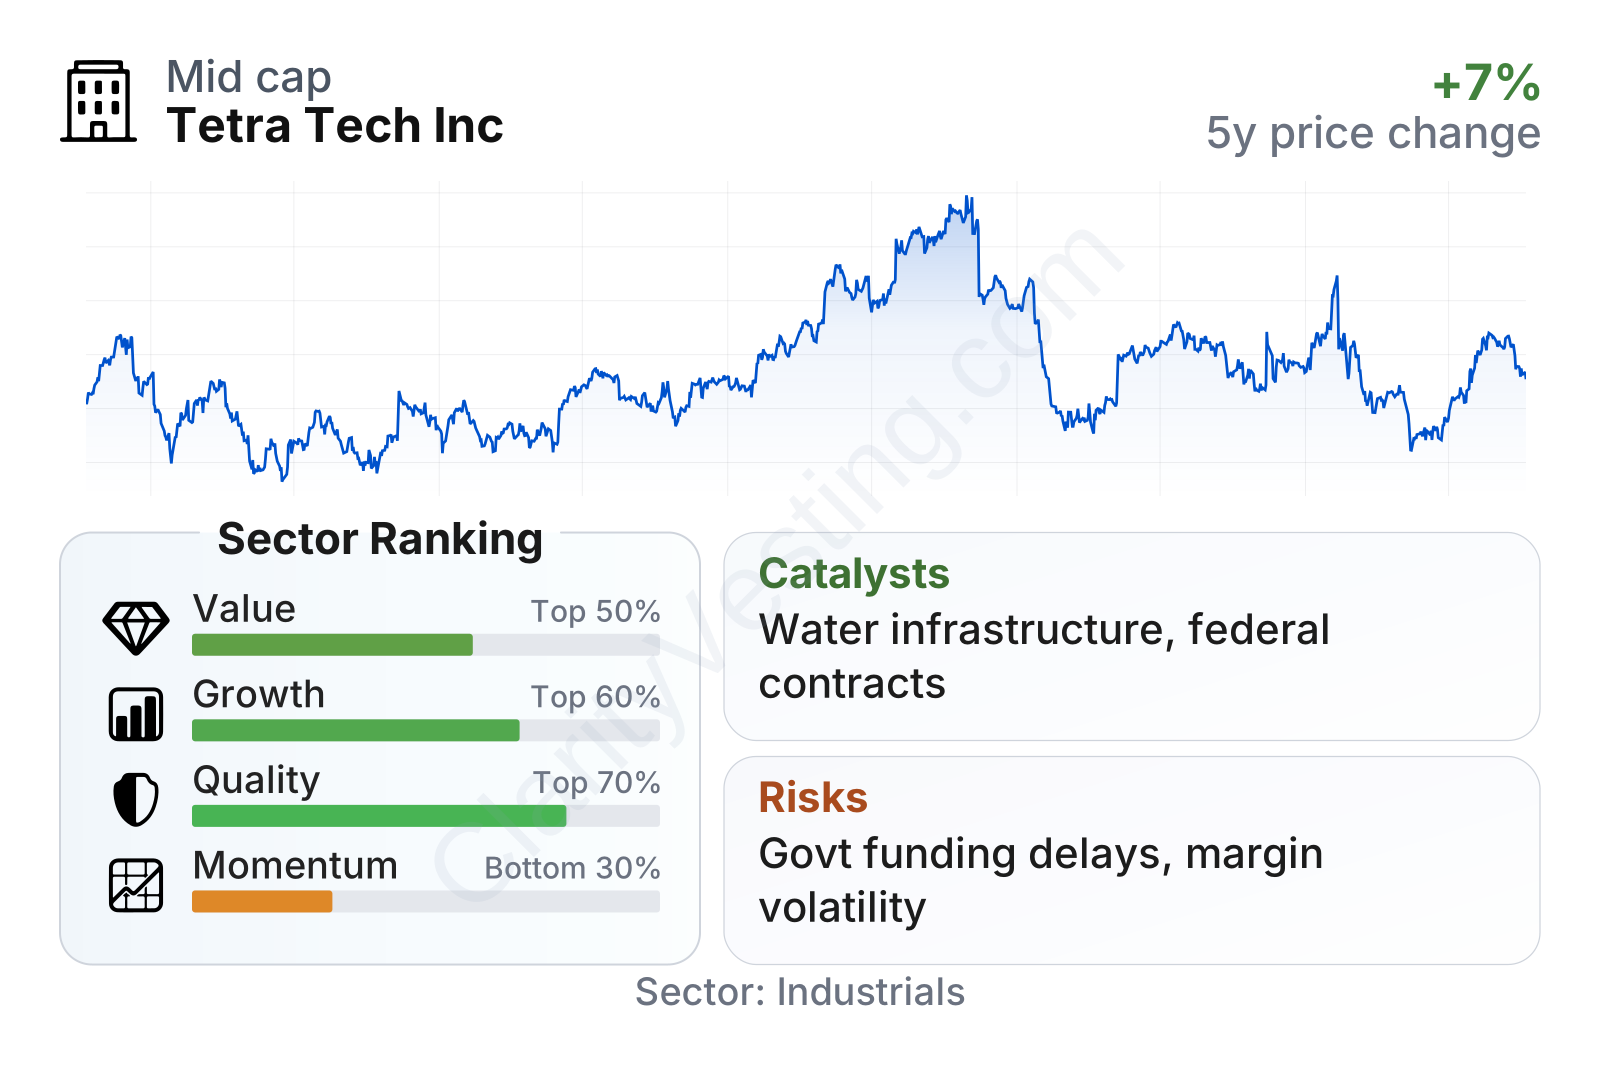
Tetra Tech is a mid-to-large engineering and consulting firm by industry standards, with a market value in the high single-digit billions of dollars. The overall picture from the latest metrics is fairly balanced: valuation looks near the sector middle, quality ranks clearly above average, growth is acceptable but not outstanding in the most recent period, and share-price momentum has been weaker than much of the sector. Profitability and returns on capital stand out more than headline recent growth.
Its return on invested capital and return on assets are both comfortably above sector medians, suggesting the business converts capital into earnings efficiently. Balance-sheet leverage is moderate rather than aggressive, and interest coverage is strong, which reduces financial strain. At the same time, the market has assigned a richer price-to-book multiple than the typical peer, showing that investors have historically been willing to pay a premium for business quality.
Growth
Tetra Tech operates in markets that have durable long-term demand drivers. Water infrastructure needs in the United States remain large because many systems are aging and require upgrades. Environmental cleanup, climate adaptation, storm resilience, wildfire mitigation, and energy-transition planning are also areas where spending is likely to remain substantial for years. These are not short-lived themes: they are tied to regulation, public funding, and physical infrastructure needs.
The company’s strategy broadly fits those trends. It has built itself around higher-value consulting, engineering, data, and program management rather than low-margin construction exposure. That matters because clients often need specialized expertise in permitting, environmental compliance, digital monitoring, and water resource planning, and those tasks can create sticky customer relationships and repeat work.
Growth has not been perfectly smooth quarter to quarter, but the longer pattern remains constructive. Revenue growth has swung from very strong double-digit periods to slower phases, yet the latest trend still points to continuing expansion in 2026 after a softer comparison in the summary metrics. Over five years, revenue per share has increased at a rate well above the sector median, which suggests that the company has created real scale rather than only benefiting from temporary pricing effects.
Cash generation is another encouraging point. Free cash flow has been somewhat uneven from year to year, which is normal for project-based businesses, but the most recent trailing figure shows a sharp improvement versus prior periods. That is important because cash flow supports acquisitions, dividends, debt management, and internal investment without requiring outside financing.
Recent company announcements also support the case for continued demand. Tetra Tech has continued to win and expand work tied to U.S. federal agencies, water management, environmental remediation, and resilience-related programs. It has also emphasized digital water, geospatial tools, and AI-enabled analytics, which can help it deepen client relationships and raise the value of its services rather than competing only on labor hours.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


