Stock Analysis · TravelSky Technology Ltd (TSYHY)
Overview
TravelSky Technology Ltd is a Chinese information technology company focused on the travel industry. Its core role is to provide the digital infrastructure used by airlines, airports, travel agencies, and travelers across China’s civil aviation system. In practical terms, the company helps process airline reservations, passenger service operations, settlement, data exchange, and other travel-related transactions. It also provides software and technology services for airports and aviation management.
The business is closely tied to air travel activity in China. When airline passengers, flight volumes, and airport technology spending rise, TravelSky generally benefits because its platforms sit inside the operating flow of the industry rather than depending on one single airline brand.
Based on the company’s annual disclosures, TravelSky’s revenue is mainly generated from the following areas:
- Aviation information technology services: approximately 70% to 80% of revenue in recent years. This is the core business and includes reservation, departure control, settlement, clearing, and related data-network services for airlines and travel distributors.
- Accounting, settlement, and clearing services: a meaningful subsegment within the aviation ecosystem, typically included in the company’s core transaction-processing activities. Public reporting indicates this is one of the main operating pillars, although exact standalone percentages are not always separately disclosed.
- System integration and data network services: roughly 10% to 20% of revenue. This includes technology infrastructure, implementation work, and network-related solutions for aviation customers.
- Airport information technology services and other related services: generally less than 10% to low-teens of revenue. This includes airport passenger processing, baggage, operational systems, and other software support.
One useful feature of TravelSky’s model is that it combines software-like economics with infrastructure-like customer relationships. Once a reservation, airport, or settlement platform is embedded in daily operations, switching can be disruptive, which can support retention and steady transaction volumes.
The broader profit flow has improved sharply since the pandemic period. Revenue and net income recovered strongly through 2023 and 2024, and margins expanded as travel volumes normalized and operating leverage returned. The 2025 revenue mix appears less favorable than 2024 at the gross profit level, which is worth monitoring, but earnings remained solid.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Technology | |
| Industry | Information Technology Services | |
| Market Cap ⓘ | $3.36B | |
| Beta ⓘ | 0.37 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 9.49 | 30.28 |
| FCF Yield ⓘ | 145.94% | 4.19% |
| Dividend Yield ⓘ | 3.55% | 1.30% |
| EBIT / EV ⓘ | N/A | 2.79% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 5.60% | 15.70% |
| RPS Growth (5Y CAGR) ⓘ | 11.39% | 8.56% |
| EPS Growth (5Y CAGR) ⓘ | 27.16% | -11.54% |
| Margin Growth (5Y Trend) ⓘ | 17.79% | 0.46% |
| FCF Growth (5Y CAGR) ⓘ | -3.44% | 9.72% |
| DPS Growth (5Y CAGR) ⓘ | 74.41% | 7.73% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.44% |
| ROIC (5Y Median) ⓘ | 7.16% | 8.35% |
| Net Debt / EBIT (Latest) ⓘ | -1.58 | 0.50 |
| Net Debt / EBIT (5Y Median) ⓘ | -3.84 | 0.48 |
| Net Debt / EBITDA (Latest) ⓘ | -1.24 | 0.28 |
| Net Debt / Assets ⓘ | -21.80% | 3.48% |
| EBITDA / Interest ⓘ | N/A | 12.91 |
| Operating Margin (Latest) ⓘ | 32.98% | 9.77% |
| Operating Margin (5Y Median) ⓘ | 23.30% | 8.53% |
| Debt to Equity (Latest) ⓘ | 4.95% | 34.51% |
| Profit Margin (Latest) ⓘ | 27.13% | 7.14% |
| Free Cash Flow (Latest) ⓘ | $4.90B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -21.25% | +56.52% |
| 12M Return (excl. last month) ⓘ | -16.58% | +13.17% |
| 6M Return ⓘ | -0.63% | +15.38% |
| Price vs. 200-Day MA ⓘ | +1.62% | +7.53% |
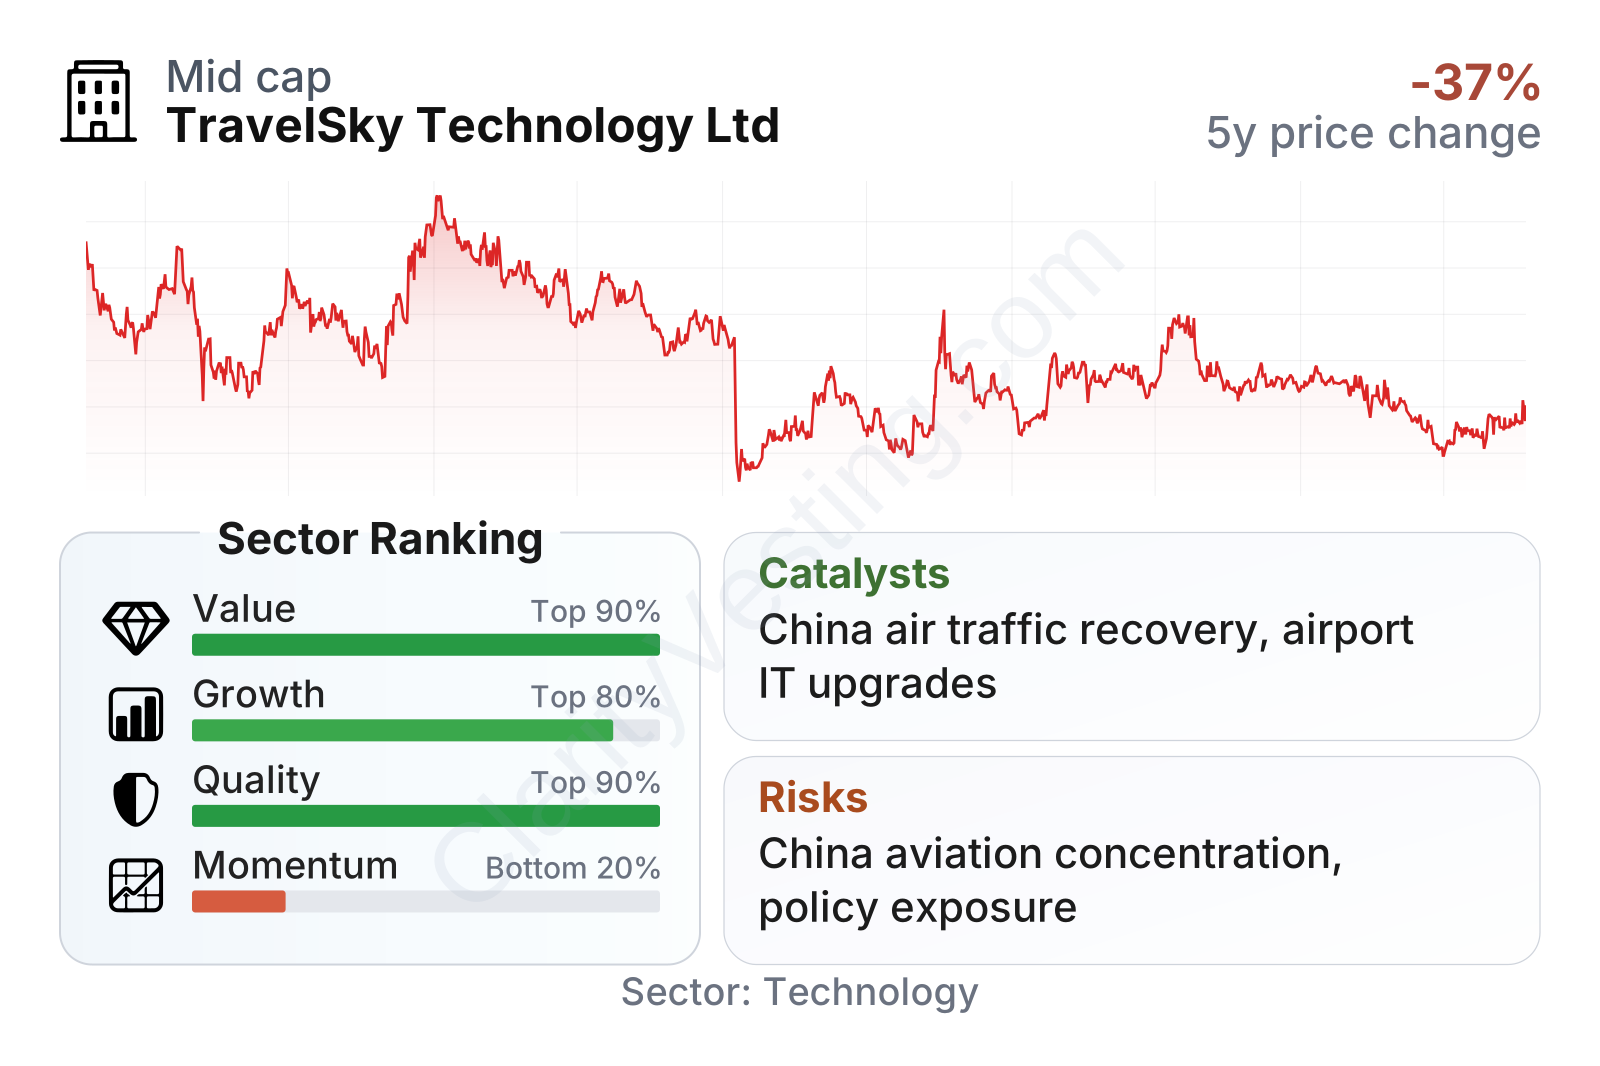
TravelSky is a mid-sized technology company with a relatively low share-price volatility profile, reflected in a beta well below 1. On valuation and profitability measures, it ranks strongly within its sector: earnings multiple, dividend yield, operating margin, and net cash positioning all stand out positively. Growth is more mixed. Recent year-over-year revenue growth is modest compared with the broader technology sector, but the longer five-year record for revenue per share, earnings per share, and margin improvement is considerably better. Market momentum is the weakest area, with the stock trailing much of the sector over the last 12 months and 3 years.
The share-price history reflects that contrast. The business recovered meaningfully after the travel downturn, but the stock has remained uneven and is still well below its 2023 high. That gap suggests the market is not fully rewarding the earnings recovery, likely because of concerns around China exposure, travel demand durability, and the company’s lower-growth profile relative to faster-growing technology names.
Growth
TravelSky operates in a sector that should grow over time: the digitization of travel infrastructure and the long-term expansion of air traffic in China. Airlines and airports increasingly rely on integrated booking, passenger handling, settlement, and operational software. This creates a structural need for the kind of systems TravelSky already provides.
The company’s strategy also makes sense from a long-term industry standpoint. Instead of chasing consumer-facing travel demand alone, it is positioned deeper in the value chain, where systems are mission-critical. That gives it exposure to rising transaction volumes, airport modernization, and broader adoption of data-driven aviation operations. If China’s domestic aviation activity continues to normalize and expand, TravelSky has a direct path to benefit.
A notable catalyst is the continued recovery and modernization of China’s civil aviation system. Airport digital upgrades, efficiency requirements, and passenger-service automation can support additional demand beyond simple ticket volume growth. Another potential tailwind is the company’s strong balance sheet and cash generation, which provide flexibility for product development, infrastructure investment, and dividends without heavy reliance on borrowing.
Recent financial trends also support the growth case in a measured way. Over the last several years, revenue per share has increased at an annualized pace above the sector median, earnings growth has been particularly strong, and operating margins have improved substantially. That combination suggests TravelSky has not only recovered from disrupted travel conditions but has done so with better profitability.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


