Stock Analysis · Turning Point Brands Inc (TPB)
Overview
Turning Point Brands is a U.S. consumer products company focused on nicotine and smoking-related categories. Its portfolio is centered on modern oral nicotine pouches sold under the Zig-Zag brand, traditional loose-leaf chewing tobacco sold mainly under Stoker’s, and a broad collection of rolling papers, tubes, cigars, and related accessories. The business operates in the wider tobacco industry, but its most important strategic shift in recent years has been toward modern nicotine products, especially nicotine pouches.
The company reports its business in three main segments. Based on recent annual reporting, revenue is spread roughly as follows:
- Zig-Zag Products: about 45% to 50% of revenue. This segment includes rolling papers, make-your-own cigarette papers and tubes, finished cigars, and modern oral nicotine products, especially nicotine pouches.
- Stoker’s Products: about 40% to 45% of revenue. This segment is primarily moist snuff and loose-leaf chewing tobacco sold in the U.S.
- Creative Distribution Solutions: about 10% to 15% of revenue. This distribution-focused activity supplies vaping and other accessory products to convenience stores and other retail channels.
Within that mix, nicotine pouches have become increasingly important because they are growing much faster than the more mature parts of the company. That matters because traditional tobacco categories can produce steady cash flow, while pouches offer a more visible path to expansion. Over the last several years, the company has also shown a meaningful recovery in total revenue and operating income after the 2022 downturn, with gross profit rising faster than sales in 2025, suggesting a healthier product mix.
The business profile now looks more balanced than it did a few years ago: traditional tobacco still provides scale and profitability, while newer nicotine offerings are driving most of the growth narrative.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Consumer Defensive | |
| Industry | Tobacco | |
| Market Cap ⓘ | $1.13B | |
| Beta ⓘ | 0.97 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 24.33 | 17.88 |
| P/B Ratio ⓘ | 2.74 | 1.29 |
| FCF Yield ⓘ | 1.73% | 12.39% |
| Dividend Yield ⓘ | 0.55% | 2.85% |
| EBIT / EV ⓘ | 7.47% | 6.43% |
| PEG ⓘ | 0.05 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 22.60% | 4.10% |
| RPS Growth (5Y CAGR) ⓘ | 5.57% | 6.18% |
| EPS Growth (5Y CAGR) ⓘ | -25.41% | -13.59% |
| BVPS Growth (5Y CAGR) ⓘ | 32.86% | 3.20% |
| Margin Growth (5Y Trend) ⓘ | 2.43% | -0.15% |
| FCF Growth (5Y CAGR) ⓘ | -8.32% | 4.10% |
| DPS Growth (5Y CAGR) ⓘ | 12.64% | 6.79% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 12.34% | 12.34% |
| ROA (Latest) ⓘ | 5.58% | 6.30% |
| ROIC (5Y Median) ⓘ | 13.72% | 10.49% |
| ROA (5Y Median) ⓘ | 7.49% | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | 0.45 | 1.96 |
| Net Debt / EBIT (5Y Median) ⓘ | 3.08 | 2.35 |
| Net Debt / EBITDA (Latest) ⓘ | 0.41 | 1.38 |
| Net Debt / Assets ⓘ | 4.95% | 21.51% |
| EBITDA / Interest ⓘ | 4.16 | 9.46 |
| Operating Margin (Latest) ⓘ | 18.48% | 8.87% |
| Operating Margin (5Y Median) ⓘ | 23.44% | 9.53% |
| Debt to Equity (Latest) ⓘ | 72.23% | 72.35% |
| Profit Margin (Latest) ⓘ | 8.78% | 5.40% |
| Free Cash Flow (Latest) ⓘ | $19.63M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +165.34% | +20.92% |
| 12M Return (excl. last month) ⓘ | -29.89% | +2.13% |
| 6M Return ⓘ | -33.48% | +1.26% |
| Price vs. 200-Day MA ⓘ | -38.13% | +1.39% |
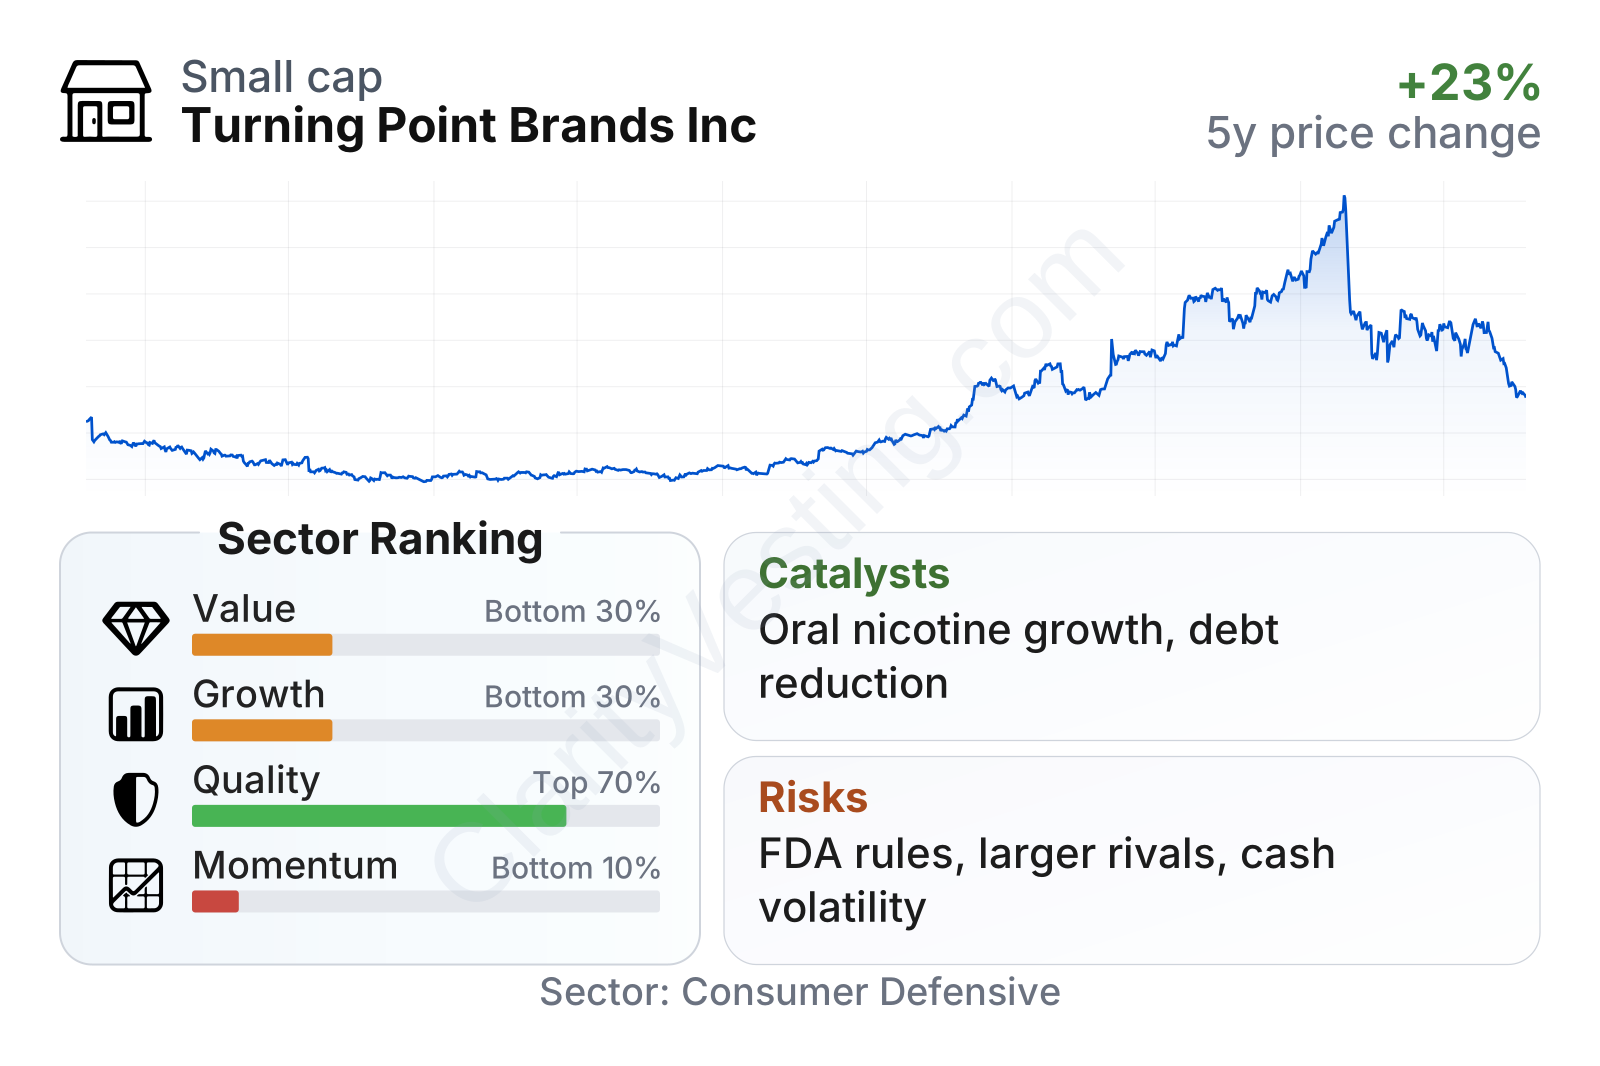
Turning Point Brands is a small-cap consumer defensive company with a stock that has been much stronger over three years than the broader sector, although recent trading has been notably weaker. The quality profile looks decent: operating margin and profit margin are above sector norms, and leverage has come down sharply from very elevated levels to around the sector average on a debt-to-equity basis. On the other hand, valuation metrics are not especially cheap, free cash flow yield is low, and recent momentum has turned negative after a very strong run.
Growth
Turning Point Brands operates in a sector that is split between slow-moving legacy tobacco and faster-growing reduced-risk nicotine products. The most attractive part of that market is modern oral nicotine, where consumer demand has been expanding as some users shift away from combustible products and seek more discreet formats. That puts the company in a category with better structural growth than the traditional tobacco market as a whole.
The company’s strategy makes sense if viewed through that lens. Stoker’s remains a cash-generating brand in mature smokeless tobacco, while Zig-Zag gives the group a recognized consumer name that can be extended into adjacent nicotine products. The key point is that Turning Point Brands does not need all of tobacco to grow; it mainly needs to keep gaining relevance in oral nicotine while defending profitability in its legacy brands.
Revenue growth has improved sharply since 2024. After several periods of decline, sales turned positive in 2025 and remained strong into 2026, with year-over-year growth running well above the sector median. That kind of rebound usually points to more than simple price increases alone; it suggests that product mix, distribution gains, or both are helping the company reaccelerate.
Cash generation is the more mixed part of the picture. Free cash flow has been volatile and recently compressed, even though accounting profitability remains positive. For long-term analysis, that means sales growth and margin resilience look encouraging, but it is still important to watch whether that growth converts into steadier cash flow over time.
A notable catalyst in recent years has been the company’s deeper push into nicotine pouches. Management has highlighted this area as a priority, and the broader U.S. market for modern oral nicotine continues to expand. If Turning Point Brands can keep widening distribution and maintain shelf space in convenience retail, that segment could continue to raise its weight in the overall business.
Another favorable element is that the company’s brand portfolio sits in categories where repeat purchasing is common. In consumer staples, that can support predictable demand once a product gains traction. The strongest opportunity is therefore not tied to one-time events, but to the possibility that oral nicotine keeps growing faster than the legacy parts of the business for several more years.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


