Stock Analysis · Torex Gold Resources Inc (TORXF)
Overview
Torex Gold Resources Inc. is a Canadian gold producer focused on mining, processing, and selling gold from its operations in Mexico. Its core asset is the Morelos Complex in Guerrero State, which includes the El Limón Guajes mining complex, the Media Luna project, processing infrastructure, and related exploration land. In practical terms, the company earns money by extracting ore, processing it into gold doré, and selling that metal into the market.
The business is concentrated, which makes it easy to understand but also increases asset-level risk. Public filings indicate that revenue is overwhelmingly tied to gold sales, with a smaller contribution from silver contained in doré bars. The company is also investing heavily in extending mine life and expanding production through Media Luna, a nearby deposit designed to become the next major source of ore for the Morelos processing system.
Main revenue sources are approximately the following:
- Gold sales: about 95% to 99% of revenue. This is the company’s primary economic engine and reflects ounces sold multiplied by realized gold prices.
- Silver sales: about 1% to 5% of revenue. Silver is mainly a by-product recovered alongside gold and sold as part of doré output.
- Other revenue: minimal. Torex is essentially a single-business mining company rather than a diversified materials group.
The financial flow has improved meaningfully over the last several years. Revenue moved from roughly $0.9 billion in 2021-2023 to above $1.1 billion in 2024 and above $1.3 billion in 2025, while operating income and free cash generation expanded strongly. That pattern suggests not only better metal prices, but also stronger operating leverage when production is running well.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Gold | |
| Market Cap ⓘ | $4.85B | |
| Beta ⓘ | 1.45 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 8.04 | 16.92 |
| P/B Ratio ⓘ | 1.90 | 1.66 |
| FCF Yield ⓘ | 11.36% | 5.83% |
| Dividend Yield ⓘ | 0.63% | 2.07% |
| EBIT / EV ⓘ | 18.66% | 6.38% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 60.30% | 11.25% |
| RPS Growth (5Y CAGR) ⓘ | 10.67% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | 17.31% | -15.24% |
| BVPS Growth (5Y CAGR) ⓘ | 20.77% | 5.49% |
| Margin Growth (5Y Trend) ⓘ | 10.03% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 2.92% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 5.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.59% |
| ROA (Latest) ⓘ | 21.65% | 4.92% |
| ROIC (5Y Median) ⓘ | 14.68% | 7.91% |
| ROA (5Y Median) ⓘ | 11.92% | 3.92% |
| Net Debt / EBIT (Latest) ⓘ | -0.08 | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | -0.61 | 1.69 |
| Net Debt / EBITDA (Latest) ⓘ | -0.07 | 0.93 |
| Net Debt / Assets ⓘ | -2.27% | 13.69% |
| EBITDA / Interest ⓘ | N/A | 12.38 |
| Operating Margin (Latest) ⓘ | 46.39% | 13.24% |
| Operating Margin (5Y Median) ⓘ | 31.44% | 11.82% |
| Debt to Equity (Latest) ⓘ | 3.86% | 40.30% |
| Profit Margin (Latest) ⓘ | 32.96% | 6.38% |
| Free Cash Flow (Latest) ⓘ | $550.76M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +396.06% | +73.47% |
| 12M Return (excl. last month) ⓘ | +24.24% | +27.59% |
| 6M Return ⓘ | +15.13% | -4.02% |
| Price vs. 200-Day MA ⓘ | +11.87% | -0.65% |
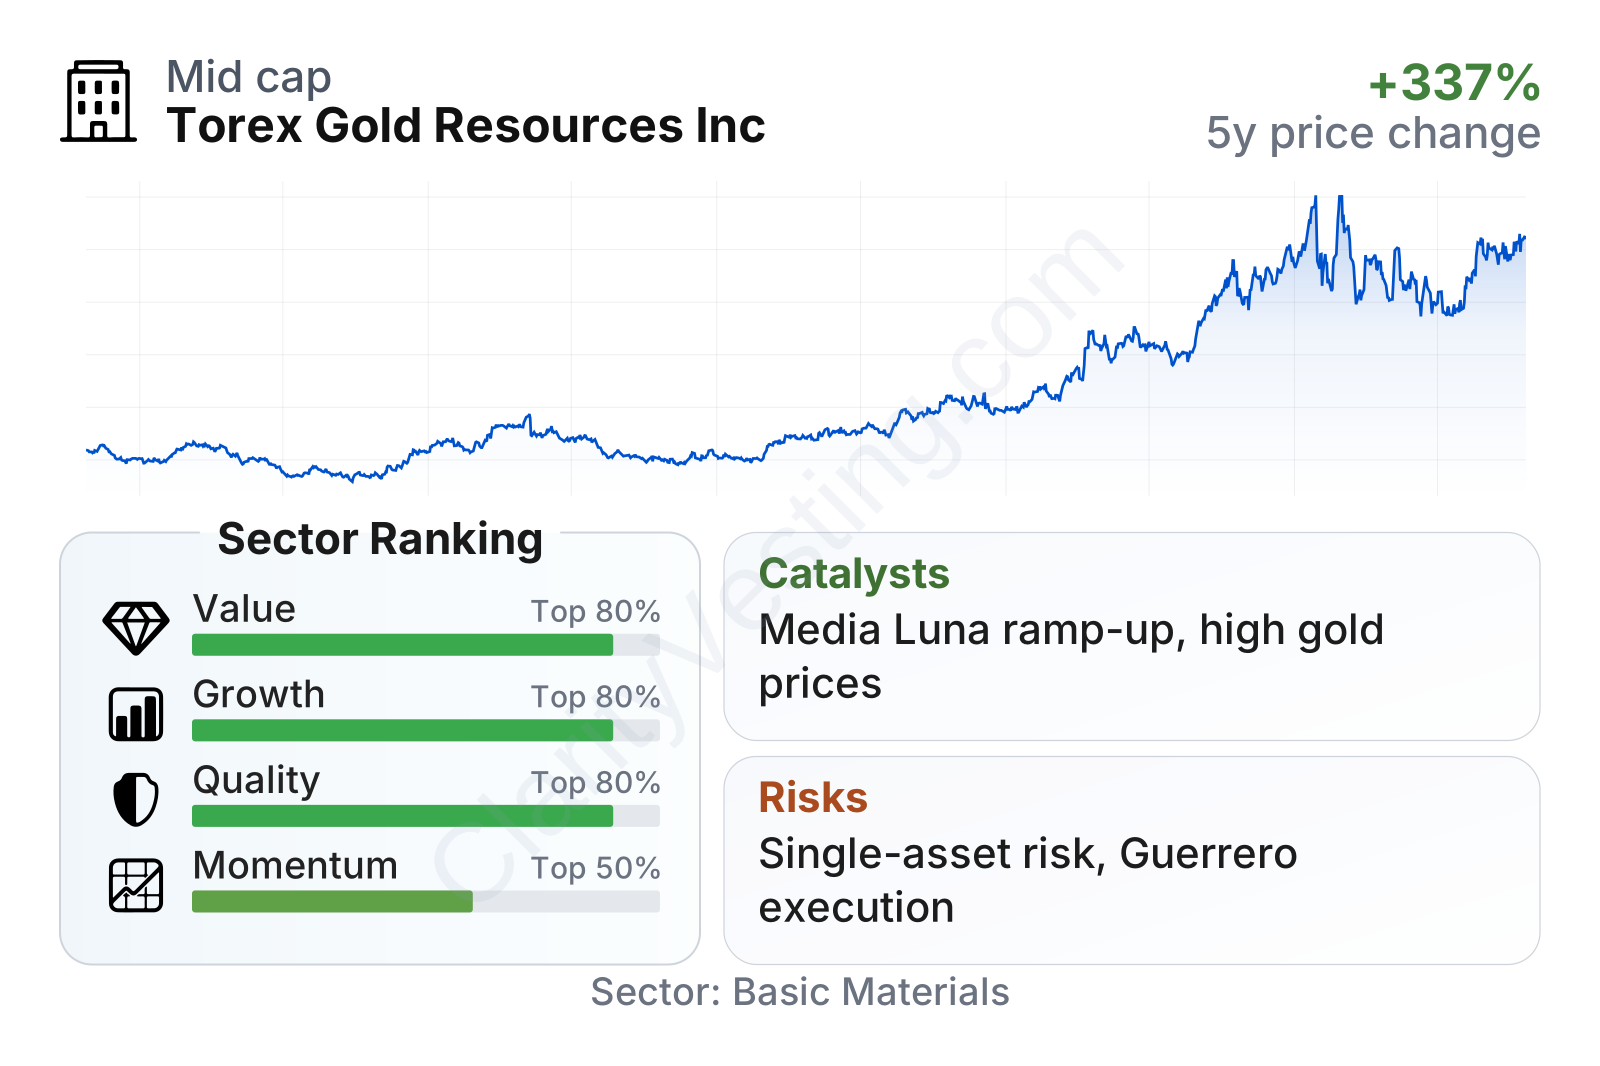
Torex stands out as a mid-sized gold producer with unusually strong profitability and balance-sheet quality for the sector. The table points to a low earnings multiple relative to peers, free cash flow yield that is well above the sector median, and growth and quality metrics that rank near the stronger end of the gold group. Momentum has also been favorable over multi-year periods, although the stock has shown meaningful swings, which is typical for a miner with exposure to both commodity prices and one main operating district.
Growth
Gold mining is not a classic high-growth industry in the way software or semiconductors can be, but it can still offer long-duration value creation when a company controls a profitable asset base, replaces reserves, and raises output efficiently. Torex operates in a sector that remains strategically relevant because gold keeps its role as a store of value, a hedge in uncertain periods, and an asset that often benefits when real interest rates or geopolitical confidence move in a favorable direction.
Torex’s growth case is centered on more than just gold prices. The key strategic driver is the transition toward Media Luna, which is meant to extend the life of the Morelos Complex and support future production. This matters because many gold miners struggle with reserve depletion. A nearby deposit that can use much of the existing infrastructure is usually more attractive than growth through large, expensive acquisitions. That lowers execution complexity compared with building an entirely new district from scratch.
Revenue growth has been volatile quarter to quarter, which is common in mining because timing of sales, grades, and maintenance periods can distort short-term comparisons. Even so, the broader direction has been strong, with recent year-over-year growth clearly ahead of the sector median and five-year per-share revenue growth also comfortably above peers.
Cash generation also shows why the company has drawn attention. Free cash flow dipped into negative territory during heavier investment periods, then recovered sharply as production and pricing improved. That rebound is important because it indicates the company has been able to fund growth spending and still move back into substantial cash creation, rather than relying on constant equity issuance or heavy leverage.
A notable recent opportunity is the combination of rising gold prices and a project pipeline that is close to existing operations. When a producer already has the plant, workforce base, and regional knowledge, additional ounces can be especially valuable. If the Media Luna ramp-up and ongoing optimization continue as planned, Torex could shift from being viewed as a single-asset producer with a finite mine life to a company with a clearer multi-year operating runway.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


