Stock Analysis · Tandem Diabetes Care Inc (TNDM)
Overview
Tandem Diabetes Care is a medical device company focused on insulin delivery for people with diabetes. Its main product family is the t:slim line of insulin pumps, including systems that work with continuous glucose monitors and software algorithms to automate part of insulin dosing. In simpler terms, the company sells devices and related supplies that help people manage diabetes more precisely than traditional insulin injections.
The business is centered on recurring use, not just one-time hardware sales. Once a person starts using a Tandem pump, they usually need ongoing infusion sets, cartridges, and software-supported ecosystem services. That makes the installed user base important because it can support repeat revenue over time.
Based on the company’s recent annual reporting structure, revenue mainly comes from the following areas:
- Insulin pump sales and renewals: approximately 45% to 55% of revenue. This includes new customer starts and replacement pumps for existing users reaching renewal cycles.
- Pump supplies: approximately 35% to 45% of revenue. This is the recurring part of the business and includes infusion sets, cartridges, and other consumables needed for continued pump use.
- Other revenue: approximately 5% to 10% of revenue. This can include software-related items, training, and smaller service or accessory categories depending on the period.
- Geographic mix: the United States remains the large majority of sales, while international markets are still smaller but strategically important for expansion.
Tandem’s financial flow over the last several years shows a business that has grown revenue from roughly $700 million in 2021 to just above $1.0 billion in 2025, but that growth has not translated into durable profitability. Gross profit improved in 2024 and 2025, yet operating expenses, especially selling costs and product development, remained high enough to keep earnings negative.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Medical Devices | |
| Market Cap ⓘ | $1.11B | |
| Beta ⓘ | 1.66 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 24.79 |
| P/B Ratio ⓘ | 8.67 | 3.08 |
| FCF Yield ⓘ | -2.39% | 3.15% |
| Dividend Yield ⓘ | N/A | 1.94% |
| EBIT / EV ⓘ | -3.71% | 0.57% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 5.80% | 7.45% |
| RPS Growth (5Y CAGR) ⓘ | 8.40% | 8.61% |
| EPS Growth (5Y CAGR) ⓘ | -11.88% | -17.81% |
| BVPS Growth (5Y CAGR) ⓘ | -23.49% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | N/A | -0.62% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 1.04% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.77% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -7.96% | 3.24% |
| ROA (Latest) ⓘ | -6.24% | 3.01% |
| ROIC (5Y Median) ⓘ | -12.79% | 4.60% |
| ROA (5Y Median) ⓘ | -10.00% | 1.89% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.84 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 1.00 |
| Net Debt / Assets ⓘ | 58.61% | 5.45% |
| EBITDA / Interest ⓘ | N/A | 9.64 |
| Operating Margin (Latest) ⓘ | -5.07% | 9.27% |
| Operating Margin (5Y Median) ⓘ | -11.05% | 7.38% |
| Debt to Equity (Latest) ⓘ | 566.96% | 28.58% |
| Profit Margin (Latest) ⓘ | -6.08% | 3.59% |
| Free Cash Flow (Latest) ⓘ | -$26.62M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -6.46% | +42.80% |
| 12M Return (excl. last month) ⓘ | +34.66% | +18.50% |
| 6M Return ⓘ | -20.04% | +7.57% |
| Price vs. 200-Day MA ⓘ | -13.79% | +5.12% |
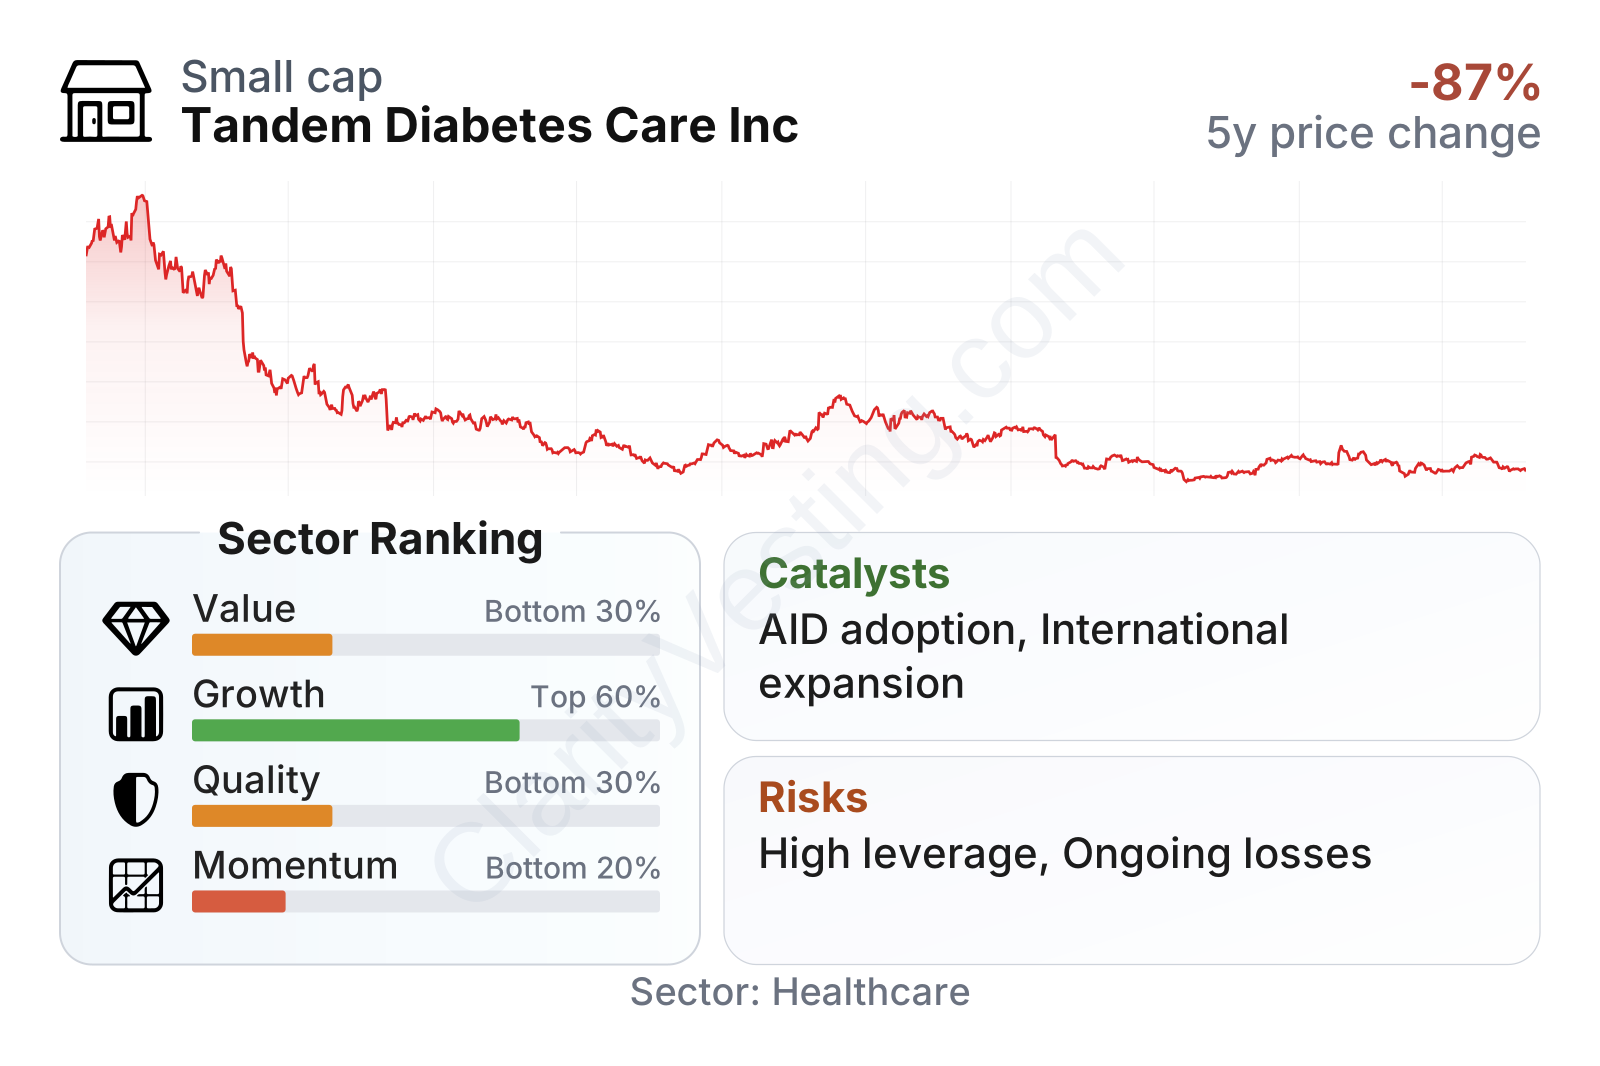
Tandem is a small-cap healthcare company with a stock that has been highly volatile. The share price is far below its 2022 peak, which reflects how sharply expectations have reset. In the latest factor snapshot, growth looks closer to the middle of the healthcare pack, but quality, valuation support, and longer-term momentum remain weak. The most important takeaway is that the market is still treating Tandem as a turnaround case rather than a stable compounder.
Growth
Diabetes technology is still a growing part of healthcare. More patients are moving toward automated insulin delivery, better glucose tracking, and connected devices that reduce daily management burden. That industry direction supports Tandem’s long-term relevance. The company operates in a segment with structural demand: diabetes is widespread, care is continuous, and technology adoption is still expanding internationally.
Tandem’s strategy also makes sense on paper. It combines hardware, recurring consumables, and software-enabled automation. That can create a stronger relationship with users than a stand-alone device sale. The launch and expansion of newer systems, broader continuous glucose monitor compatibility, and international market penetration are all visible growth levers. The company has also been working to improve manufacturing efficiency and operating discipline after a period of heavy spending.
Revenue growth has clearly been uneven. After strong expansion in 2021 and 2022, growth turned negative in 2023, then rebounded sharply in 2024, helped in part by easier comparisons and renewed commercial momentum. More recently, year-over-year growth has settled into a modest mid-single-digit range. That is a healthier pattern than the 2023 contraction, but it also shows Tandem is not currently in a rapid-growth phase.
Cash generation has improved meaningfully from the worst point, but free cash flow is still slightly negative on a trailing basis. That matters because it suggests the operating recovery is not yet complete. For a company in medical devices, recurring supply revenue is usually expected to support stronger cash conversion over time, so reaching sustainably positive free cash flow remains one of the most important markers to watch.
One recent opportunity for Tandem is continued adoption of automated insulin delivery systems as payers, physicians, and patients become more comfortable with this category. Another is the company’s ability to expand beyond its core U.S. base. If new products gain traction while supply revenue keeps compounding from the installed customer base, growth could become steadier than it has been over the last three years.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


