Stock Analysis · Telix Pharmaceuticals Limited (TLPPF)
Overview
Telix Pharmaceuticals Limited is a biotechnology company focused on radiopharmaceuticals, which are medicines that use radioactive isotopes for imaging or treatment. In simple terms, Telix develops products that help doctors find cancer more accurately and, in some cases, deliver targeted radiation directly to tumors. The company is active across prostate cancer, kidney cancer, brain cancer, and hematology, with a mix of commercial products and pipeline programs.
Its business model has shifted from a development-stage biotech toward a commercial oncology company. The largest driver is its approved prostate cancer imaging product, sold under the brand Illuccix in multiple markets. Telix also earns revenue from related product sales, licensing, and regional commercialization arrangements, while continuing to invest heavily in newer therapeutic and diagnostic candidates.
Based on recent company reporting and the revenue pattern over the last two years, Telix’s revenue sources appear concentrated as follows:
- Prostate cancer imaging products: approximately 80% to 90% of revenue. This mainly reflects PSMA-PET imaging agents used to detect and stage prostate cancer.
- Other commercial radiopharmaceutical sales and service-related revenue: approximately 5% to 15%. This can include distribution, manufacturing-related activity, and other commercialization revenue depending on the reporting period.
- Licensing, milestone, and collaboration-related revenue: typically a small and variable share. This depends on the timing of agreements and accounting recognition.
The broader financial picture shows why the market pays close attention to Telix. Revenue rose from a very small base a few years ago to well over $1 billion in 2025, while research spending also increased sharply as the company tried to turn one successful product into a broader radiopharmaceutical platform. That combination makes Telix look less like a classic early-stage biotech and more like a fast-growing oncology commercializer that is still carrying pipeline risk.
The main takeaway from the operating picture is that Telix has built a real revenue engine quickly, but it is also reinvesting aggressively. Gross profit has expanded strongly since 2023, yet rising research, commercialization, and financing costs have kept earnings more volatile than revenue alone would suggest.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Healthcare | |
| Industry | Biotechnology | |
| Market Cap ⓘ | $3.46B | |
| Beta ⓘ | 0.56 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 102.00 | 25.42 |
| P/B Ratio ⓘ | 4.63 | 3.08 |
| FCF Yield ⓘ | -2.40% | 3.12% |
| Dividend Yield ⓘ | N/A | 1.85% |
| EBIT / EV ⓘ | 1.63% | 0.56% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 22.30% | 7.50% |
| RPS Growth (5Y CAGR) ⓘ | 242.13% | 8.60% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -17.73% |
| BVPS Growth (5Y CAGR) ⓘ | 294.00% | 3.72% |
| Margin Growth (5Y Trend) ⓘ | 994.53% | -0.57% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 0.96% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 6.69% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 3.17% |
| ROA (Latest) ⓘ | 4.71% | 2.98% |
| ROIC (5Y Median) ⓘ | -70.03% | 4.56% |
| ROA (5Y Median) ⓘ | -0.67% | 1.87% |
| Net Debt / EBIT (Latest) ⓘ | 6.88 | 1.34 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 1.86 |
| Net Debt / EBITDA (Latest) ⓘ | 3.48 | 1.00 |
| Net Debt / Assets ⓘ | 24.08% | 5.06% |
| EBITDA / Interest ⓘ | 3.47 | 9.55 |
| Operating Margin (Latest) ⓘ | 2.75% | 9.25% |
| Operating Margin (5Y Median) ⓘ | 3.23% | 7.33% |
| Debt to Equity (Latest) ⓘ | 118.90% | 26.68% |
| Profit Margin (Latest) ⓘ | 3.76% | 3.34% |
| Free Cash Flow (Latest) ⓘ | -$82.76M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +68.61% | +51.61% |
| 12M Return (excl. last month) ⓘ | +34.42% | +19.90% |
| 6M Return ⓘ | -13.24% | +10.10% |
| Price vs. 200-Day MA ⓘ | -6.31% | +6.44% |
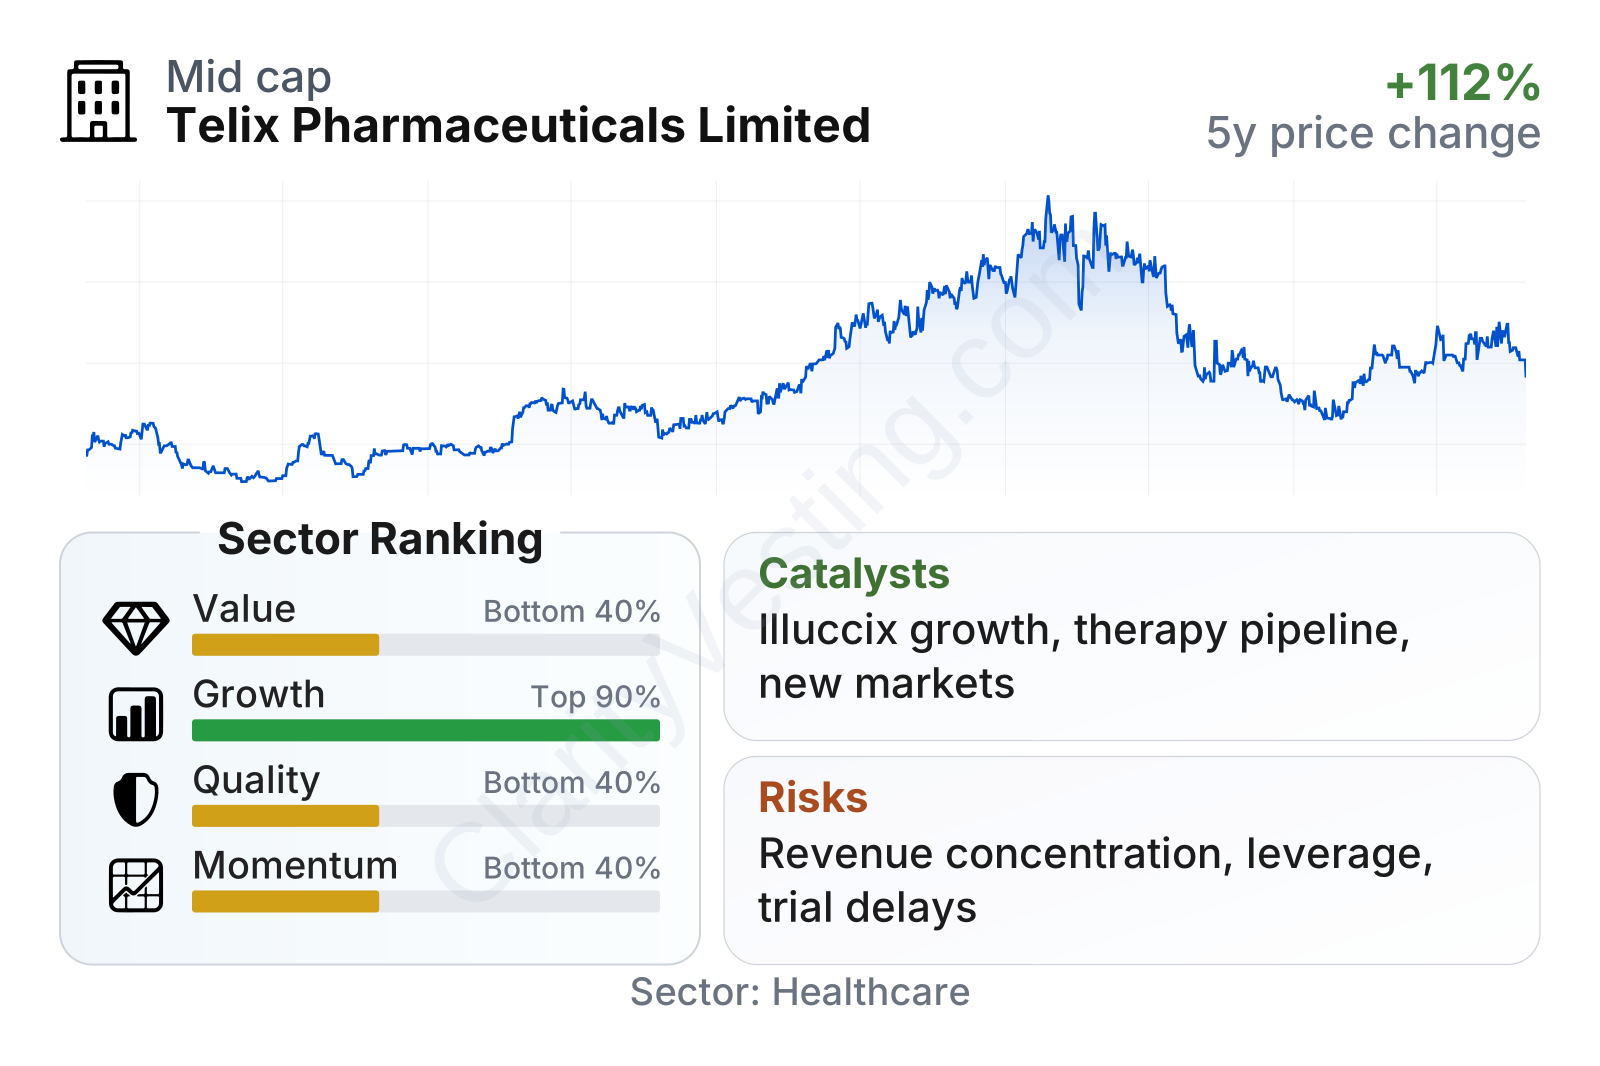
Telix stands out most on growth. Revenue growth remains well above the healthcare sector median, and the multi-year expansion in revenue per share and book value per share is unusually strong. Price performance has also been favorable over longer periods, although the share price has been volatile, with a major run-up into 2024, a steep pullback in late 2025 and early 2026, and then a partial recovery by mid-2026.
The weaker areas are valuation and balance-sheet quality. The earnings multiple is far above the sector median, price-to-book is also elevated, and free cash flow remains negative. Profitability exists, but margins are still relatively thin for a business that now has substantial scale. In other words, the market is valuing Telix more on expected future expansion than on mature, steady cash generation today.
Growth
Telix operates in one of the more promising parts of healthcare: precision oncology and radiopharmaceuticals. This field has attracted major industry attention because it combines imaging, diagnostics, and targeted treatment in a way that can improve cancer detection and potentially increase treatment effectiveness. Demand for better prostate cancer imaging has already been proven commercially, and that gives Telix a stronger starting point than many biotech companies that are still waiting for their first meaningful product revenue.
The company’s strategy is logical for future growth. It starts with a commercial base in prostate cancer imaging, then uses that installed market presence, physician relationships, and manufacturing know-how to move into additional imaging uses and therapeutic applications. That matters because radiopharmaceuticals are not just about discovering a drug candidate; they also require isotope supply, manufacturing reliability, and distribution capabilities close to the point of care. Those operational barriers can become valuable over time.
A major catalyst is the effort to expand beyond imaging into therapy. Imaging products can generate recurring revenue, but therapeutic radiopharmaceuticals usually carry higher strategic value because they can address larger treatment opportunities and create stronger competitive positioning. Telix has continued advancing kidney cancer, brain cancer, and hematology programs, and any successful late-stage clinical development or regulatory progress in those areas could materially change how the company is viewed.
Another important opportunity is geographic expansion. Telix has been broadening market access outside its original core regions, and additional regulatory clearances or reimbursement progress can increase the addressable market for existing products without requiring a completely new scientific breakthrough.
Recent company updates have also pointed to continued commercial execution, pipeline progress, and efforts to build a broader theranostics platform. For a long-term view, the key point is simple: Telix is no longer relying on a single binary event. It already has a commercial product, and the next phase is about multiplying that success across more indications, more countries, and potentially higher-value therapeutic assets.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


