Stock Analysis · Acuren Corporation (TIC)
Overview
Acuren Corporation is an industrial inspection and engineering services company. Its work is centered on helping owners of critical infrastructure keep assets safe, reliable, and compliant with regulations. In practical terms, the company tests pipelines, refineries, power facilities, manufacturing plants, and other industrial equipment to find corrosion, cracks, and other problems before they become failures. It also provides engineering, certification, and monitoring services that support maintenance programs and major projects.
The business mainly serves customers in oil and gas, petrochemical, power generation, utilities, aerospace, and broader industrial markets. This is generally a service business rather than a product business, so revenue is largely tied to technical labor, recurring inspection work, turnaround and maintenance activity, and project-based engineering support.
Based on company disclosures, Acuren’s revenue is primarily generated from service lines rather than manufactured goods. Public filings indicate the mix is broad, but not always broken out with precise percentages in a way that allows a full ranked split for every activity. The main revenue drivers can still be summarized as follows:
- Testing, inspection, and certification services — the largest source of revenue. This includes non-destructive testing, asset integrity work, field inspections, and compliance-related services performed at customer sites.
- Mechanical integrity and maintenance support — a major contributor tied to plant reliability programs, shutdowns, turnarounds, and recurring maintenance cycles.
- Engineering and consulting services — a smaller but strategic activity that includes design support, analysis, failure assessment, and specialized technical advisory work.
- Monitoring and advanced technology services — a developing area that includes higher-value diagnostics, data-driven asset monitoring, and specialty inspection techniques.
The overall financial flow shows a company that has expanded revenue materially over the last few years, but with a cost structure that also grew significantly. Gross profit improved in dollar terms, yet selling, general, and administrative expenses and interest expense rose enough to pressure operating and net results.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Specialty Business Services | |
| Market Cap ⓘ | $1.99B | |
| Beta ⓘ | 1.87 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 22.10 |
| P/B Ratio ⓘ | 0.65 | 1.97 |
| FCF Yield ⓘ | -0.07% | 6.38% |
| Dividend Yield ⓘ | N/A | 1.94% |
| EBIT / EV ⓘ | -1.17% | 4.79% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 86.10% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | -62.36% | 7.81% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -13.06% |
| BVPS Growth (5Y CAGR) ⓘ | -48.70% | 6.14% |
| Margin Growth (5Y Trend) ⓘ | -5.82% | 0.88% |
| FCF Growth (5Y CAGR) ⓘ | 53.58% | 11.01% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 9.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -0.81% | 10.84% |
| ROA (Latest) ⓘ | -2.72% | 5.41% |
| ROIC (5Y Median) ⓘ | N/A | 9.38% |
| ROA (5Y Median) ⓘ | -2.64% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 2.08 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 6.13 | 1.39 |
| Net Debt / Assets ⓘ | 31.23% | 19.28% |
| EBITDA / Interest ⓘ | 1.93 | 9.58 |
| Operating Margin (Latest) ⓘ | -1.88% | 10.50% |
| Operating Margin (5Y Median) ⓘ | 2.29% | 10.29% |
| Debt to Equity (Latest) ⓘ | 81.24% | 65.48% |
| Profit Margin (Latest) ⓘ | -5.65% | 6.67% |
| Free Cash Flow (Latest) ⓘ | -$1.39M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | N/A | +61.68% |
| 12M Return (excl. last month) ⓘ | -17.14% | +12.58% |
| 6M Return ⓘ | +9.46% | 0.00% |
| Price vs. 200-Day MA ⓘ | -1.70% | +0.02% |
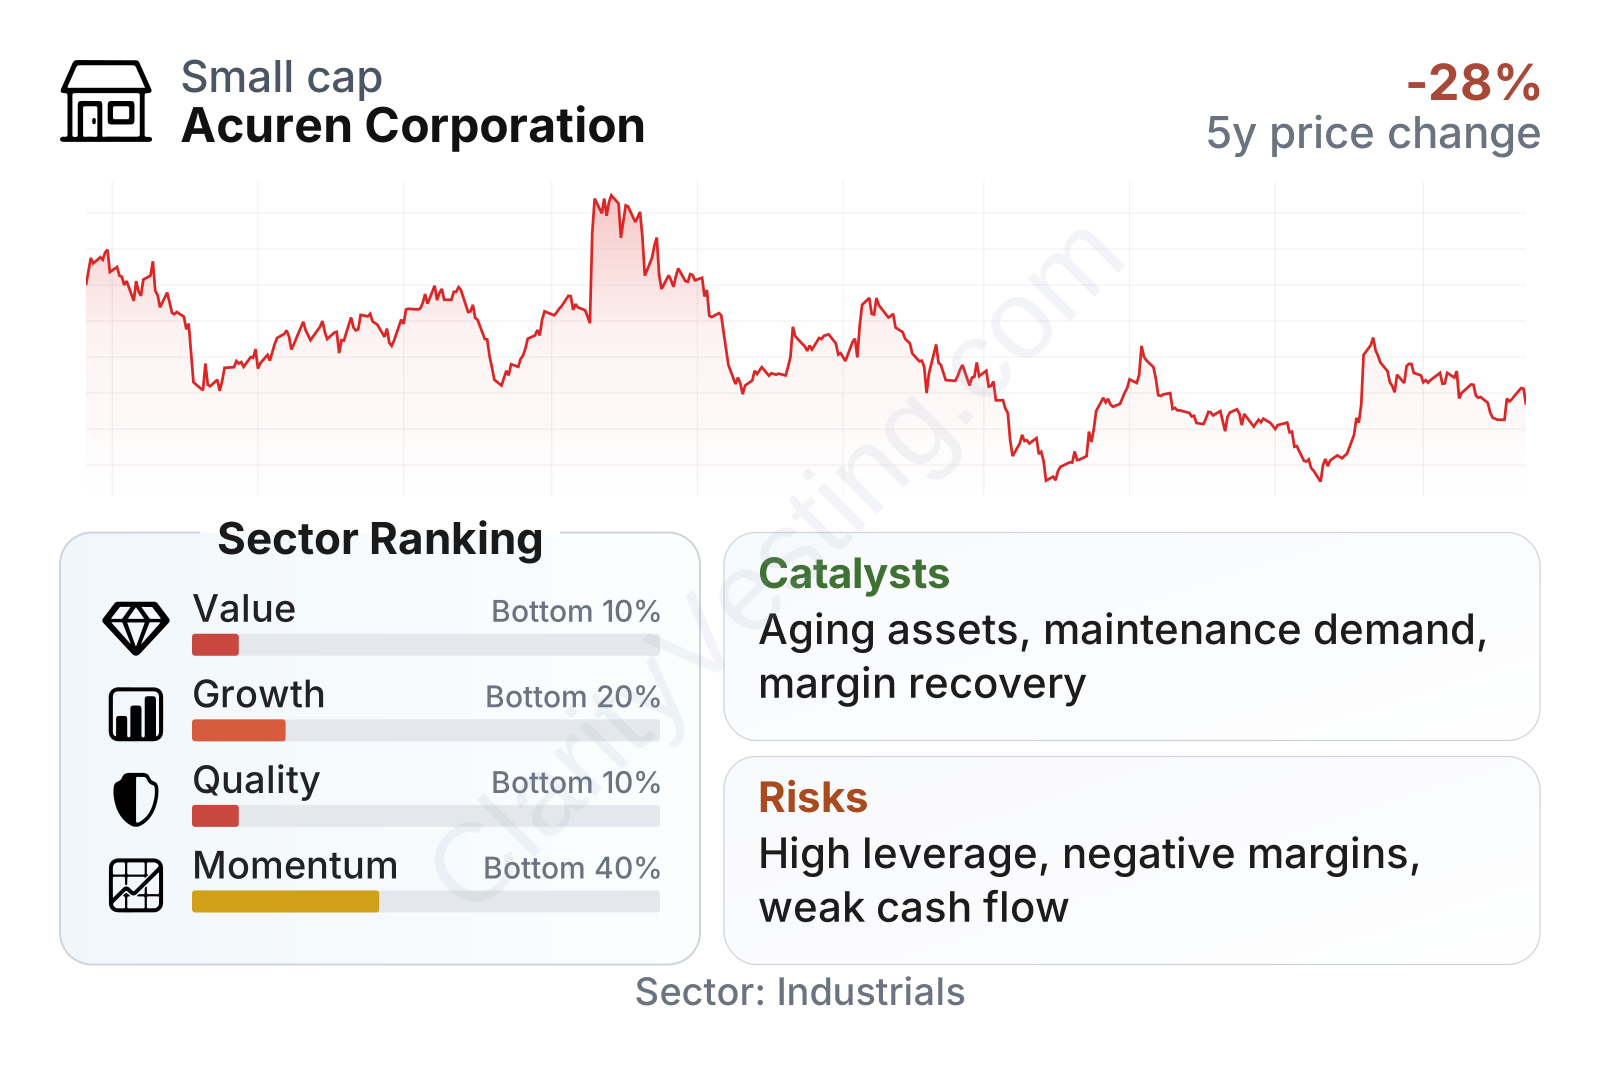
Acuren is a mid-sized industrial services company with stock volatility above the broader market, as reflected by a beta well above 1. In the factor summary, it ranks weakly versus the sector on value, quality, and growth metrics, while momentum is closer to the middle but still not strong. The sharp recent revenue expansion stands out, yet it is offset by negative returns on assets and capital, weak cash flow yield, and leverage metrics that are heavier than the sector median.
The stock’s path over the last 18 months has been uneven, with a meaningful decline from early 2025 levels before a partial rebound. That pattern suggests the market has recognized the company’s growth potential but remains cautious about profitability, debt load, and execution.
Growth
Acuren operates in a sector with durable long-term demand. Industrial assets age, safety rules tighten, and operators increasingly prefer preventive maintenance over emergency repairs. That creates a structural need for inspection, testing, and integrity services. In North America especially, energy, utilities, and process industries continue to require specialized contractors that can work across large installed asset bases.
The company’s strategy also makes logical sense for future growth. Acuren is positioned in services that are often mission-critical but relatively small compared with the cost of an equipment failure or unplanned shutdown. That tends to support recurring customer relationships. In addition, the company benefits when customers increase spending on plant uptime, regulatory compliance, and asset life extension rather than only on new construction.
Recent revenue growth has been exceptionally strong, far above the sector median. That is the clearest positive signal in the current profile. However, the very high year-over-year growth rate should be viewed carefully because growth driven by acquisitions or business combinations can be harder to translate into durable per-share gains than purely organic expansion.
Cash generation appears less convincing than revenue growth. Free cash flow was positive late in 2025 but weakened substantially afterward, and the latest trailing figure is close to break-even to slightly negative. For a company expanding quickly, this matters because long-term value creation depends not just on winning more work, but on converting that work into cash after labor, equipment, and financing costs.
A meaningful catalyst is the continued need for integrity management in energy and industrial infrastructure. Another is the company’s exposure to turnaround and maintenance cycles, where customers cannot easily defer safety-related work indefinitely. If management can improve operating discipline and capture synergies from expansion efforts, revenue scale could eventually support better margins than current results show.
Recent company communications and filings also point to ongoing positioning around broader infrastructure reliability and compliance demand. That backdrop remains supportive because many end markets served by Acuren face aging assets and stricter inspection requirements.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


