Stock Analysis · Tecnoglass Inc (TGLS)
Overview
Tecnoglass is a building products manufacturer focused on architectural glass, windows, and aluminum systems used in residential and commercial construction. The company was founded in Colombia and serves customers across the Americas, with the United States as its main end market. Its products are used in high-rise buildings, office towers, hotels, single-family homes, and multifamily projects. A key feature of the business is vertical integration: Tecnoglass processes raw glass, manufactures finished windows and related aluminum components, and delivers customized systems for large projects as well as standard products for housing markets.
The business is organized around two main product categories, with revenue heavily concentrated in glass and glazing products. Based on recent company reporting, the mix is approximately:
- Architectural glass and related products: about 77% of revenue. This includes tempered, laminated, insulating, and other processed glass products used in façades, curtain walls, windows, and doors.
- Windows and aluminum products: about 23% of revenue. This includes windows, doors, aluminum profiles, and associated systems used in residential and commercial installations.
Geographically, Tecnoglass depends mainly on the United States, which represents the large majority of sales, while Colombia and other markets contribute a much smaller share. That concentration reflects the company’s strategy: manufacture at scale in Colombia, then ship into U.S. markets where demand and pricing are more attractive.
Over the last several years, revenue has expanded strongly, while the company has kept unusually high profitability for a building materials business. The flow of revenue to gross profit and operating income still shows a business with solid conversion, even though margins have come down from peak levels reached during the strongest recent cycle.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Building Materials | |
| Market Cap ⓘ | $1.67B | |
| Beta ⓘ | 1.42 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 13.16 | 16.90 |
| P/B Ratio ⓘ | 2.07 | 1.65 |
| FCF Yield ⓘ | 2.62% | 5.76% |
| Dividend Yield ⓘ | 1.56% | 2.13% |
| EBIT / EV ⓘ | 11.51% | 6.30% |
| PEG ⓘ | 0.47 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 15.60% | 11.10% |
| RPS Growth (5Y CAGR) ⓘ | 19.25% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | -71.51% | -13.47% |
| BVPS Growth (5Y CAGR) ⓘ | 31.57% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | 2.43% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | -14.89% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 53.00% | 6.08% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 13.99% | 9.26% |
| ROA (Latest) ⓘ | 9.76% | 4.91% |
| ROIC (5Y Median) ⓘ | 22.85% | 7.70% |
| ROA (5Y Median) ⓘ | 16.30% | 3.86% |
| Net Debt / EBIT (Latest) ⓘ | 0.74 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | 0.27 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | 0.61 | 0.95 |
| Net Debt / Assets ⓘ | 10.11% | 13.69% |
| EBITDA / Interest ⓘ | N/A | 12.34 |
| Operating Margin (Latest) ⓘ | 18.68% | 13.20% |
| Operating Margin (5Y Median) ⓘ | 26.13% | 11.80% |
| Debt to Equity (Latest) ⓘ | 28.58% | 40.56% |
| Profit Margin (Latest) ⓘ | 12.36% | 6.43% |
| Free Cash Flow (Latest) ⓘ | $43.79M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +15.68% | +68.89% |
| 12M Return (excl. last month) ⓘ | -47.31% | +30.21% |
| 6M Return ⓘ | -18.95% | -4.16% |
| Price vs. 200-Day MA ⓘ | -15.76% | -1.27% |
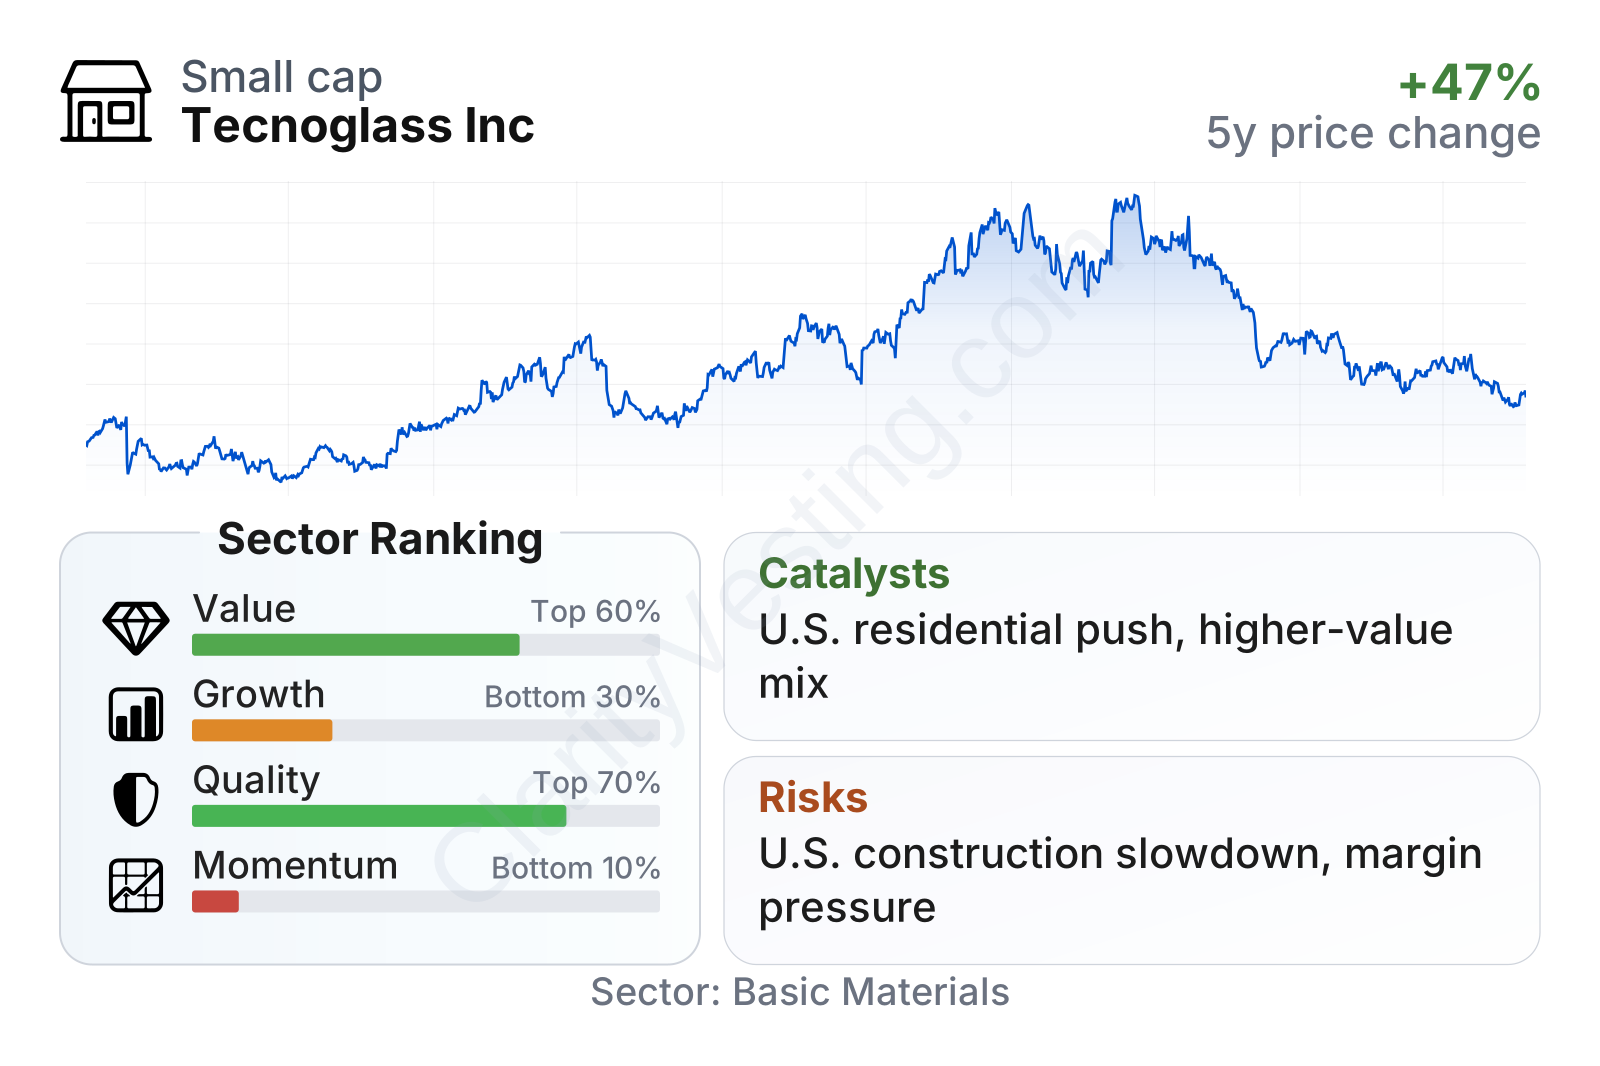
Tecnoglass is a mid-cap company with a share price history that has been volatile: the stock climbed sharply through 2023 and 2024, then gave back a meaningful portion of those gains in 2025 and 2026. In the latest factor snapshot, quality stands out more than momentum or headline growth. Profitability and returns on capital remain better than many peers in building materials, while leverage is moderate. On valuation, earnings multiples are below the sector median, and EBIT relative to enterprise value remains above the sector median, which suggests the market is not assigning an aggressive price compared with current operating earnings. The weaker areas are recent share-price momentum and free-cash-flow yield, which looks less favorable after cash generation cooled from earlier levels.
Growth
Tecnoglass operates in a sector that benefits from long-term needs rather than fast-changing technology trends: housing, renovation, commercial construction, energy-efficient buildings, and storm-resistant building envelopes. That makes it cyclical, but not structurally obsolete. Demand for impact-resistant windows and high-performance architectural glass remains supported by stricter building codes, especially in hurricane-prone regions such as Florida, where Tecnoglass has a strong presence.
The company’s strategy is straightforward and easy to understand. It combines low-cost manufacturing in Colombia with distribution into the U.S., especially the Southeast. That can work well when construction demand is healthy because it gives Tecnoglass a cost advantage while allowing it to serve both large commercial projects and the residential replacement market. The company has also been expanding its single-family residential reach, which helps diversify away from dependence on large towers and commercial developments.
Revenue growth has been uneven, which is normal for a project-driven construction supplier. After a very strong period in 2022 and 2023, growth slowed and even turned negative for some quarters before reaccelerating. More recently, year-over-year sales growth moved back into the mid-teens range, which suggests demand has stabilized better than the share price might imply. Over a five-year view, revenue per share growth has remained far stronger than the sector median.
Cash generation deserves a more careful reading. Free cash flow has stayed positive over time, but it has also been lumpy and recently much lower than earlier peaks. For a manufacturer tied to project timing, inventory needs, and capital spending, that pattern is not unusual. Still, future growth will look stronger if earnings once again convert into cash more consistently.
A meaningful catalyst is capacity and mix expansion. Management has emphasized scaling higher-value products, deeper penetration of the U.S. residential market, and continued investment in automation and productivity. Another visible support is the company’s backlog and order pipeline commentary in recent corporate updates, which points to ongoing demand despite a tougher construction environment. In addition, lower interest expense over recent years has improved financial flexibility, leaving more room for reinvestment and shareholder returns.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


