Stock Analysis · Triple Flag Precious Metals Corp (TFPM)
Overview
Triple Flag Precious Metals Corp is a precious-metals royalty and streaming company. In simple terms, it does not usually operate mines itself. Instead, it provides financing to mine developers and operators in exchange for a contractual right to receive a share of future metal production or revenue. This model is often viewed as less operationally risky than running mines directly because Triple Flag is generally not responsible for day-to-day mining costs, labor issues, or site management.
The company’s portfolio is focused on gold and silver, with smaller exposure to other metals and mining interests. Its assets are spread across producing mines, development projects, and exploration-stage properties, which gives it a mix of current cash generation and longer-term optionality. Triple Flag has built this portfolio through direct deals, acquisitions, and partnerships with mining companies across multiple jurisdictions.
Based on the company’s recent annual disclosures, revenue is primarily tied to precious metals, with gold clearly dominant. The mix can shift from year to year depending on metal prices, mine output, and the timing of deliveries, but the broad picture is:
- Gold: approximately 75% to 85% of revenue. This mainly reflects streams and royalties linked to gold-producing mines.
- Silver: approximately 10% to 20% of revenue. This includes silver streams and royalty interests where silver is either the main commodity or a by-product.
- Other revenue sources: approximately 5% to 10% of revenue. This may include interests tied to other metals, contractual payments, and occasional accounting effects related to the portfolio.
One of the most attractive features of the business model is the gap between revenue and operating costs. Over the last several years, sales have expanded materially while direct costs have remained comparatively modest, which is typical for royalty and streaming companies when their assets are performing well. That said, accounting charges and portfolio revaluations can still create swings in reported earnings from one year to the next.
The long-term trend shows a business that has scaled revenue meaningfully, while preserving strong gross economics. The unusually weak net result in 2024 stands out more as a reminder that non-cash charges and one-off items can distort bottom-line profit than as evidence of a broken operating model.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 24, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Other Precious Metals & Mining | |
| Market Cap ⓘ | $6.34B | |
| Beta ⓘ | 0.31 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 15.46 | 16.92 |
| P/B Ratio ⓘ | 2.79 | 1.66 |
| FCF Yield ⓘ | -3.44% | 5.83% |
| Dividend Yield ⓘ | 0.75% | 2.07% |
| EBIT / EV ⓘ | 6.26% | 6.38% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 37.30% | 11.25% |
| RPS Growth (5Y CAGR) ⓘ | 17.52% | 4.49% |
| EPS Growth (5Y CAGR) ⓘ | 21.09% | -15.24% |
| BVPS Growth (5Y CAGR) ⓘ | 3.42% | 5.49% |
| Margin Growth (5Y Trend) ⓘ | 31.57% | -1.54% |
| FCF Growth (5Y CAGR) ⓘ | 7.77% | 0.37% |
| DPS Growth (5Y CAGR) ⓘ | 22.89% | 5.91% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 25.85% | 9.59% |
| ROA (Latest) ⓘ | 17.82% | 4.92% |
| ROIC (5Y Median) ⓘ | 3.59% | 7.91% |
| ROA (5Y Median) ⓘ | 3.50% | 3.92% |
| Net Debt / EBIT (Latest) ⓘ | 0.49 | 1.36 |
| Net Debt / EBIT (5Y Median) ⓘ | -0.68 | 1.69 |
| Net Debt / EBITDA (Latest) ⓘ | 0.44 | 0.93 |
| Net Debt / Assets ⓘ | 8.55% | 13.69% |
| EBITDA / Interest ⓘ | 230.58 | 12.38 |
| Operating Margin (Latest) ⓘ | 92.30% | 13.24% |
| Operating Margin (5Y Median) ⓘ | 38.82% | 11.82% |
| Debt to Equity (Latest) ⓘ | 10.30% | 40.30% |
| Profit Margin (Latest) ⓘ | 84.32% | 6.38% |
| Free Cash Flow (Latest) ⓘ | -$217.94M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +144.88% | +73.47% |
| 12M Return (excl. last month) ⓘ | +16.42% | +27.59% |
| 6M Return ⓘ | -9.71% | -4.02% |
| Price vs. 200-Day MA ⓘ | -6.51% | -0.65% |
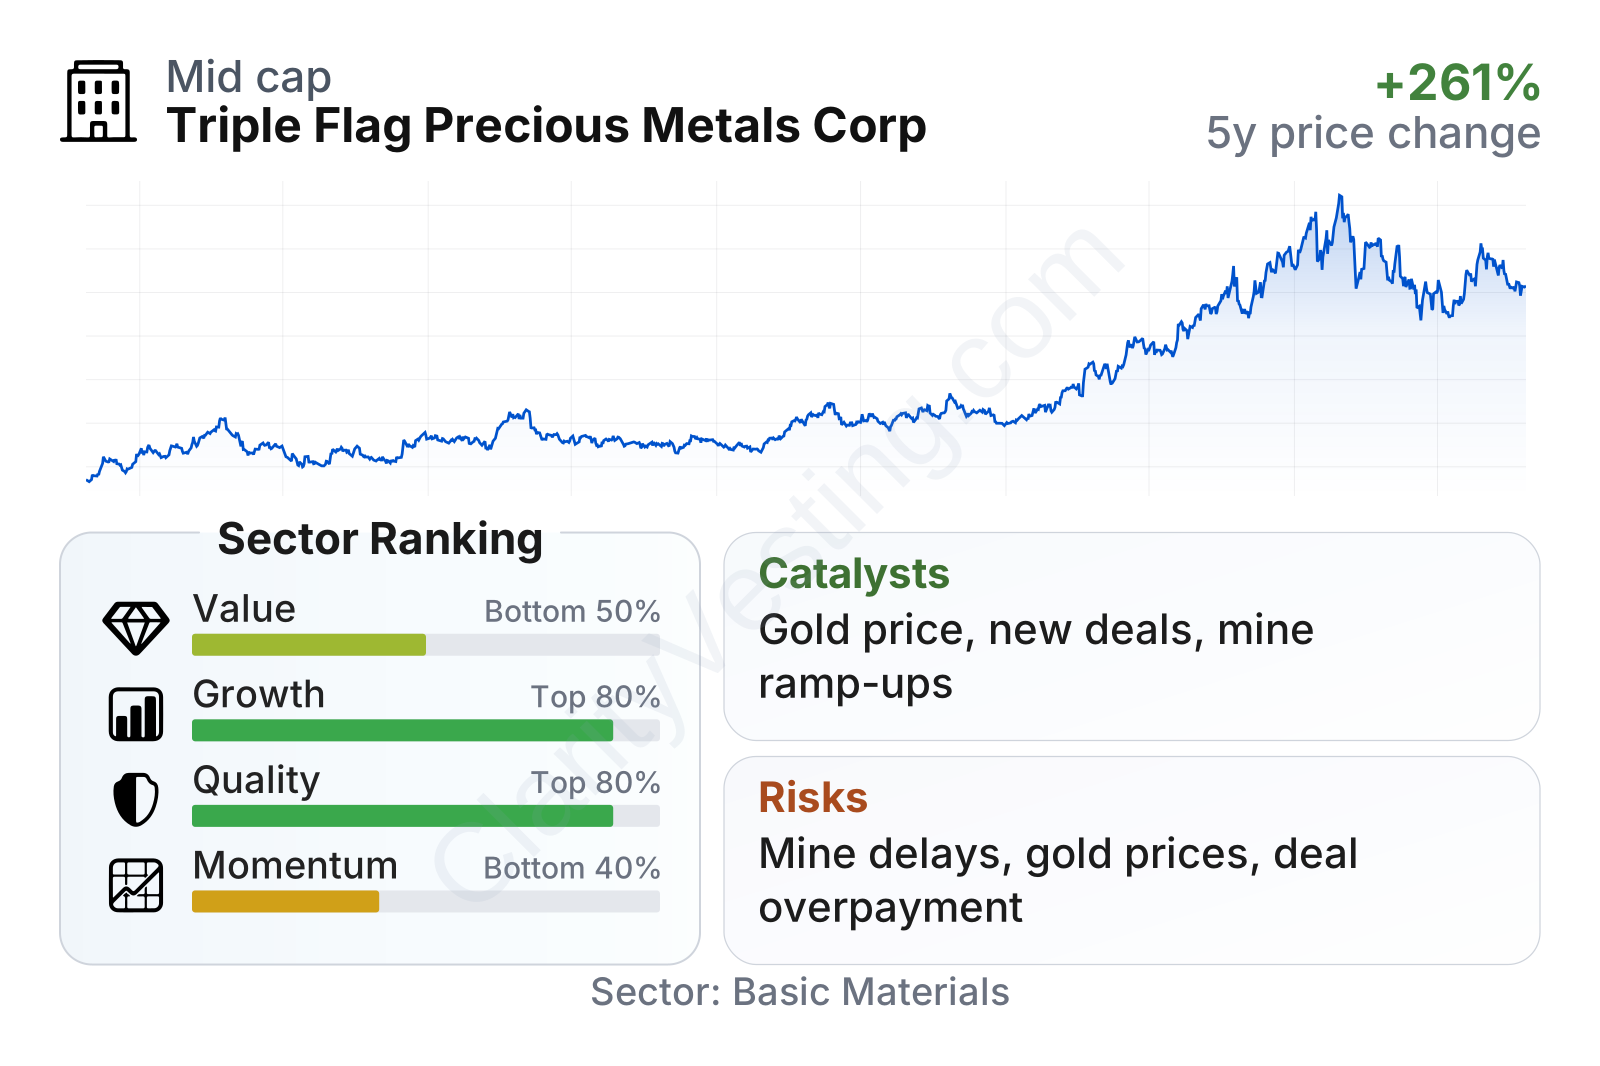
Triple Flag sits in the larger end of the royalty and streaming niche, with a market value around the mid-single-digit billions and a notably low beta, meaning the stock has historically moved less violently than many mining names. The overall factor picture is mixed in a sensible way: growth and quality rank strongly against the sector, while value and recent momentum are less impressive. In plain language, the market appears to be recognizing the company’s business quality, so the shares are not especially cheap on all measures, even though earnings-based valuation is not stretched versus the broader materials group.
Growth
Triple Flag operates in a sector that still has room to grow. Royalty and streaming companies have become an important financing source for the mining industry because mine developers often need capital without taking on too much traditional debt or issuing too much equity. That gives companies like Triple Flag a continuing pipeline of potential deals, especially when banks and capital markets are selective.
The strategy also makes sense for long-term expansion. Rather than betting everything on one mine, Triple Flag builds a portfolio of claims on many projects. If management allocates capital well, this can create a diversified stream of production growth over time. The company also benefits when existing counterparties expand reserves, extend mine life, or bring new phases into production, because Triple Flag may receive more ounces without having to spend large amounts of additional operating capital.
Recent revenue growth has been strong and clearly above the sector median. The pattern is not perfectly smooth, which is normal in this business, but the broader direction has been favorable. The latest year-over-year pace remains robust even after a very strong 2025, suggesting the recent expansion is not just a one-quarter anomaly.
Cash generation has also improved significantly over time. The longer trend in free cash flow is positive, even if short-term reported free-cash-flow figures can occasionally look messy because new deal funding can temporarily absorb cash. For a royalty company, that is an important distinction: a weaker near-term cash figure is not always operational weakness if it reflects reinvestment into new streams and royalties.
A major catalyst is precious-metals pricing. Higher gold and silver prices can lift revenue and margins quickly because the company’s cost base is relatively light. Another important catalyst is asset conversion: development-stage projects moving into production can add volume without requiring Triple Flag to build mines itself. The portfolio structure means a few successful ramp-ups can have an outsized effect on results.
Recent corporate updates have also pointed to continued portfolio development, with management emphasizing new deal opportunities and a pipeline of assets at different stages. For a company in this niche, sustained access to transactions is central to future growth, and Triple Flag appears to remain active on that front.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


