Stock Analysis · Technogym S.p.A (TCCHF)
Overview
Technogym S.p.A is an Italian wellness and fitness company best known for premium exercise equipment, connected training platforms, and design-oriented solutions used in gyms, hotels, medical settings, corporate wellness spaces, and homes. The company positions itself not just as an equipment maker, but as a broader wellness brand that combines machines, software, digital content, and services.
Its business model is built around selling physical equipment first, then expanding the customer relationship through connected services, training content, and recurring support. That matters for long-term analysis because it gives Technogym exposure to both durable product demand and the more attractive software-and-service layer that can deepen customer loyalty over time.
Based on company reporting, Technogym’s revenue mix is primarily organized by end market rather than by individual product line. The main sources of revenue appear to be:
- Commercial / B2B wellness solutions: the largest contributor, likely around 75% to 85% of revenue. This includes equipment and connected solutions for fitness clubs, hotels, resorts, health centers, corporate wellness programs, and public institutions.
- Consumer / home wellness: likely around 15% to 25% of revenue. This includes premium home fitness equipment and digital training experiences sold directly or through distribution partners.
- Services and digital ecosystem: a smaller but strategically important share embedded across both segments. This includes maintenance, software, subscriptions, and connected platform services, though a precise standalone percentage is not consistently disclosed.
Geographically, Technogym is an international company with Europe still the core market, while North America, Asia-Pacific, and the Middle East offer additional room for expansion. The financial profile also shows a business that has been scaling: revenue rose from about €611 million in 2021 to just over €1.0 billion in 2025, while net income and operating profit also moved higher over that period. At a high level, the business appears to be converting growth into stronger profitability rather than simply chasing volume.
The long-term trend points to rising revenue, expanding operating profit, and healthy net income conversion. Selling and administrative costs have grown with the business, but profit has still widened, which suggests Technogym has preserved pricing power and brand strength while scaling.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Consumer Cyclical | |
| Industry | Leisure | |
| Market Cap ⓘ | $4.78B | |
| Beta ⓘ | 0.87 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 35.82 | 17.04 |
| P/B Ratio ⓘ | 16.12 | 1.61 |
| FCF Yield ⓘ | 4.84% | 9.02% |
| Dividend Yield ⓘ | 1.58% | 2.75% |
| EBIT / EV ⓘ | N/A | 6.69% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 7.40% | 5.60% |
| RPS Growth (5Y CAGR) ⓘ | 13.94% | 9.04% |
| EPS Growth (5Y CAGR) ⓘ | -37.76% | -17.44% |
| BVPS Growth (5Y CAGR) ⓘ | 1.96% | 5.73% |
| Margin Growth (5Y Trend) ⓘ | 2.69% | -0.26% |
| FCF Growth (5Y CAGR) ⓘ | 21.58% | 4.91% |
| DPS Growth (5Y CAGR) ⓘ | 38.87% | 10.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 46.42% | 12.38% |
| ROA (Latest) ⓘ | 23.49% | 5.54% |
| ROIC (5Y Median) ⓘ | 21.22% | 10.63% |
| ROA (5Y Median) ⓘ | 9.18% | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | -0.38 | 2.16 |
| Net Debt / EBIT (5Y Median) ⓘ | -1.22 | 2.31 |
| Net Debt / EBITDA (Latest) ⓘ | -0.27 | 1.52 |
| Net Debt / Assets ⓘ | -9.46% | 21.74% |
| EBITDA / Interest ⓘ | 7.92 | 9.06 |
| Operating Margin (Latest) ⓘ | 11.15% | 9.12% |
| Operating Margin (5Y Median) ⓘ | 13.18% | 9.56% |
| Debt to Equity (Latest) ⓘ | 41.16% | 76.18% |
| Profit Margin (Latest) ⓘ | 11.07% | 5.30% |
| Free Cash Flow (Latest) ⓘ | $231.46M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +182.74% | +11.77% |
| 12M Return (excl. last month) ⓘ | +74.61% | +0.61% |
| 6M Return ⓘ | +74.61% | +1.32% |
| Price vs. 200-Day MA ⓘ | +20.30% | -3.47% |
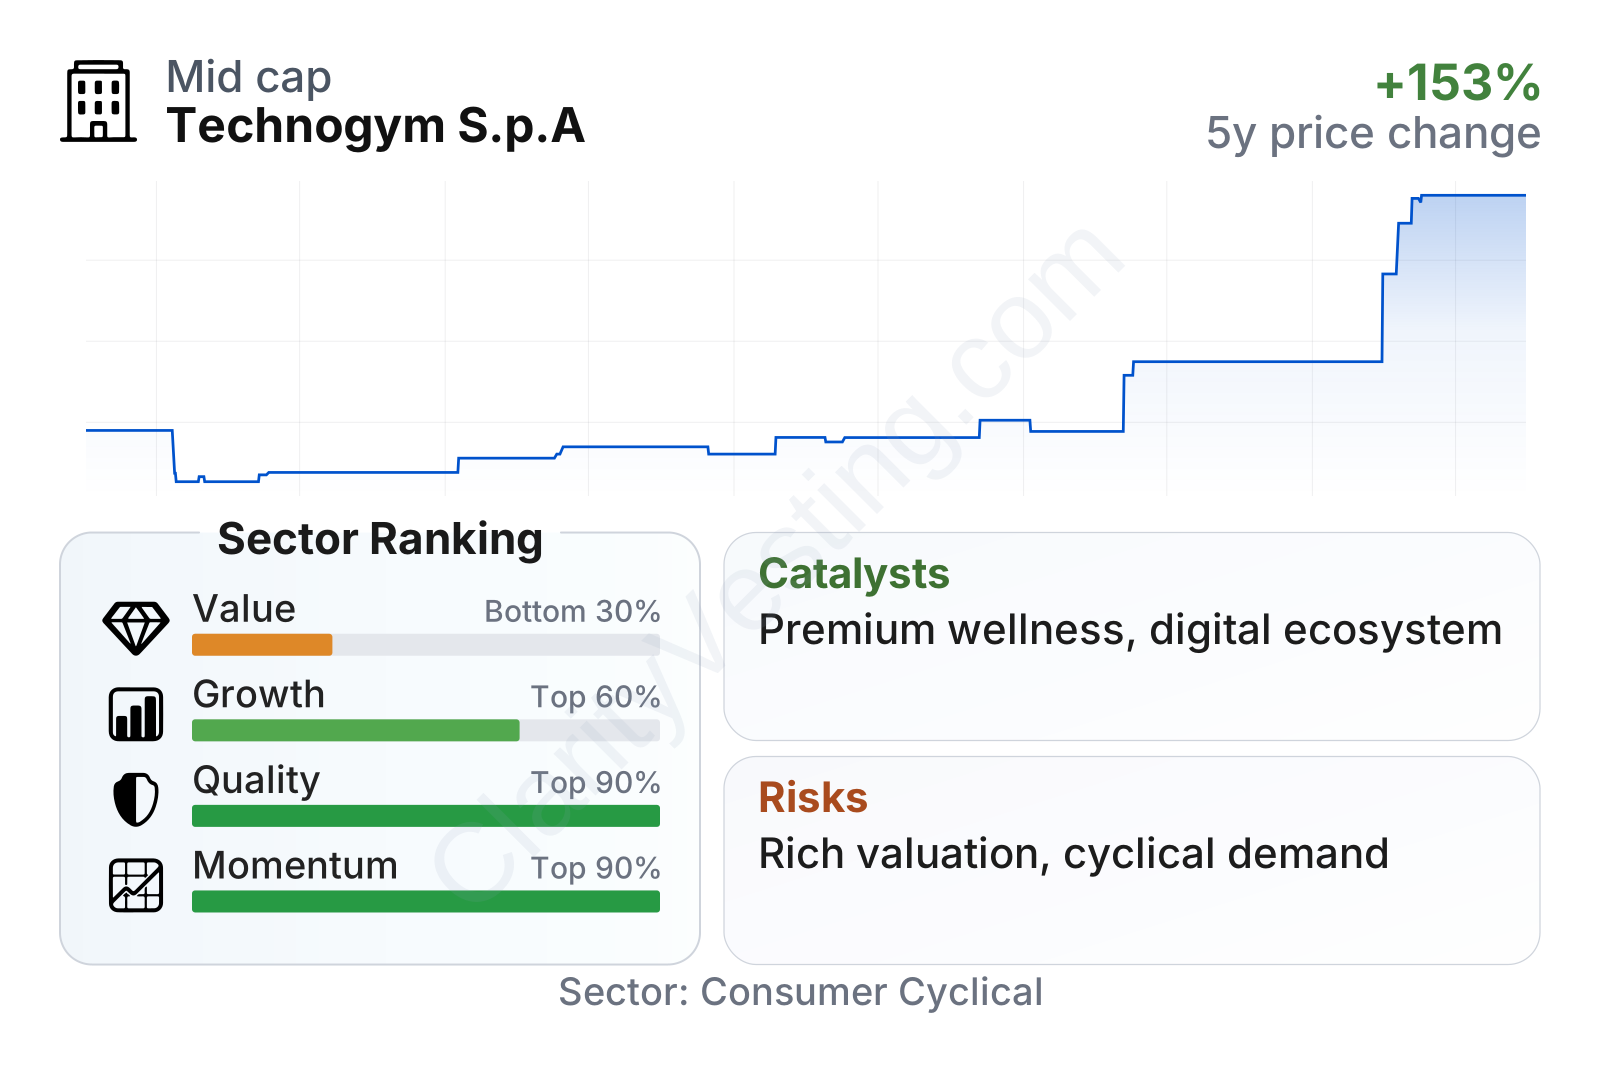
Technogym stands out for business quality more than for cheapness. Profitability and capital efficiency are well above the sector median, with returns on capital and assets in particularly strong territory. The balance sheet is also a notable strength, with net cash rather than heavy leverage. Growth metrics are mixed but generally constructive: revenue and free cash flow trends look solid, while earnings growth over a five-year view is less flattering, likely reflecting earlier volatility and comparison effects. Market performance has been very strong, but that has pushed valuation measures well above the broader sector.
The stock history also shows a sharp re-rating. After trading at much lower levels in 2022, the shares climbed strongly through 2025 and 2026. That kind of move usually signals improved confidence in the company’s execution, but it also raises the bar for future operating performance.
Growth
Technogym operates in a sector with credible long-term support: aging populations, rising awareness of preventive health, continued interest in fitness and longevity, and growing demand for connected wellness experiences. The business sits at the intersection of fitness equipment, digital coaching, corporate wellness, hospitality, and health-oriented lifestyle spending. That gives it more than one path to expansion.
The company’s strategy also makes sense for future growth because it is not limited to selling standalone machines. Technogym has built an ecosystem around hardware, software, content, and services. In practice, this can improve customer retention and support higher-value relationships, especially with gyms, hotels, and institutions that want integrated solutions rather than one-off purchases.
Revenue momentum has remained positive and has outpaced the sector median on the latest yearly comparison. Over a five-year period, revenue per share growth has also been ahead of the sector, while free cash flow growth has been particularly strong. That combination suggests expansion has not been purely accounting-driven; cash generation has also improved materially.
A meaningful catalyst is Technogym’s positioning in premium wellness environments. Luxury hospitality, corporate wellness programs, and high-end home fitness all fit the company’s brand and design-led approach. Another potential driver is the continued digitization of fitness experiences, where connected platforms can make equipment more valuable and create recurring revenue opportunities.
The company also benefits from visibility linked to elite sports and major athletic events, which reinforces brand recognition globally. That does not automatically translate into immediate revenue, but it strengthens Technogym’s premium image in a market where reputation matters.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


