Stock Analysis · Talos Energy (TALO)
Overview
Talos Energy is an independent U.S. oil and gas producer. In simple terms, it explores for hydrocarbons, develops offshore fields, operates wells, and sells the oil, natural gas, and natural gas liquids it produces. The company is best known for its offshore position in the U.S. Gulf of America, where it has built a portfolio of producing assets, development projects, and exploration prospects. Talos also has a carbon capture and storage business, but that operation is still small compared with the core oil and gas segment.
Revenue mainly comes from selling produced commodities. Based on recent company filings, the mix changes with production volumes and commodity prices, but the business is dominated by oil. A practical breakdown is:
- Oil sales: approximately 74% to 79% of revenue. This is the largest earnings driver and reflects Talos’s offshore crude production.
- Natural gas sales: approximately 16% to 20% of revenue. This includes gas sold from its offshore properties.
- Natural gas liquids sales: approximately 4% to 7% of revenue. These are hydrocarbon liquids separated from gas production.
- Other revenue: a very small contribution, generally tied to miscellaneous operating and marketing items rather than a major standalone business line.
Geographically, Talos is overwhelmingly tied to the United States through its offshore Gulf production base. That concentration makes the company easier to understand than global majors, but it also means performance depends heavily on a narrower asset set and project pipeline.
The financial flow over recent years shows an important pattern: revenue expanded strongly through 2024, but costs rose as well, especially production-related expenses and interest expense. That helps explain why high sales did not translate into equally strong bottom-line results by 2025.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Energy | |
| Industry | Oil & Gas E&P | |
| Market Cap ⓘ | $2.71B | |
| Beta ⓘ | 0.36 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 14.47 |
| P/B Ratio ⓘ | 1.37 | 1.70 |
| FCF Yield ⓘ | 12.22% | 8.66% |
| Dividend Yield ⓘ | N/A | 3.77% |
| EBIT / EV ⓘ | -11.85% | 7.46% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 56.60% | 27.35% |
| RPS Growth (5Y CAGR) ⓘ | -9.60% | 6.75% |
| EPS Growth (5Y CAGR) ⓘ | -24.39% | -15.45% |
| BVPS Growth (5Y CAGR) ⓘ | 7.40% | 5.85% |
| Margin Growth (5Y Trend) ⓘ | -20.65% | 0.75% |
| FCF Growth (5Y CAGR) ⓘ | 40.03% | 3.62% |
| DPS Growth (5Y CAGR) ⓘ | -15.09% | 16.85% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | -9.54% | 11.33% |
| ROA (Latest) ⓘ | -7.31% | 6.03% |
| ROIC (5Y Median) ⓘ | 2.53% | 10.16% |
| ROA (5Y Median) ⓘ | -1.39% | 5.34% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 1.62 |
| Net Debt / EBIT (5Y Median) ⓘ | 3.87 | 1.91 |
| Net Debt / EBITDA (Latest) ⓘ | 1.01 | 1.06 |
| Net Debt / Assets ⓘ | 12.24% | 17.29% |
| EBITDA / Interest ⓘ | 2.71 | 9.64 |
| Operating Margin (Latest) ⓘ | -20.54% | 16.32% |
| Operating Margin (5Y Median) ⓘ | 5.89% | 19.53% |
| Debt to Equity (Latest) ⓘ | 61.14% | 54.41% |
| Profit Margin (Latest) ⓘ | -20.46% | 8.79% |
| Free Cash Flow (Latest) ⓘ | $330.79M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -0.67% | +62.93% |
| 12M Return (excl. last month) ⓘ | +74.70% | +44.83% |
| 6M Return ⓘ | +3.62% | -1.62% |
| Price vs. 200-Day MA ⓘ | +14.29% | +5.18% |
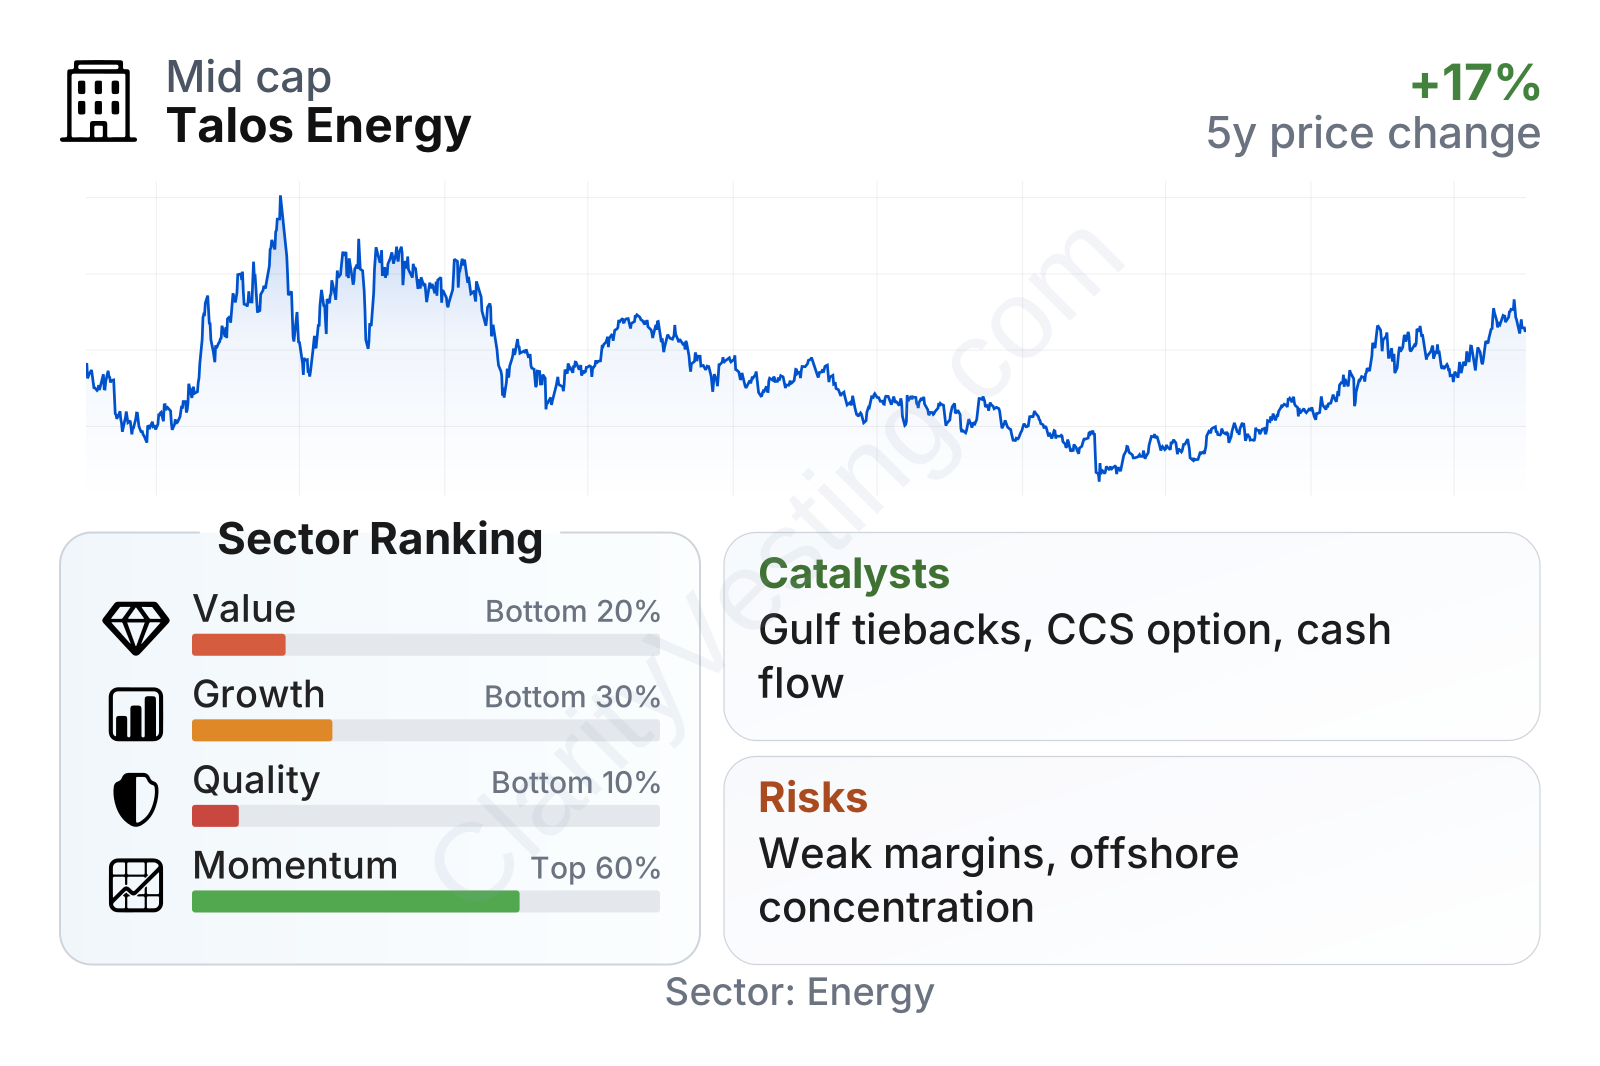
Talos sits in the small-to-mid-cap range within the energy sector, with a market value around the low single-digit billions of dollars. The stock’s beta is low for an oil and gas producer, which is unusual given the sector’s normal volatility. In factor terms, the company currently looks weak on value, growth, and especially quality, while recent momentum has been better than much of the sector. One notable contrast is that free cash flow yield is relatively strong, but profitability and returns on capital are significantly weaker than sector norms.
The share-price history also shows how cyclical the market’s view has been. The stock traded much higher during stronger commodity conditions, fell sharply into 2025, and then recovered meaningfully in 2026. That pattern fits a company whose valuation is highly sensitive to operating execution, commodity prices, and confidence in future offshore developments.
Growth
Talos operates in a sector that still has long-term relevance, even though it is not a classic high-growth industry. Oil and gas demand remains substantial, and offshore supply can become more valuable when existing fields decline and replacement barrels are harder to find. For Talos, growth is less about industry expansion and more about disciplined reserve replacement, higher-margin project execution, and extending the life of its offshore infrastructure.
The company’s strategy is logically built around assets where it believes technical expertise matters: deepwater and offshore operations, infrastructure-led tiebacks, and acquisitions that can add reserves near existing hubs. This can be a sensible model because offshore projects often benefit from existing platforms and pipelines, which can lower development costs and shorten timelines compared with building entirely new systems.
Revenue growth has been volatile rather than smooth. Recent year-over-year growth rebounded sharply by mid-2026, rising well above the sector median, but the path included several quarters of contraction beforehand. That is a reminder that Talos’s growth profile is heavily influenced by production timing, acquisitions, and realized commodity prices rather than a steady, predictable expansion pattern.
Free cash flow is one of the more constructive parts of the picture. Over the last several years, cash generation improved meaningfully, even if it has come down from peak levels. Current trailing free cash flow remains positive and sizeable for a company of Talos’s scale, which matters because offshore development requires ongoing capital spending and balance-sheet flexibility.
A potentially important catalyst is the company’s carbon capture and storage platform. It is not yet a major revenue source, but it offers a possible second leg of growth over time if projects move from permitting and partnerships into commercial operation. In addition, any successful execution of new Gulf developments, reserve additions, or accretive bolt-on acquisitions could materially change the production base. Recent corporate updates have also highlighted continued focus on portfolio optimization and operational delivery, both of which are central to whether Talos can convert asset depth into sustained earnings growth.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


