Stock Analysis · Tabcorp Holdings Limited (TABCF)
Overview
Tabcorp Holdings Limited is an Australian gambling and wagering company best known for sports betting, racing wagering, media linked to racing, and gaming services for venues such as pubs and clubs. After separating its lotteries business in 2022, Tabcorp became a more focused betting-and-gaming operator. Its activities now center on three main areas: the TAB wagering brand, media and broadcasting assets connected to racing, and gaming services that support electronic gaming machines in licensed venues.
The business earns money from several distinct revenue streams. Based on recent annual reporting, the mix is approximately as follows:
- Wagering and Media – about 75% to 80%: this is the core business. It includes fixed-odds and pari-mutuel betting on racing and sports, digital betting through apps and websites, retail betting in agencies and venues, and media income from racing channels, vision distribution, and related content services.
- Gaming Services – about 20% to 25%: this mainly covers monitoring and service fees tied to electronic gaming machines, especially in Queensland, together with venue-facing technology and support services.
- Other revenue – small remainder: this includes smaller corporate and ancillary items that are not major earnings drivers.
That revenue structure matters because Tabcorp is no longer cushioned by the steadier lotteries business it once owned. The company is now much more directly exposed to the competitive and regulated wagering market, where customer acquisition costs, technology quality, and product appeal all have a large influence on results.
The long-term picture shows a business that has kept revenue around the low-to-mid A$2 billion range in recent years, but profitability has been uneven. Operating performance improved from the difficult 2024 period into 2025 and 2026, yet net earnings remain relatively thin compared with sales. In simple terms, Tabcorp still generates sizable customer activity, but converting that into durable profit has been the harder part.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Consumer Cyclical | |
| Industry | Gambling | |
| Market Cap ⓘ | $1.45B | |
| Beta ⓘ | 0.36 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 63.00 | 16.89 |
| P/B Ratio ⓘ | 1.18 | 1.61 |
| FCF Yield ⓘ | 30.93% | 8.99% |
| Dividend Yield ⓘ | 4.76% | 2.73% |
| EBIT / EV ⓘ | 13.50% | 6.69% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 0.50% | 5.60% |
| RPS Growth (5Y CAGR) ⓘ | -3.58% | 8.91% |
| EPS Growth (5Y CAGR) ⓘ | N/A | -17.41% |
| BVPS Growth (5Y CAGR) ⓘ | -18.36% | 5.62% |
| Margin Growth (5Y Trend) ⓘ | 11.62% | -0.17% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 4.91% |
| DPS Growth (5Y CAGR) ⓘ | -35.47% | 9.86% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 12.38% |
| ROA (Latest) ⓘ | N/A | 5.49% |
| ROIC (5Y Median) ⓘ | 3.40% | 10.75% |
| ROA (5Y Median) ⓘ | 1.46% | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | 1.99 | 2.17 |
| Net Debt / EBIT (5Y Median) ⓘ | 2.81 | 2.30 |
| Net Debt / EBITDA (Latest) ⓘ | 1.21 | 1.50 |
| Net Debt / Assets ⓘ | 16.46% | 21.57% |
| EBITDA / Interest ⓘ | N/A | 9.13 |
| Operating Margin (Latest) ⓘ | N/A | 9.10% |
| Operating Margin (5Y Median) ⓘ | 4.70% | 9.56% |
| Debt to Equity (Latest) ⓘ | 65.97% | 75.99% |
| Profit Margin (Latest) ⓘ | 1.75% | 5.31% |
| Free Cash Flow (Latest) ⓘ | $447.10M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +12.32% | +15.94% |
| 12M Return (excl. last month) ⓘ | +16.36% | -2.82% |
| 6M Return ⓘ | -2.87% | -1.58% |
| Price vs. 200-Day MA ⓘ | -48.31% | -3.31% |
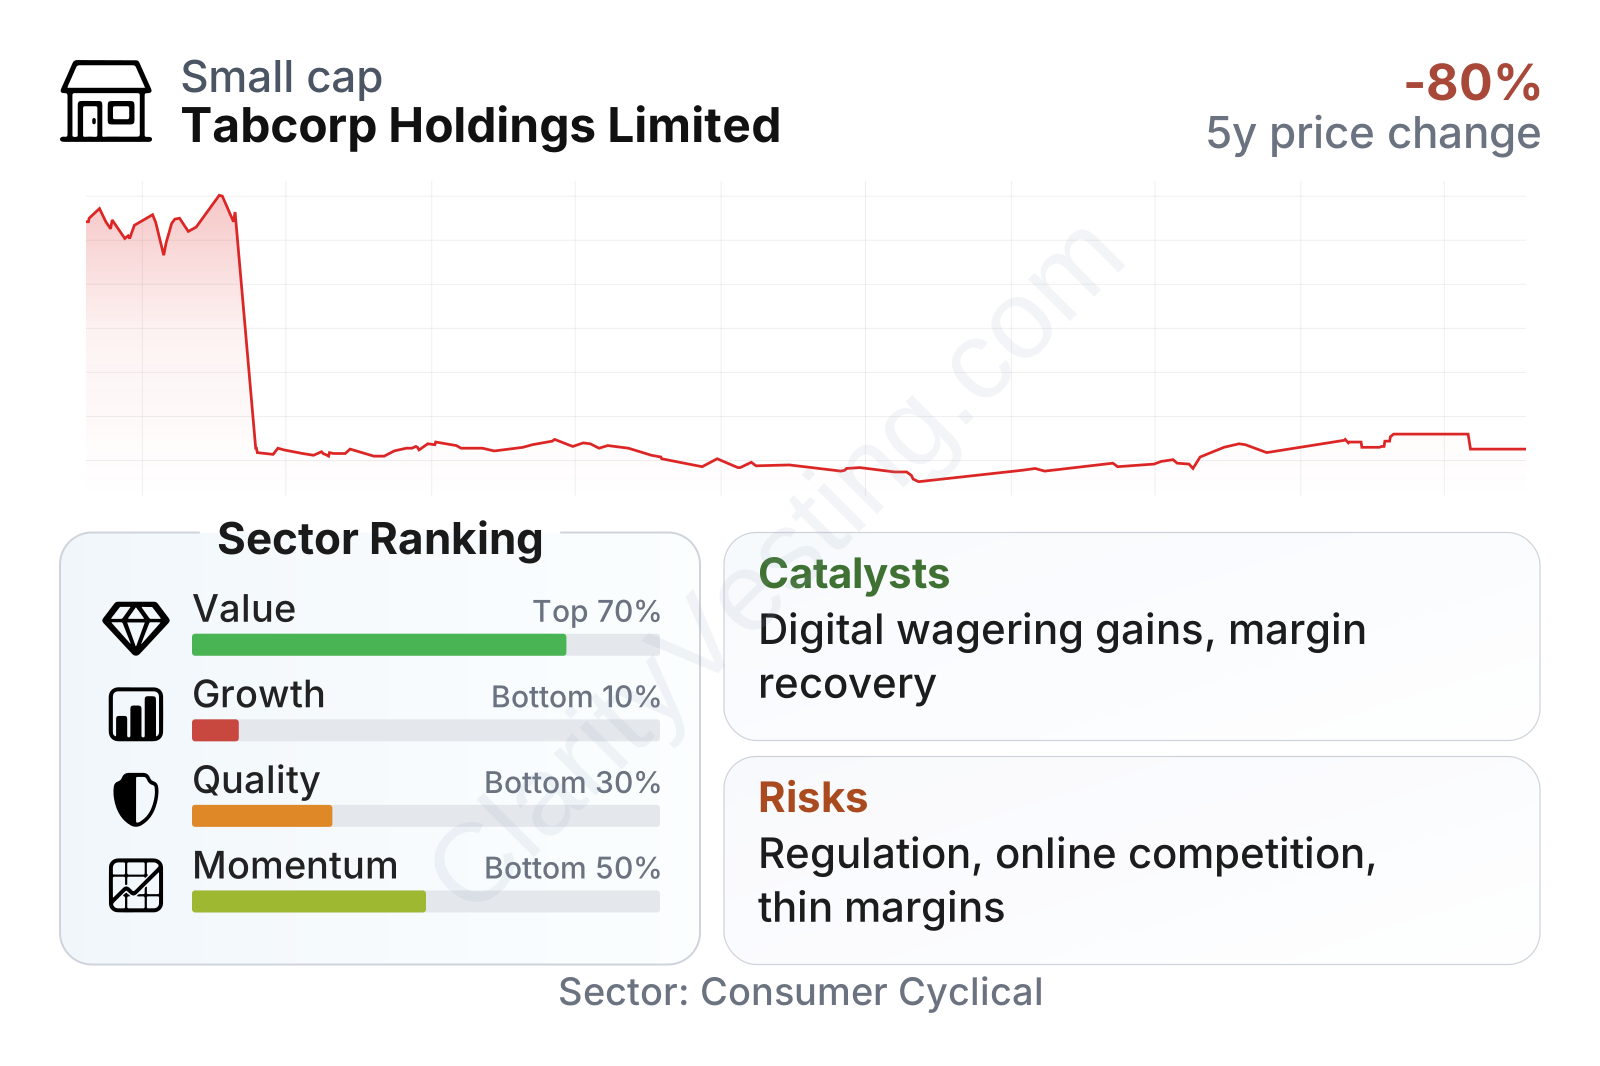
Tabcorp is a mid-sized company with a low beta, meaning its share price has historically moved less than the broader market. The mixed picture comes from the underlying factors: valuation measures look stronger than much of the sector on cash flow and enterprise-value-based metrics, but growth ranks near the bottom of the group and quality is below average. The dividend yield is above the sector median, and free cash flow is notably strong, yet the earnings multiple based on reported profit looks elevated because net income remains modest relative to sales and cash generation.
The stock history also shows why the company attracts debate. Shares are far below the levels seen around the 2021 period, reflecting the lotteries separation, competitive pressure, and profit volatility. There was a strong run over the last year before a pullback, which suggests the market has been reacting quickly to operational updates rather than treating the business as a steady compounder.
Growth
Tabcorp operates in a sector that has a real digital growth angle, but it is not a simple high-growth industry. Online sports betting and app-based wagering continue to take share from older retail channels, and media rights around racing still have value. However, the market is mature in Australia, competition is intense, and regulation can offset some of the natural demand growth.
The company’s strategy for future expansion is centered less on entering a brand-new market and more on improving execution in the one it already knows well. That includes upgrading technology, improving the digital betting experience, using the TAB brand more effectively, strengthening its racing ecosystem, and extracting more value from omni-channel customers who use both physical and digital betting options.
Recent growth numbers suggest only limited top-line momentum. Revenue growth has been close to flat on a year-over-year basis, while five-year revenue per share has declined. That points to a company still in a rebuilding phase rather than one enjoying broad-based expansion. The more encouraging element is margin recovery: operating margin trends over the last five years have improved, even if they still sit below stronger peers. In plain language, Tabcorp’s main growth opportunity may come more from becoming a better operator than from relying on a rapidly expanding market.
A meaningful catalyst is the ongoing shift toward digital wagering. If Tabcorp can retain more customers in its own app ecosystem and improve product competitiveness, even modest revenue growth could have an outsized effect on profit because betting businesses often benefit when fixed costs are spread across a larger activity base. Another potential support comes from its close ties to Australian racing, where content, distribution, and wagering can reinforce one another.
Recent company updates have also emphasized operational improvement and simplification. That is important because the strongest upside case for Tabcorp depends on execution: better pricing discipline, more efficient marketing, smoother technology, and greater monetization of its retail-plus-digital footprint.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


