Stock Analysis · Shenzhou International Group Holdings Limited (SZHIF)
Overview
Shenzhou International Group Holdings Limited is a large apparel manufacturing company best known for producing knitted sportswear, casualwear, and innerwear for global clothing brands. The group operates as an integrated manufacturer, which means it handles several stages of production itself rather than relying heavily on outside suppliers. Its operations cover fabric knitting, dyeing, printing, cutting, sewing, and finishing. This model gives the company tighter control over quality, delivery times, and production efficiency.
The business mainly earns revenue from making garments for major international brand customers. Based on the company’s annual disclosures, revenue is largely organized by product category rather than by retail brand, with sportswear and casualwear typically representing the largest share. A practical breakdown of revenue sources is:
- Sportswear: approximately 68% of revenue in recent annual reporting periods. This includes performance apparel and athletic garments produced for large global sports brands.
- Casualwear: approximately 24% of revenue. This covers everyday clothing such as T-shirts, hoodies, and similar leisure apparel.
- Lingerie and innerwear: approximately 7% of revenue. This includes underwear, bras, and related products.
- Other knitwear products: approximately 1% of revenue. This is a smaller category that can include specialized or miscellaneous garments.
Geographically, the company serves global brands rather than depending on one domestic consumer market. Production is spread across China and Southeast Asia, especially Vietnam and Cambodia, which is important because many apparel customers want diversified sourcing outside a single country.
Over the last several years, the business has shown a clear ability to convert revenue into profit and cash flow at a level that is stronger than many companies in the broader consumer cyclical sector. Revenue moved from roughly HK$23.8 billion in 2021 to about HK$30.2 billion in 2025, while profitability expanded materially after the post-pandemic disruption period. That pattern suggests scale advantages and operating discipline rather than growth at any cost.
The operating profile has improved meaningfully since 2021. Revenue has climbed overall, while operating income and net income have risen faster than sales over the full period, indicating better efficiency and a healthier margin structure than earlier in the cycle.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Consumer Cyclical | |
| Industry | Textile Manufacturing | |
| Market Cap ⓘ | $11.48B | |
| Beta ⓘ | 1.10 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 14.15 | 16.89 |
| P/B Ratio ⓘ | 0.27 | 1.61 |
| FCF Yield ⓘ | 64.66% | 8.99% |
| Dividend Yield ⓘ | 22.07% | 2.73% |
| EBIT / EV ⓘ | N/A | 6.69% |
| PEG ⓘ | 1.04 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -5.30% | 5.60% |
| RPS Growth (5Y CAGR) ⓘ | 6.08% | 8.91% |
| EPS Growth (5Y CAGR) ⓘ | -32.17% | -17.41% |
| BVPS Growth (5Y CAGR) ⓘ | 7.81% | 5.62% |
| Margin Growth (5Y Trend) ⓘ | 3.77% | -0.17% |
| FCF Growth (5Y CAGR) ⓘ | 18.75% | 4.91% |
| DPS Growth (5Y CAGR) ⓘ | 7.83% | 9.86% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 23.43% | 12.38% |
| ROA (Latest) ⓘ | 20.02% | 5.49% |
| ROIC (5Y Median) ⓘ | 8.79% | 10.75% |
| ROA (5Y Median) ⓘ | 10.31% | 5.44% |
| Net Debt / EBIT (Latest) ⓘ | -0.03 | 2.17 |
| Net Debt / EBIT (5Y Median) ⓘ | 0.27 | 2.30 |
| Net Debt / EBITDA (Latest) ⓘ | -0.02 | 1.50 |
| Net Debt / Assets ⓘ | -0.65% | 21.57% |
| EBITDA / Interest ⓘ | N/A | 9.13 |
| Operating Margin (Latest) ⓘ | 20.79% | 9.10% |
| Operating Margin (5Y Median) ⓘ | 16.08% | 9.56% |
| Debt to Equity (Latest) ⓘ | 39.94% | 75.99% |
| Profit Margin (Latest) ⓘ | 15.07% | 5.31% |
| Free Cash Flow (Latest) ⓘ | $7.42B | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -23.29% | +15.94% |
| 12M Return (excl. last month) ⓘ | -7.36% | -2.82% |
| 6M Return ⓘ | +4.03% | -1.58% |
| Price vs. 200-Day MA ⓘ | -20.02% | -3.31% |
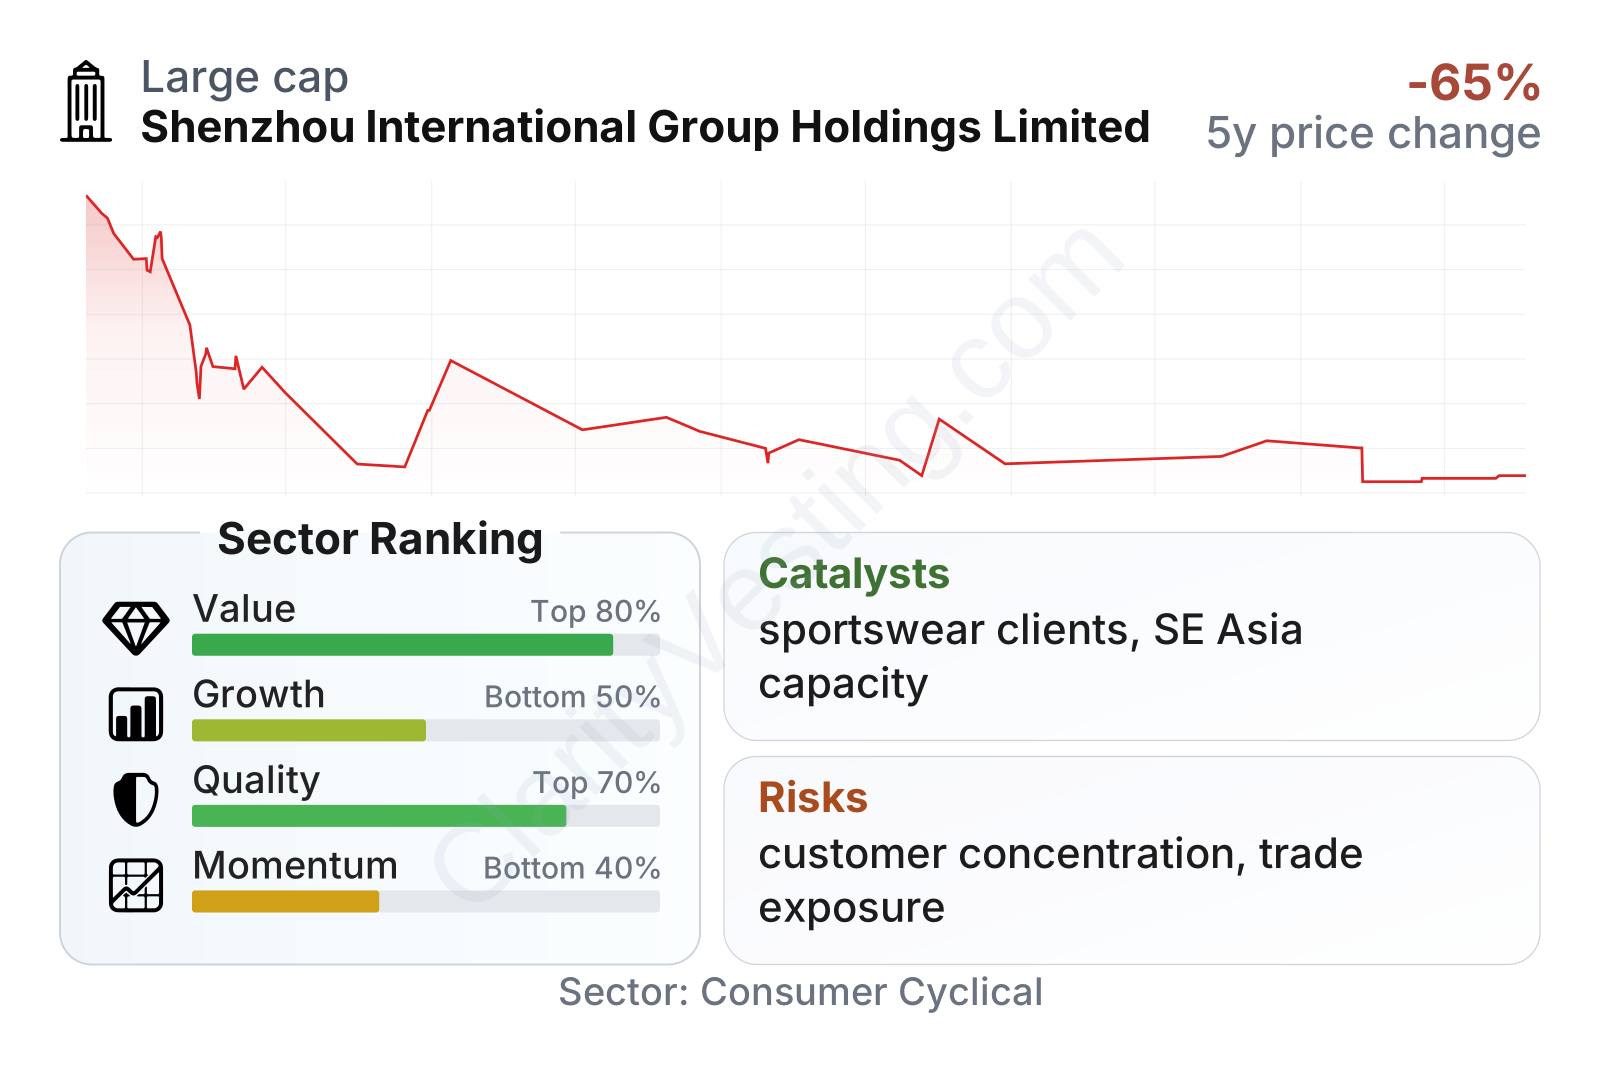
Shenzhou International stands out more for profitability, cash generation, and balance sheet strength than for recent top-line momentum. Quality metrics are comfortably above sector norms, with returns on assets and invested capital well ahead of the median and operating margins also much stronger than typical peers. The value profile also looks unusual: earnings multiple is below the sector median, free cash flow yield is very high, and leverage is modest. The weaker area is growth, where recent revenue and earnings trends have lagged the sector, and market momentum remains soft after a large multiyear share-price decline.
Growth
The company operates in a sector that is mature but still relevant for long-term expansion: outsourced apparel manufacturing for global brands. This is not a high-growth technology market, yet there are durable drivers behind it. International sportswear and athleisure demand has grown over time, global brands continue to rely on specialized contract manufacturers, and customers increasingly prefer suppliers that can offer large scale, product consistency, and multi-country production capacity. Shenzhou fits that profile well.
Its strategy also makes industrial sense. Rather than competing only on low labor costs, the company has built an integrated manufacturing system and long-standing relationships with major global customers. That can be difficult to replicate because apparel brands value reliable delivery, product development capability, and quality control as much as simple unit cost. The presence of production bases outside China also supports future order allocation as brand customers diversify sourcing across Asia.
Near-term growth has been less impressive than the company’s longer-term operating record. Recent year-over-year revenue growth has been negative, and five-year earnings growth has been pressured by cycle swings. Even so, free cash flow growth over five years has been strong, and the operating margin trend has improved, which suggests the company has been strengthening the economics of the business even when sales growth has not been consistently strong.
A meaningful catalyst is customer concentration in premium global sportswear brands that continue to launch technical apparel and expand internationally. If brand inventories normalize and order patterns improve, a manufacturer with Shenzhou’s scale and quality reputation can benefit disproportionately. Capacity ramp-up in Southeast Asia is another important opportunity because many customers increasingly want a broader sourcing footprint for geopolitical and supply-chain reasons.
Recent company reporting also indicates continued emphasis on advanced fabric capability, automation, and overseas capacity. Those are not headline-grabbing developments, but they matter in this industry because they can support margin resilience and make the company more valuable to large multinational clients looking for dependable long-term suppliers.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


