Stock Analysis · Sensient Technologies Corporation (SXT)
Overview
Sensient Technologies Corporation is a specialty ingredients company that develops colors, flavors, and other formulation systems used mainly in food, beverages, pharmaceuticals, nutraceuticals, cosmetics, and personal care products. In simple terms, it sells the ingredients that help finished products look better, taste better, and perform more consistently. This is generally a business with repeat demand because customers need these inputs every day across many consumer categories.
The company’s revenue is organized primarily by operating segment. Based on recent annual reporting, the business mix is centered on colors and flavors, with a smaller Asia-Pacific segment. Approximate revenue contribution is as follows:
- Color Group: about 57% — natural and synthetic colors, color systems, cosmetic pigments, pharmaceutical colors, and ingredients used in food, beverage, beauty, and personal care applications.
- Flavor Group: about 34% — flavors, flavor extracts, seasonings, and ingredient systems used in food, beverage, and certain health-related products.
- Asia Pacific Group: about 9% — regional sales across colors, flavors, and related ingredients, including local manufacturing and commercialization.
Sensient is not a commodity chemical producer in the traditional sense. Its products are more specialized, often tailored to customer formulations, regulatory requirements, and local consumer preferences. That usually supports better margins than bulk chemical businesses, although it also requires ongoing product development, customer relationships, and regulatory know-how.
Over the last several years, revenue has moved gradually upward, from roughly $1.38 billion in 2021 to about $1.61 billion in 2025. Operating income and net income also recovered after a weaker 2023, suggesting that the business has been able to regain some efficiency as volumes and pricing improved. Selling and administrative costs remain substantial, which is typical for an ingredient company that depends on technical selling, formulation support, and global customer service.
The long-term pattern is fairly constructive: sales have trended higher, gross profit has expanded, and earnings have recovered from the 2023 dip. One caution point is that interest expense has also risen over time, which matters because debt is a more important part of the capital structure than for many peers.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 03, 2026 | |
| Context | ||
| Sector | Basic Materials | |
| Industry | Specialty Chemicals | |
| Market Cap ⓘ | $5.48B | |
| Beta ⓘ | 0.78 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 34.70 | 17.61 |
| P/B Ratio ⓘ | 4.43 | 1.77 |
| FCF Yield ⓘ | 0.08% | 5.87% |
| Dividend Yield ⓘ | 1.27% | 2.06% |
| EBIT / EV ⓘ | 3.80% | 6.43% |
| PEG ⓘ | 1.74 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 11.60% | 11.30% |
| RPS Growth (5Y CAGR) ⓘ | 3.75% | 4.46% |
| EPS Growth (5Y CAGR) ⓘ | -9.75% | -13.11% |
| BVPS Growth (5Y CAGR) ⓘ | 5.99% | 5.51% |
| Margin Growth (5Y Trend) ⓘ | 0.53% | -1.57% |
| FCF Growth (5Y CAGR) ⓘ | -17.87% | 0.55% |
| DPS Growth (5Y CAGR) ⓘ | 0.88% | 6.02% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 9.31% | 9.31% |
| ROA (Latest) ⓘ | 6.90% | 4.94% |
| ROIC (5Y Median) ⓘ | 9.44% | 7.91% |
| ROA (5Y Median) ⓘ | 6.30% | 3.93% |
| Net Debt / EBIT (Latest) ⓘ | 3.06 | 1.40 |
| Net Debt / EBIT (5Y Median) ⓘ | 3.20 | 1.70 |
| Net Debt / EBITDA (Latest) ⓘ | 2.71 | 0.91 |
| Net Debt / Assets ⓘ | 30.91% | 13.69% |
| EBITDA / Interest ⓘ | 8.73 | 11.93 |
| Operating Margin (Latest) ⓘ | 14.05% | 13.07% |
| Operating Margin (5Y Median) ⓘ | 12.32% | 11.86% |
| Debt to Equity (Latest) ⓘ | 60.63% | 40.43% |
| Profit Margin (Latest) ⓘ | 9.27% | 6.57% |
| Free Cash Flow (Latest) ⓘ | $4.48M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +137.17% | +65.06% |
| 12M Return (excl. last month) ⓘ | +20.79% | +36.05% |
| 6M Return ⓘ | +52.26% | +1.89% |
| Price vs. 200-Day MA ⓘ | +19.54% | +1.03% |
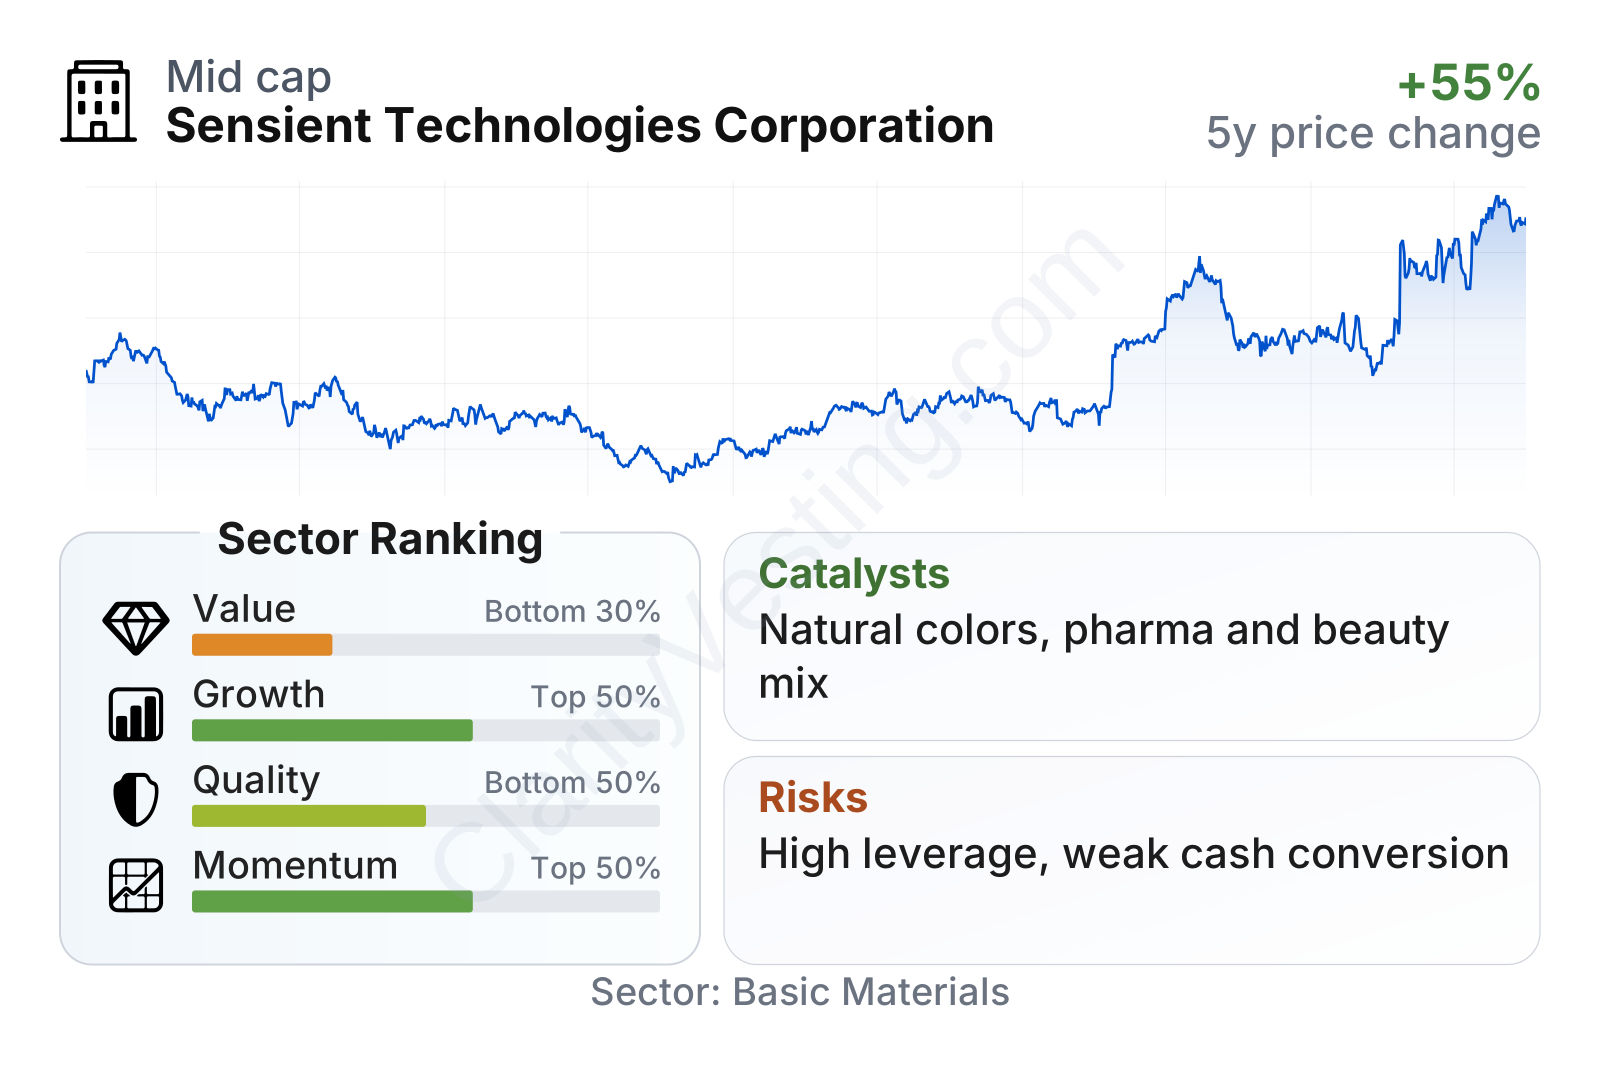
Sensient is a mid-sized specialty chemicals company with a market value around the mid-single-digit billions and a stock that has historically shown lower volatility than the broader market. The factor mix is unusual: growth and momentum look decent, and profitability is solid, but value metrics are weak. The shares trade at a noticeably higher earnings and book multiple than the sector median, while free cash flow yield is especially thin. Quality is mixed rather than poor: returns on capital and assets are respectable, but leverage pulls the overall picture down.
The stock price history also shows a sharp rerating. After a prolonged weak period through 2023, the shares rebounded strongly through 2025 and remained elevated into 2026. That helps explain why valuation now looks less forgiving than the company’s operating profile alone might suggest.
Growth
Sensient operates in categories that benefit from durable long-term demand rather than explosive disruption. Food and beverage formulation, natural colors, clean-label reformulation, pharmaceutical coatings, and cosmetic pigments are all supported by recurring end-market consumption. That makes this a growth business in a steady, compounding sense: customers refresh products, regulators change standards, and brands increasingly seek specialty ingredients that can meet performance and labeling requirements at the same time.
A particularly important growth angle is the shift toward natural colors. Food, beverage, and personal care companies continue to reformulate away from certain synthetic ingredients in response to regulation, retailer standards, and consumer preferences. Sensient has spent years building extraction, formulation, and application expertise in natural color systems, which can make it a useful partner when customers need performance across shelf life, heat stability, acidity, or shade consistency. This is one of the clearer strategic reasons the company may be able to grow faster than a plain-vanilla ingredients supplier.
Its strategy also makes sense because the business is diversified across end uses and geographies, but still focused on high-value formulation niches. A customer that develops a successful beverage, vitamin gummy, lipstick, or coated tablet often needs ongoing supply and technical support, which can create repeat business and switching friction. That is not the same as having total pricing power, but it can make revenue more resilient over time.
Recent revenue growth has improved meaningfully. After a slower stretch in 2023 and moderate growth in 2024 and 2025, year-over-year revenue growth accelerated into the low-double-digit range in 2026. That suggests demand and mix have strengthened at the same time, which is usually more encouraging than growth driven by price alone.
Free cash flow is the softer part of the growth profile. It has been positive overall but somewhat uneven, and the latest trailing twelve-month figure is quite low relative to the company’s size. That does not erase the operating progress, but it does mean that earnings growth has not translated into equally strong cash generation recently. For a specialty ingredients company, sustained growth tends to look more convincing when revenue, margins, and cash conversion all move together.
As a recent business catalyst, the company has continued emphasizing color innovation, especially natural and specialty systems, while also expanding capabilities that serve pharmaceuticals and personal care. Those are attractive submarkets because they often demand regulatory expertise and application support, not just low-cost production. If that mix keeps improving, Sensient could continue lifting margins even without dramatic top-line acceleration.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


