Stock Analysis · Standex International Corporation (SXI)
Overview
Standex International Corporation is a diversified industrial manufacturer. The company designs and produces engineered products used in food service equipment, electronics, engraving, scientific and medical applications, specialty hydraulics, and aerospace and defense. In simple terms, Standex sells highly specialized components and systems rather than broad commodity products, which helps it serve niche markets where technical know-how matters.
Its business model is spread across several operating segments, which reduces dependence on a single end market. Based on the latest company reporting, revenue is mainly generated from the following sources, listed from largest to smallest:
- Electronics: about 30% to 35% of revenue. This segment includes magnetic components, power magnetics, sensing technologies, and other engineered electronic products used in industrial, aerospace, defense, and medical applications.
- Engraving: about 20% to 25% of revenue. This activity includes mold texturizing, roll engraving, and industrial marking solutions used in packaging, automotive, and product identification.
- Scientific: about 15% to 20% of revenue. This segment serves laboratory equipment, medical refrigeration, and other controlled-temperature applications.
- Engineering Technologies: about 15% to 20% of revenue. It includes specialty hydraulic cylinders, aviation refueling systems, and related engineered products.
- Specialty Solutions: about 10% to 15% of revenue. This segment includes food service equipment and custom industrial solutions.
That mix shows an important feature of Standex: it is not a single-product company. It participates in several specialized industrial niches, and management has increasingly emphasized businesses with better margins, stronger intellectual property, and more exposure to long-term themes such as electrification, aerospace demand, and medical or laboratory equipment.
The latest financial flow also suggests a meaningful step-up in operating performance. Revenue has moved higher over the last few years, but the stronger signal is margin expansion: gross profit and operating income improved faster than sales in the most recent annual period, which points to a business mix shifting toward more profitable activities.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 17, 2026 | |
| Context | ||
| Sector | Industrials | |
| Industry | Specialty Industrial Machinery | |
| Market Cap ⓘ | $3.47B | |
| Beta ⓘ | 1.07 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | 32.57 | 22.10 |
| P/B Ratio ⓘ | 4.37 | 1.97 |
| FCF Yield ⓘ | 1.45% | 6.38% |
| Dividend Yield ⓘ | 0.48% | 1.94% |
| EBIT / EV ⓘ | 5.11% | 4.79% |
| PEG ⓘ | 0.95 | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | 2.80% | 9.30% |
| RPS Growth (5Y CAGR) ⓘ | 5.05% | 7.81% |
| EPS Growth (5Y CAGR) ⓘ | 10.43% | -13.06% |
| BVPS Growth (5Y CAGR) ⓘ | 11.02% | 6.14% |
| Margin Growth (5Y Trend) ⓘ | 8.12% | 0.88% |
| FCF Growth (5Y CAGR) ⓘ | 4.71% | 11.01% |
| DPS Growth (5Y CAGR) ⓘ | 7.33% | 9.48% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | 12.22% | 10.84% |
| ROA (Latest) ⓘ | 6.66% | 5.41% |
| ROIC (5Y Median) ⓘ | 10.96% | 9.38% |
| ROA (5Y Median) ⓘ | 6.64% | 4.95% |
| Net Debt / EBIT (Latest) ⓘ | 1.94 | 2.08 |
| Net Debt / EBIT (5Y Median) ⓘ | 1.09 | 2.27 |
| Net Debt / EBITDA (Latest) ⓘ | 1.61 | 1.39 |
| Net Debt / Assets ⓘ | 23.65% | 19.28% |
| EBITDA / Interest ⓘ | 7.56 | 9.58 |
| Operating Margin (Latest) ⓘ | 21.72% | 10.50% |
| Operating Margin (5Y Median) ⓘ | 13.60% | 10.29% |
| Debt to Equity (Latest) ⓘ | 73.33% | 65.48% |
| Profit Margin (Latest) ⓘ | 11.74% | 6.67% |
| Free Cash Flow (Latest) ⓘ | $50.20M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | +90.29% | +61.68% |
| 12M Return (excl. last month) ⓘ | +26.70% | +12.58% |
| 6M Return ⓘ | +1.61% | 0.00% |
| Price vs. 200-Day MA ⓘ | -0.90% | +0.02% |
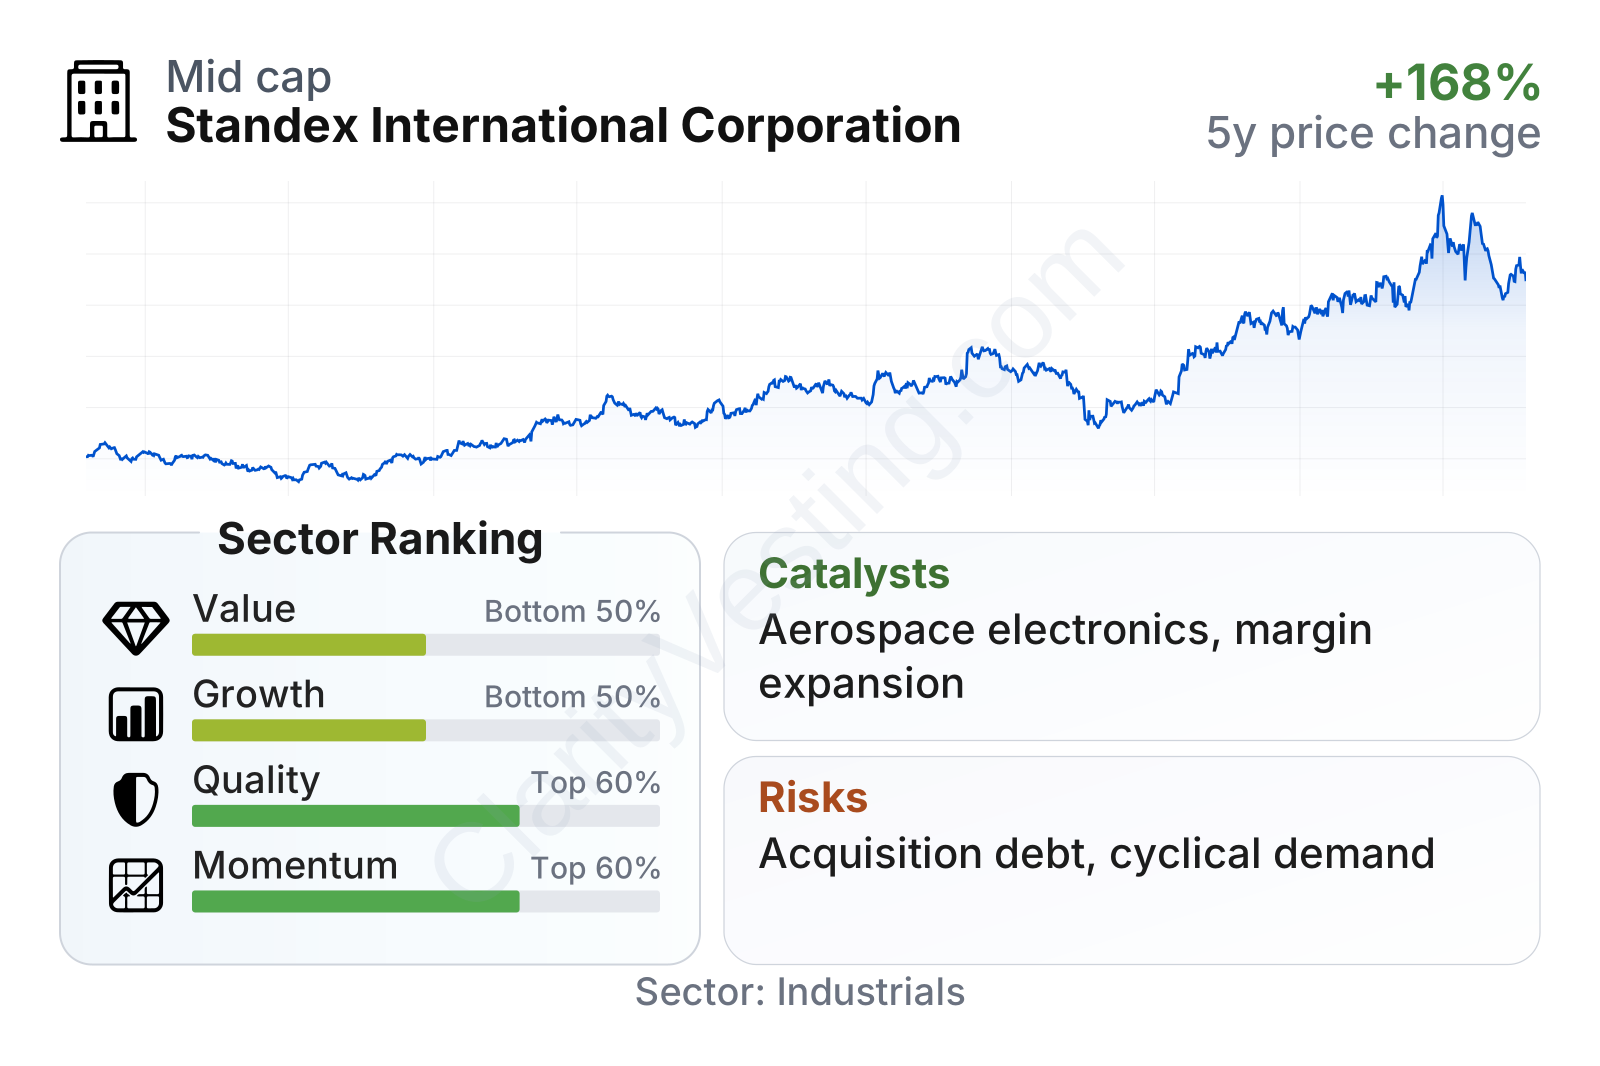
Standex is a mid-sized industrial company with a market value a little above $3 billion, so it is far smaller than the biggest multi-industry groups but large enough to operate globally. The quality profile looks solid: returns on capital and assets are above the sector median, and operating margin is notably stronger than many peers. Growth metrics are more mixed, with recent revenue expansion trailing the sector median even though earnings growth over five years has been strong. The valuation profile is less favorable, as the stock trades at a premium on earnings and book value while offering a low free-cash-flow yield and a very small dividend yield. Price performance has been strong over one year and three years, which helps explain why the market is assigning a richer multiple.
Growth
Standex operates in industrial niches that are not all fast-growing on their own, but several of its end markets have attractive long-term demand drivers. Electronics tied to power systems, aerospace and defense components, sensing technologies, and specialized scientific equipment all benefit from structural trends such as electrification, automation, higher reliability requirements, and continuing investment in medical and laboratory infrastructure. That gives the company better growth potential than a traditional cyclical machinery supplier focused only on general industrial demand.
Management’s strategy also appears coherent for future expansion. Over time, Standex has been reshaping the portfolio toward higher-value businesses with stronger margins and more technical differentiation. This matters because a smaller industrial company usually cannot win by scale alone; it needs to compete through engineering depth, customization, and niche leadership. The strong operating margin relative to the sector suggests this approach has had real results.
Recent sales growth has not been perfectly smooth. Revenue growth weakened in parts of 2023 and 2024, then rebounded sharply through much of 2025 before moderating again in 2026. That pattern suggests the company still has cyclical exposure, but it also shows the portfolio can recover well when demand normalizes and acquisitions or mix improvements help. The latest year-over-year growth rate is modest, around 3%, which is below the sector median, so the current growth picture is positive but not especially fast.
Cash generation adds another layer to the growth discussion. Free cash flow has been positive, but it has also been somewhat uneven from year to year. That is common in industrial companies because working capital, inventory, and project timing can create swings. Even so, positive free cash flow gives Standex room to keep investing in product development, bolt-on acquisitions, and manufacturing improvements without relying entirely on external financing.
A notable catalyst is the company’s exposure to higher-specification electronics and aerospace-related applications, where customers often care more about performance and reliability than the lowest upfront price. Another is continued portfolio optimization: if Standex keeps adding specialized businesses and pruning lower-return operations, it could improve both growth quality and margins. Recent company communications have also highlighted acquisition activity and integration efforts as part of the expansion plan, which remains an important lever for a company of this size.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer


