Stock Analysis · SavMobi Technology Inc (SVMB)
Overview
SavMobi Technology Inc is a small software company focused on mobile and application-related technology. Based on its public filings and financial profile, the business appears to be centered on software application products and services rather than a broad, diversified technology platform. The company is still in an early and unstable stage of development: revenue is modest, losses are large relative to sales, and operating results have been highly volatile over the last several years.
The biggest practical point for long-term readers is that SavMobi is not currently a mature software business generating recurring profits from a scaled customer base. Instead, it looks more like a company still trying to establish a durable commercial model while managing shrinking sales and ongoing operating losses.
Publicly available information does not provide a detailed revenue split by product line that is reliable enough to present precise percentages by segment. Based on the company’s filings, revenue appears to come primarily from software-related operations and associated services, but the available disclosures do not clearly break this down into major recurring categories.
What can be said with reasonable confidence is that the company’s revenue base is narrow and small. Over the last five reported fiscal years shown here, annual revenue moved from about $3.6 million in fiscal 2023 to about $1.5 million in fiscal 2026, with costs of revenue regularly exceeding sales. That means the issue is not just slow growth; the basic unit economics have also been weak.
The overall income flow shows a business where revenue has remained limited, gross profit has been negative in recent years, and selling and administrative costs have consumed far more than the company brings in. Operating expenses have come down, which shows some cost control, but that improvement has not yet been enough to move the company anywhere near profitability.
Key Figures
| Metric | Value | Sector ⓘ |
|---|---|---|
| Date | Oct 31, 2026 | |
| Context | ||
| Sector | Technology | |
| Industry | Software - Application | |
| Market Cap ⓘ | $1.48B | |
| Beta ⓘ | -67.12 | |
Value (Cheapness) | ||
| P/E Ratio ⓘ | N/A | 29.73 |
| FCF Yield ⓘ | -0.16% | 3.96% |
| Dividend Yield ⓘ | N/A | 1.30% |
| EBIT / EV ⓘ | -0.44% | 2.90% |
| PEG ⓘ | N/A | |
Growth (Business expansion) | ||
| Revenue Growth ⓘ | -32.90% | 15.80% |
| RPS Growth (5Y CAGR) ⓘ | -45.85% | 8.54% |
| EPS Growth (5Y CAGR) ⓘ | -85.06% | -10.19% |
| Margin Growth (5Y Trend) ⓘ | N/A | 0.45% |
| FCF Growth (5Y CAGR) ⓘ | N/A | 9.80% |
| DPS Growth (5Y CAGR) ⓘ | N/A | 7.67% |
Quality (Business durability) | ||
| ROIC (Latest) ⓘ | N/A | 9.74% |
| ROIC (5Y Median) ⓘ | -74.22% | 8.31% |
| Net Debt / EBIT (Latest) ⓘ | N/A | 0.53 |
| Net Debt / EBIT (5Y Median) ⓘ | N/A | 0.46 |
| Net Debt / EBITDA (Latest) ⓘ | N/A | 0.29 |
| Net Debt / Assets ⓘ | 2.24% | 3.45% |
| EBITDA / Interest ⓘ | N/A | 13.54 |
| Operating Margin (Latest) ⓘ | -530.26% | 10.12% |
| Operating Margin (5Y Median) ⓘ | -276.29% | 8.50% |
| Debt to Equity (Latest) ⓘ | -0.65% | 35.18% |
| Profit Margin (Latest) ⓘ | N/A | 7.13% |
| Free Cash Flow (Latest) ⓘ | -$2.41M | |
Momentum (Price trend) | ||
| 3Y Return ⓘ | -99.11% | +61.79% |
| 12M Return (excl. last month) ⓘ | -80.43% | +12.78% |
| 6M Return ⓘ | +56.47% | +7.85% |
| Price vs. 200-Day MA ⓘ | +100.52% | +5.43% |
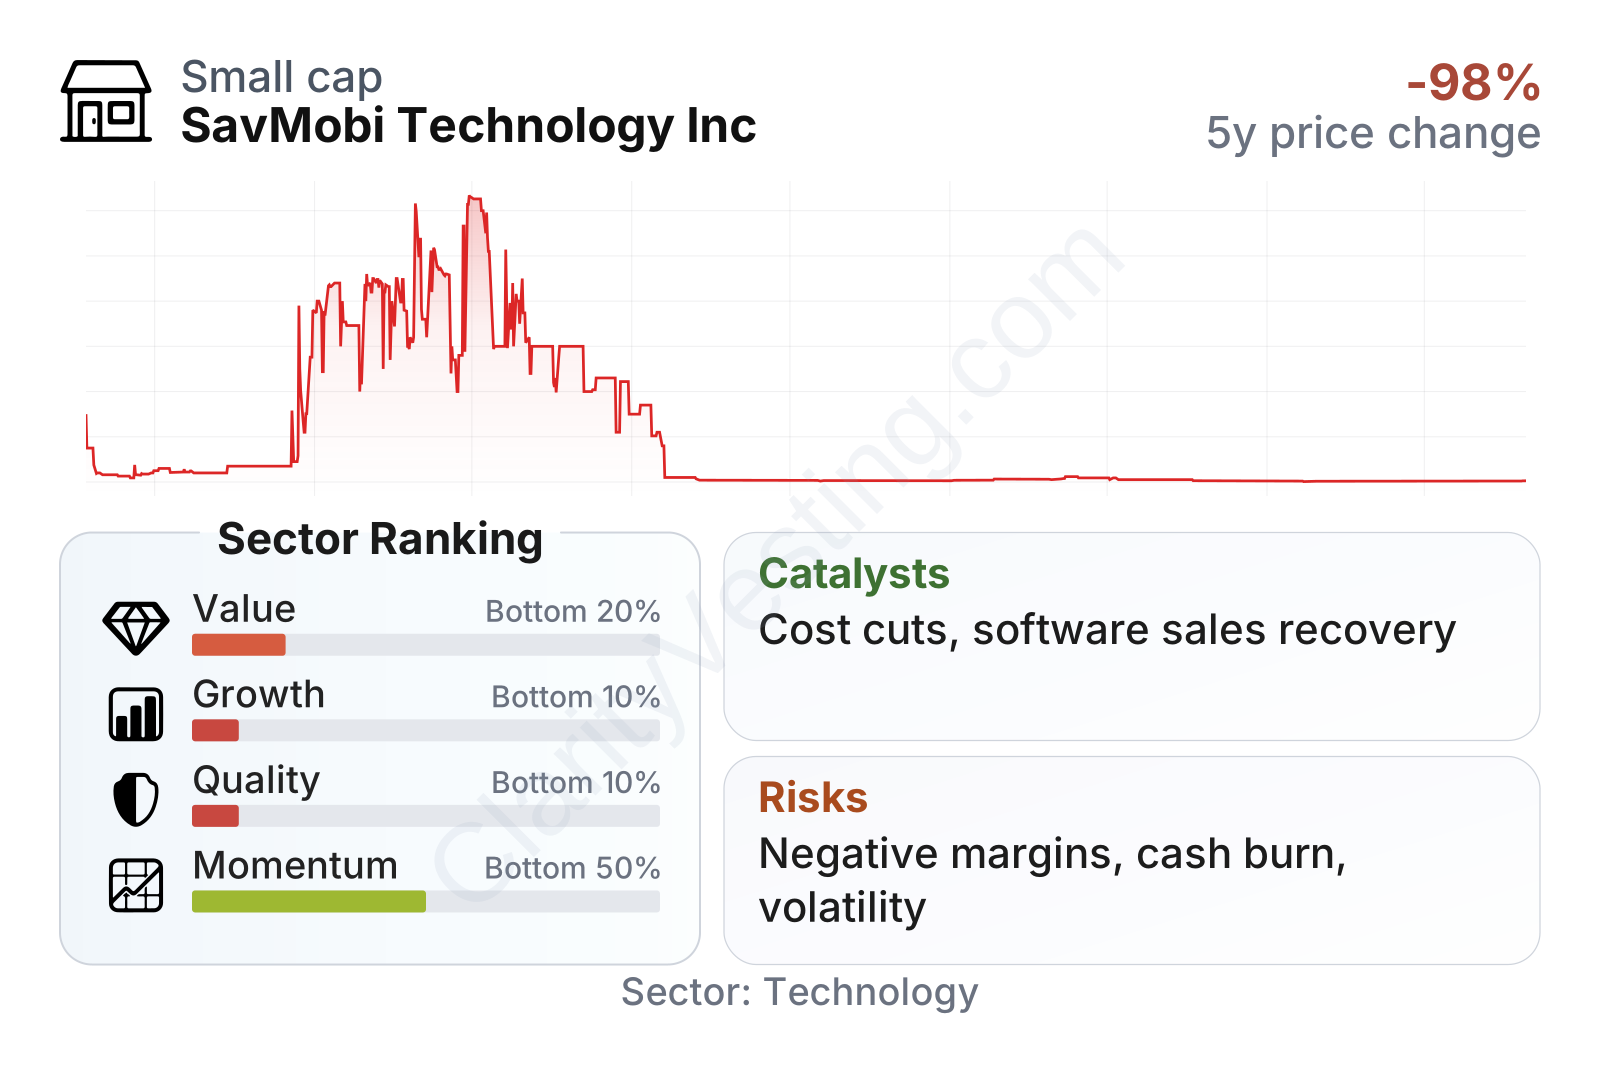
SavMobi is a small-cap software company, but its quality, growth, and valuation characteristics currently rank near the lower end of its sector. Growth metrics are especially weak, with revenue down about 33% year over year versus a technology software sector median that is still positive. Profitability is also far below normal sector levels, and free cash flow remains negative. The one brighter point is that leverage does not appear heavy on an asset basis, but that reflects the company’s capital structure more than operating strength. Price action has been extremely volatile: long-term returns have been very poor, even though shorter-term trading rebounds have occurred.
Growth
Software remains a growing sector overall, especially where companies offer sticky products, recurring subscriptions, or tools tied to mobile usage, automation, and digital services. In that broad sense, SavMobi operates in an area with long-term demand potential. The problem is that sector growth alone does not guarantee company growth. In SavMobi’s case, the business has not been participating in that industry expansion in a consistent way.
Revenue growth has been highly erratic. There were short periods of strong rebounds, including a sharp surge in late 2024 and another positive phase in early 2025, but those gains did not last. More recent readings have returned to meaningful year-over-year declines, around the low-30% to high-30% range. That kind of pattern usually points to a business with limited visibility, uneven demand, or customer concentration rather than one compounding steadily.
Cash generation also remains a major hurdle. Free cash flow has stayed negative over the periods shown, and the latest trailing figure is still around negative $2 million to negative $2.5 million. For a company with annual revenue around $1.5 million, that is a significant imbalance. It suggests that even if management is reducing expenses, the current scale of the business is still too small to support the cost base.
As for strategy, the most logical path to future improvement would be some combination of higher-value software sales, stronger recurring revenue, tighter operating discipline, and better gross margins. Cost cuts alone are unlikely to create a durable turnaround if revenue continues to contract. The company would need either a more competitive product offering, a clearer niche, or a commercial partnership that materially expands distribution.
No widely visible public development from trusted primary sources stands out as a near-term transformational catalyst on the scale of a major contract, platform breakthrough, or strategic acquisition. That does not mean opportunities do not exist, but at this stage the investment case depends more on execution and business stabilization than on a clearly identifiable external trigger.
Risks
This article is for informational purposes only and does not constitute financial advice. Some content is AI-generated. See Disclaimer